Precious Metals
June 19, 2025
3 min
Precious Metals


The first quarter of 2025 revealed a dynamic landscape for the world's leading silver producers. A detailed analysis of the Q1 2025 production figures, when compared to the same period in 2024, highlights a range of performances driven by various operational factors, strategic adjustments, and ongoing market conditions.
Significant Production Increases: Leaders in Growth
Several companies demonstrated substantial year-over-year growth in their silver output:
- First Majestic Silver Corp. led the increases with an impressive 87.55% rise, producing 3,704,503 ounces in Q1 2025, up from 1,975,176 ounces in Q1 2024. This significant jump was notably driven by the inclusion of attributable production from the Cerro Los Gatos mine, alongside an 11% increase from San Dimas operations, according to their first-quarter production report (Source).
- Coeur Mining Inc. Showed a robust 43.42% increase, with production climbing to 3,729,000 ounces in Q1 2025 from 2,600,000 ounces in the prior year. This growth was primarily attributed to the successful ramp-up of the major expansion project at its Rochester operation in Nevada (Source).
- BHP Group Ltd: Recorded a strong 35.29% increase, reaching 3,880,000 ounces in Q1 2025 compared to 2,868,000 ounces in Q1 2024. This was likely driven by strong refined gold and silver production from its Olympic Dam smelter and refinery (Source).
- Compania de Minas Buenaventura SAA: Experienced a healthy 19.80% increase, producing 3,678,636 ounces in Q1 2025, up from 3,070,773 ounces. This increase was primarily due to the full-scale operation at its Yumpag mine.
- Southern Copper Corp: Saw a notable 13.80% increase, with production climbing to 5,442,000 ounces in Q1 2025 from 4,782,000 ounces in Q1 2024. This rise in mined silver production was driven by improved performance at its Buenavista, IMSA, and Guajone operations (source).
- MAG Silver Corp: Reported an 11.86% increase, producing 4,469,000 ounces in Q1 2025 compared to 3,995,000 ounces in Q1 2024. This was supported by a 7% increase in mined tonnages at Juanicipio and improved silver metallurgical recovery (96% in Q1 2025 vs. 89% in Q1 2024, source: MAG Silver Reports First Quarter Financial Results).
Production Decreases: Navigating Challenges
Conversely, several major producers experienced declines in their silver output during the quarter, influenced by various operational headwinds and strategic adjustments:
- Newmont Corporation: Saw the most significant percentage decrease at -33.33%, with production dropping to 6,000,000 ounces in Q1 2025 from 9,000,000 ounces in Q1 2024, primarily due to planned mine sequencing and lower silver grades at its Peñasquito mine (Source).
- Fresnillo Plc: As the largest primary silver producer, reported an -8.15% decrease, with output falling to 12,400,000 ounces in Q1 2025 from 13,500,000 ounces in Q1 2024. This was largely attributed to planned mine closures (e.g., San Julián Disseminated Ore Body), lower ore grades, and operational challenges at certain sites. (Source)
- Glencore PLC: Experienced a -6.42% decrease, producing 4,230,000 ounces in Q1 2025, down from 4,520,000 ounces.
- Hindustan Zinc: Saw a -6.35% decrease, with production at 5,690,682 ounces in Q1 2025 compared to 6,076,490 ounces in the prior-year quarter.
Source: Data compiled from various company reports and industry sources
Disclaimer: The Q1 2025 silver production data and analysis in this article are provided for general informational purposes only. Figures are based on company disclosures and publicly available data compiled by MiningVisuals.com, including data from a summary image used for primary numerical alignment. While we aim for accuracy, we do not guarantee the completeness or correctness of all information presented.
This content is not intended as, and should not be relied upon as, financial or investment advice.


Explore More
View All

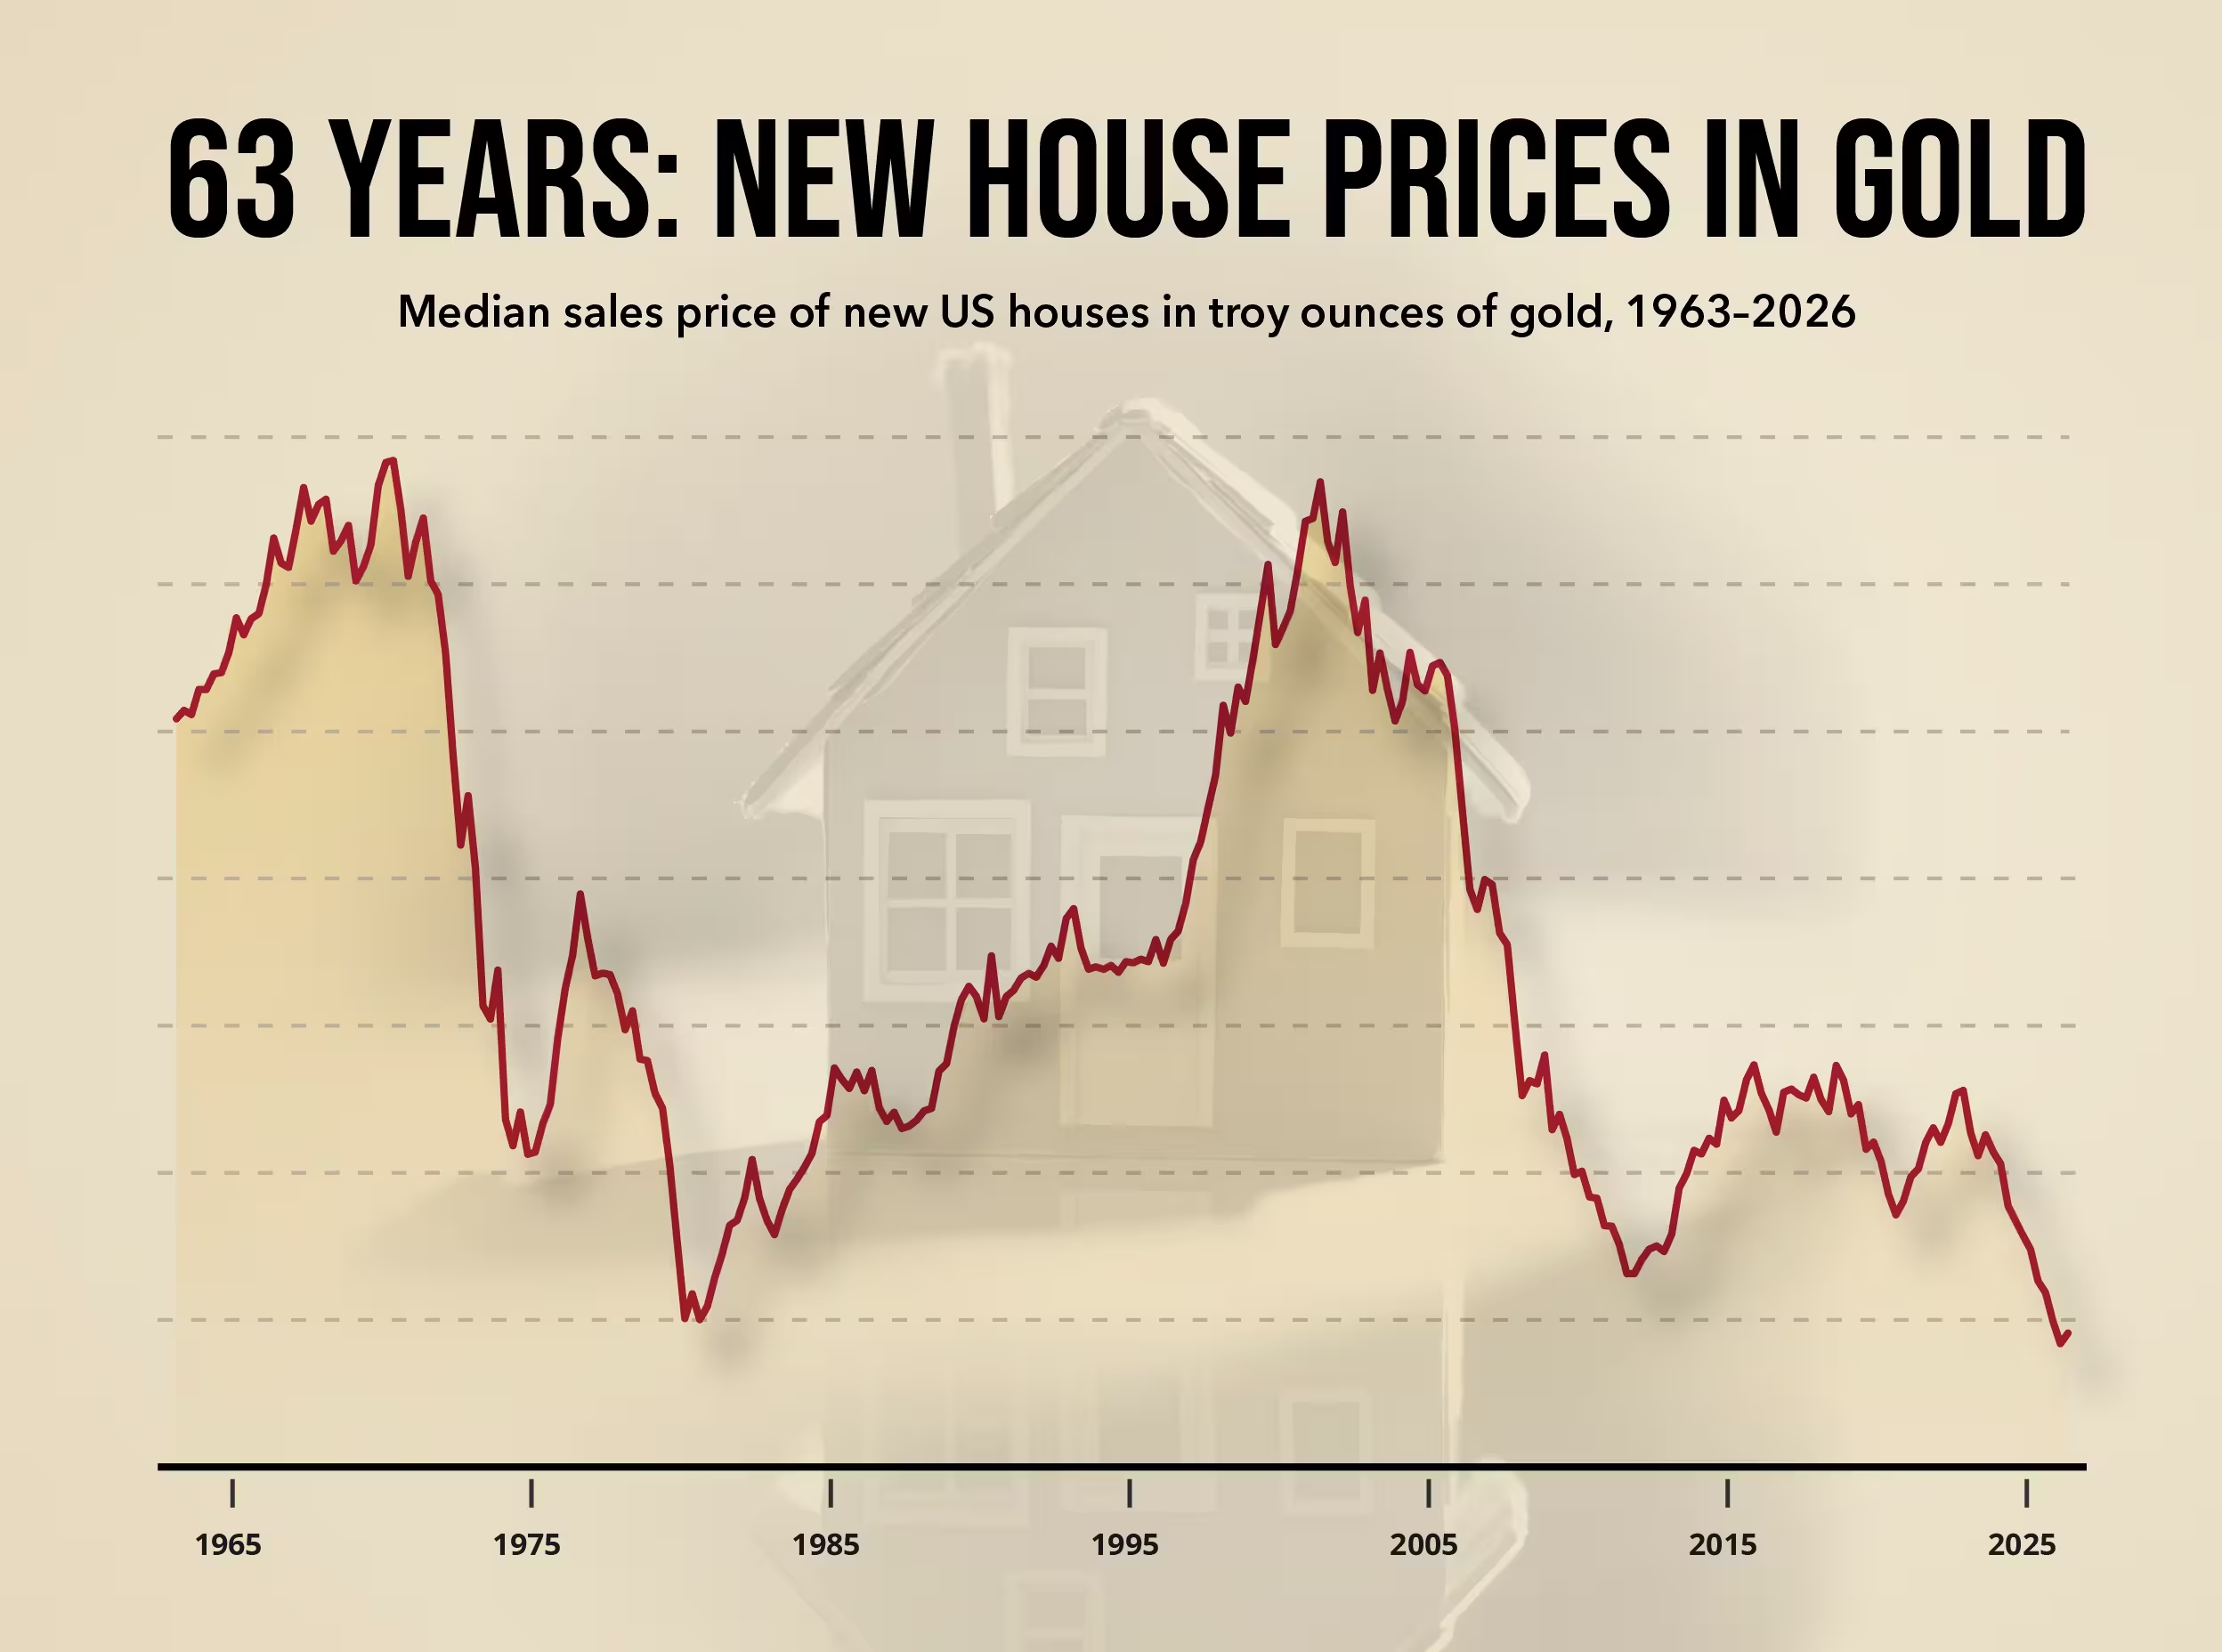
A Median New US Home Now Costs Less Than 100 Ounces of Gold
A Median New US Home Now Costs Less Than 100 Ounces of Gold
The US Census Bureau's July new-home report, released on August 25, put the median price of a newly built house at $393,800. HousingWire noted that was the lowest since July 2021. In dollars, the market has moved within a narrow band: the quarterly median has stayed between $408,500 and $435,400 since 2023.
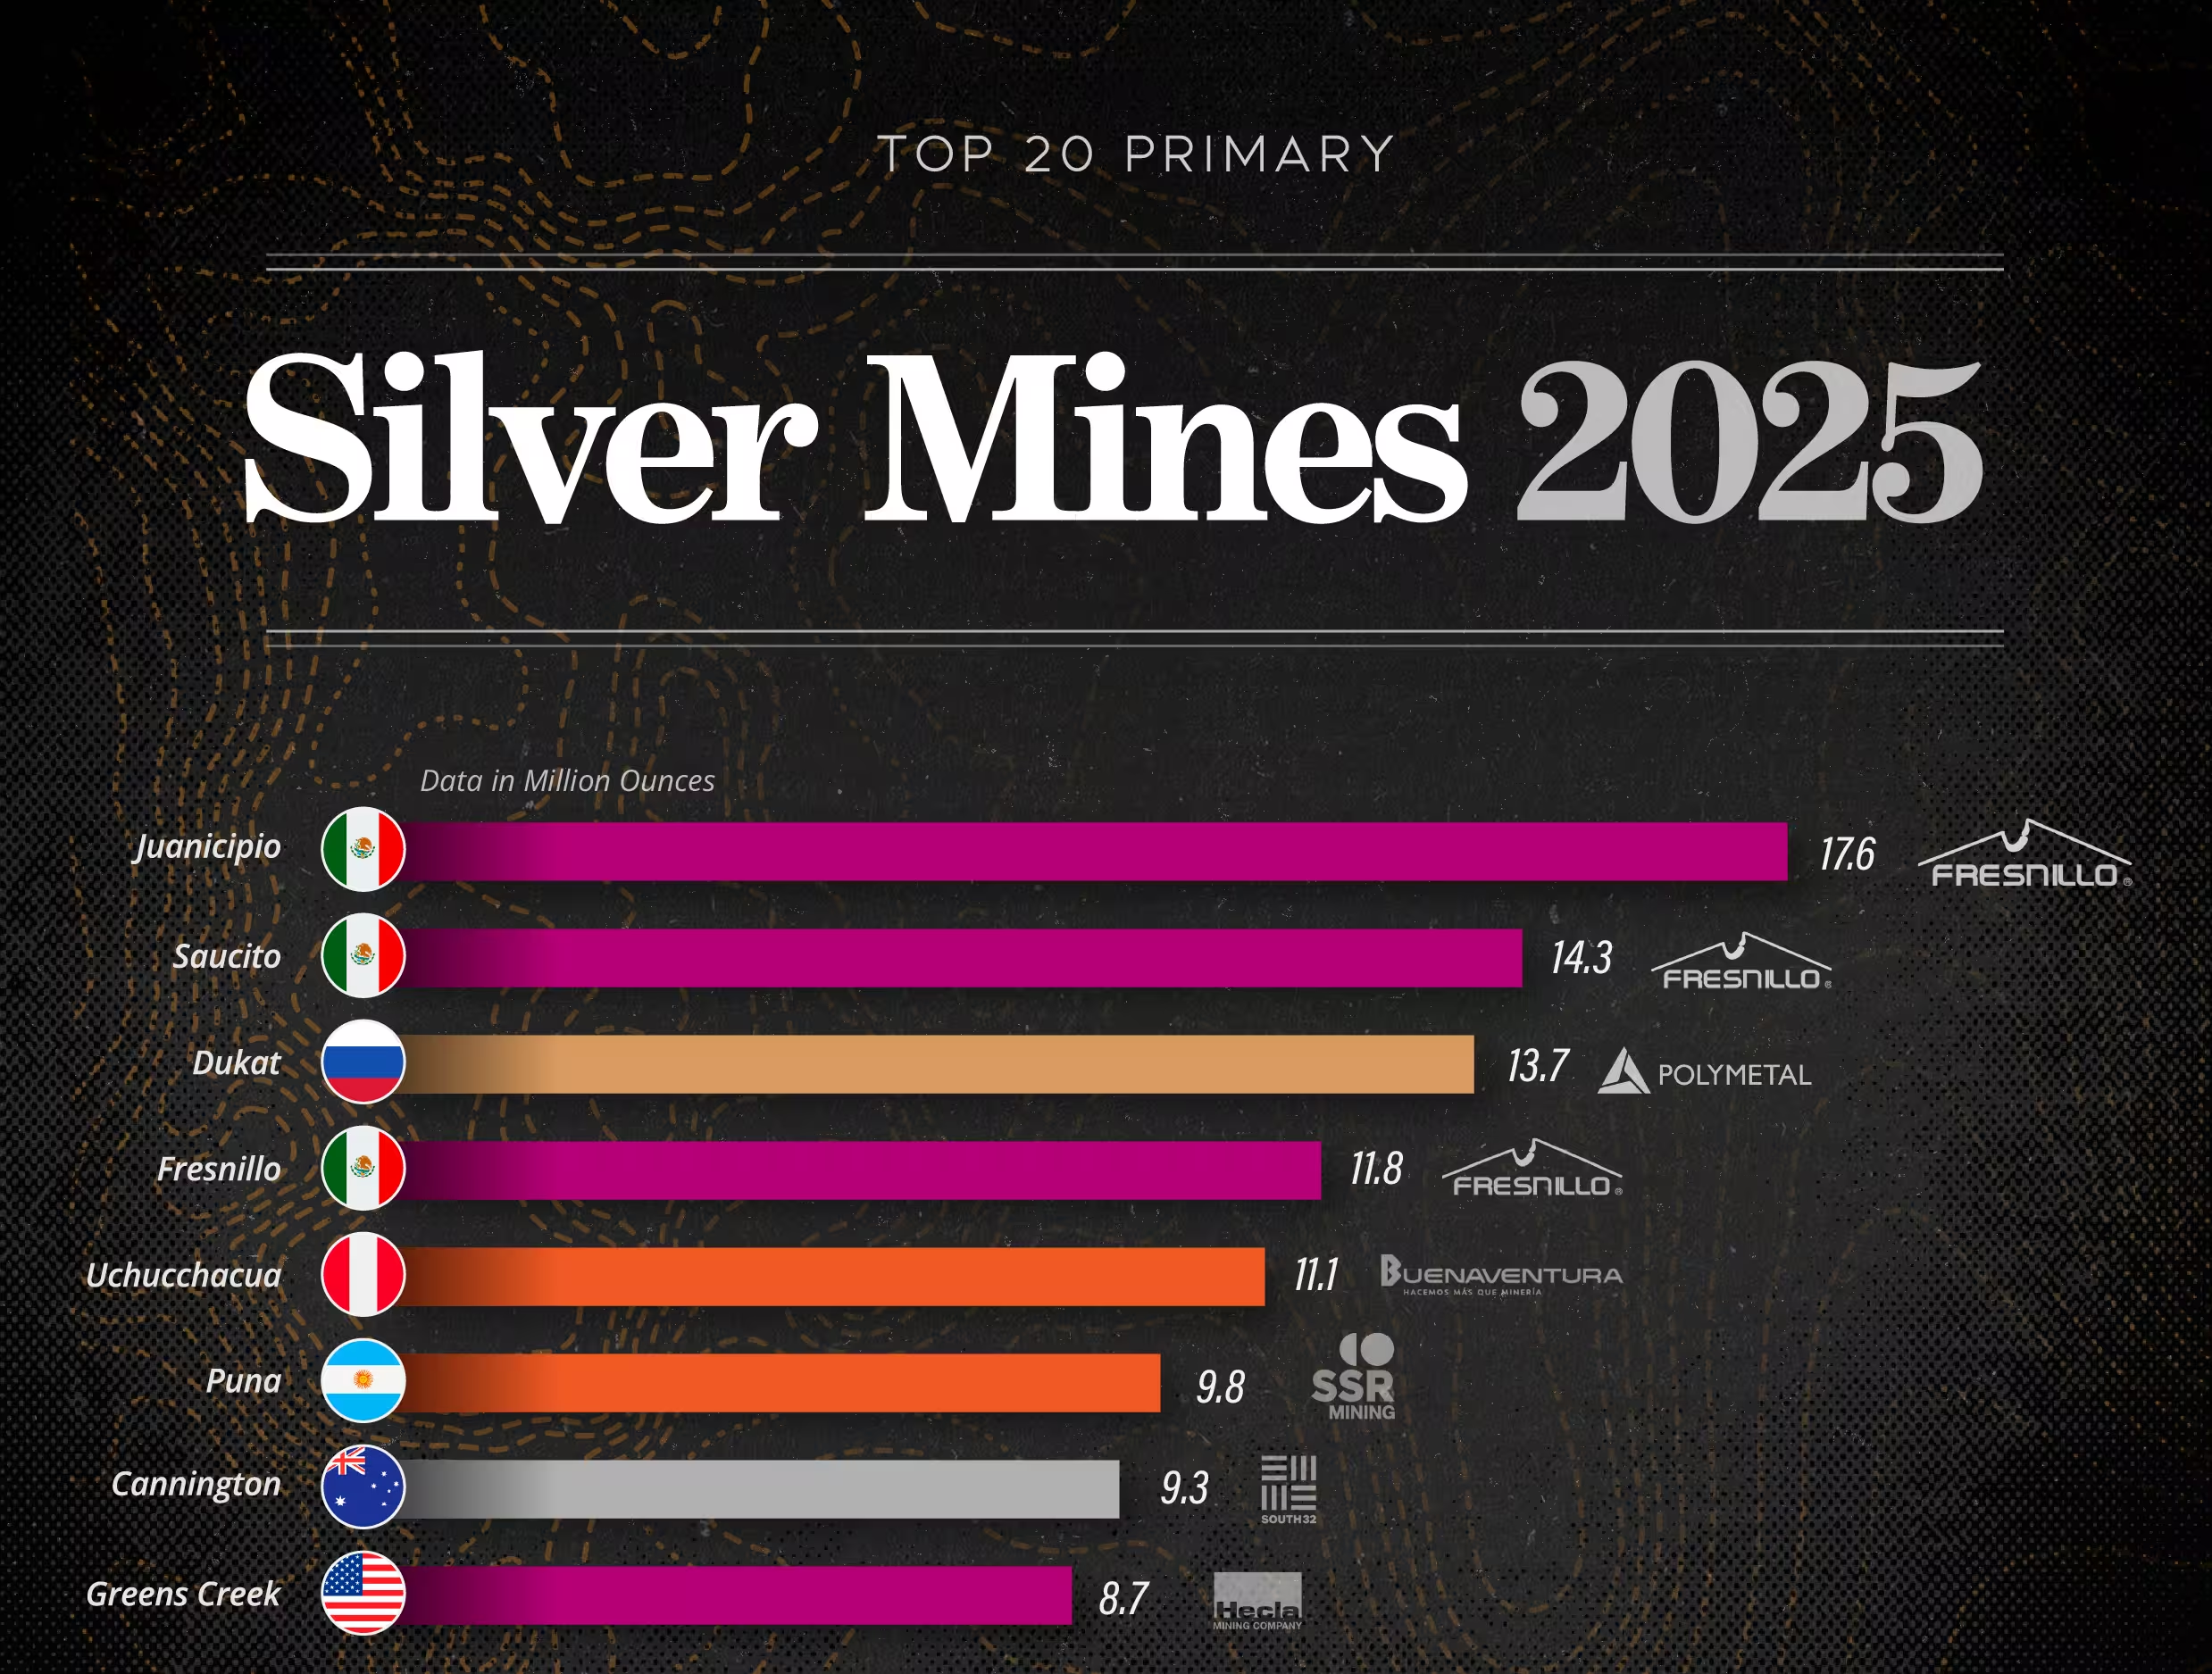
The World's 20 Largest Primary Silver Mines by 2025 Output
The World's 20 Largest Primary Silver Mines by 2025 Output
The single largest source of primary silver is a young mine in the Mexican state of Zacatecas. Juanicipio put out 17.6 million ounces in 2025, more than any other mine that earns its keep from silver itself rather than pulling it out as a byproduct of lead, zinc and gold. Fresnillo operates it and owns 56%; the other 44% changed hands in September 2025, when Pan American Silver completed a US$2.1 billion takeover of MAG Silver.
Gold's Record Run Has Set Off a Wave of Mining Mergers
Gold's Record Run Has Set Off a Wave of Mining Mergers
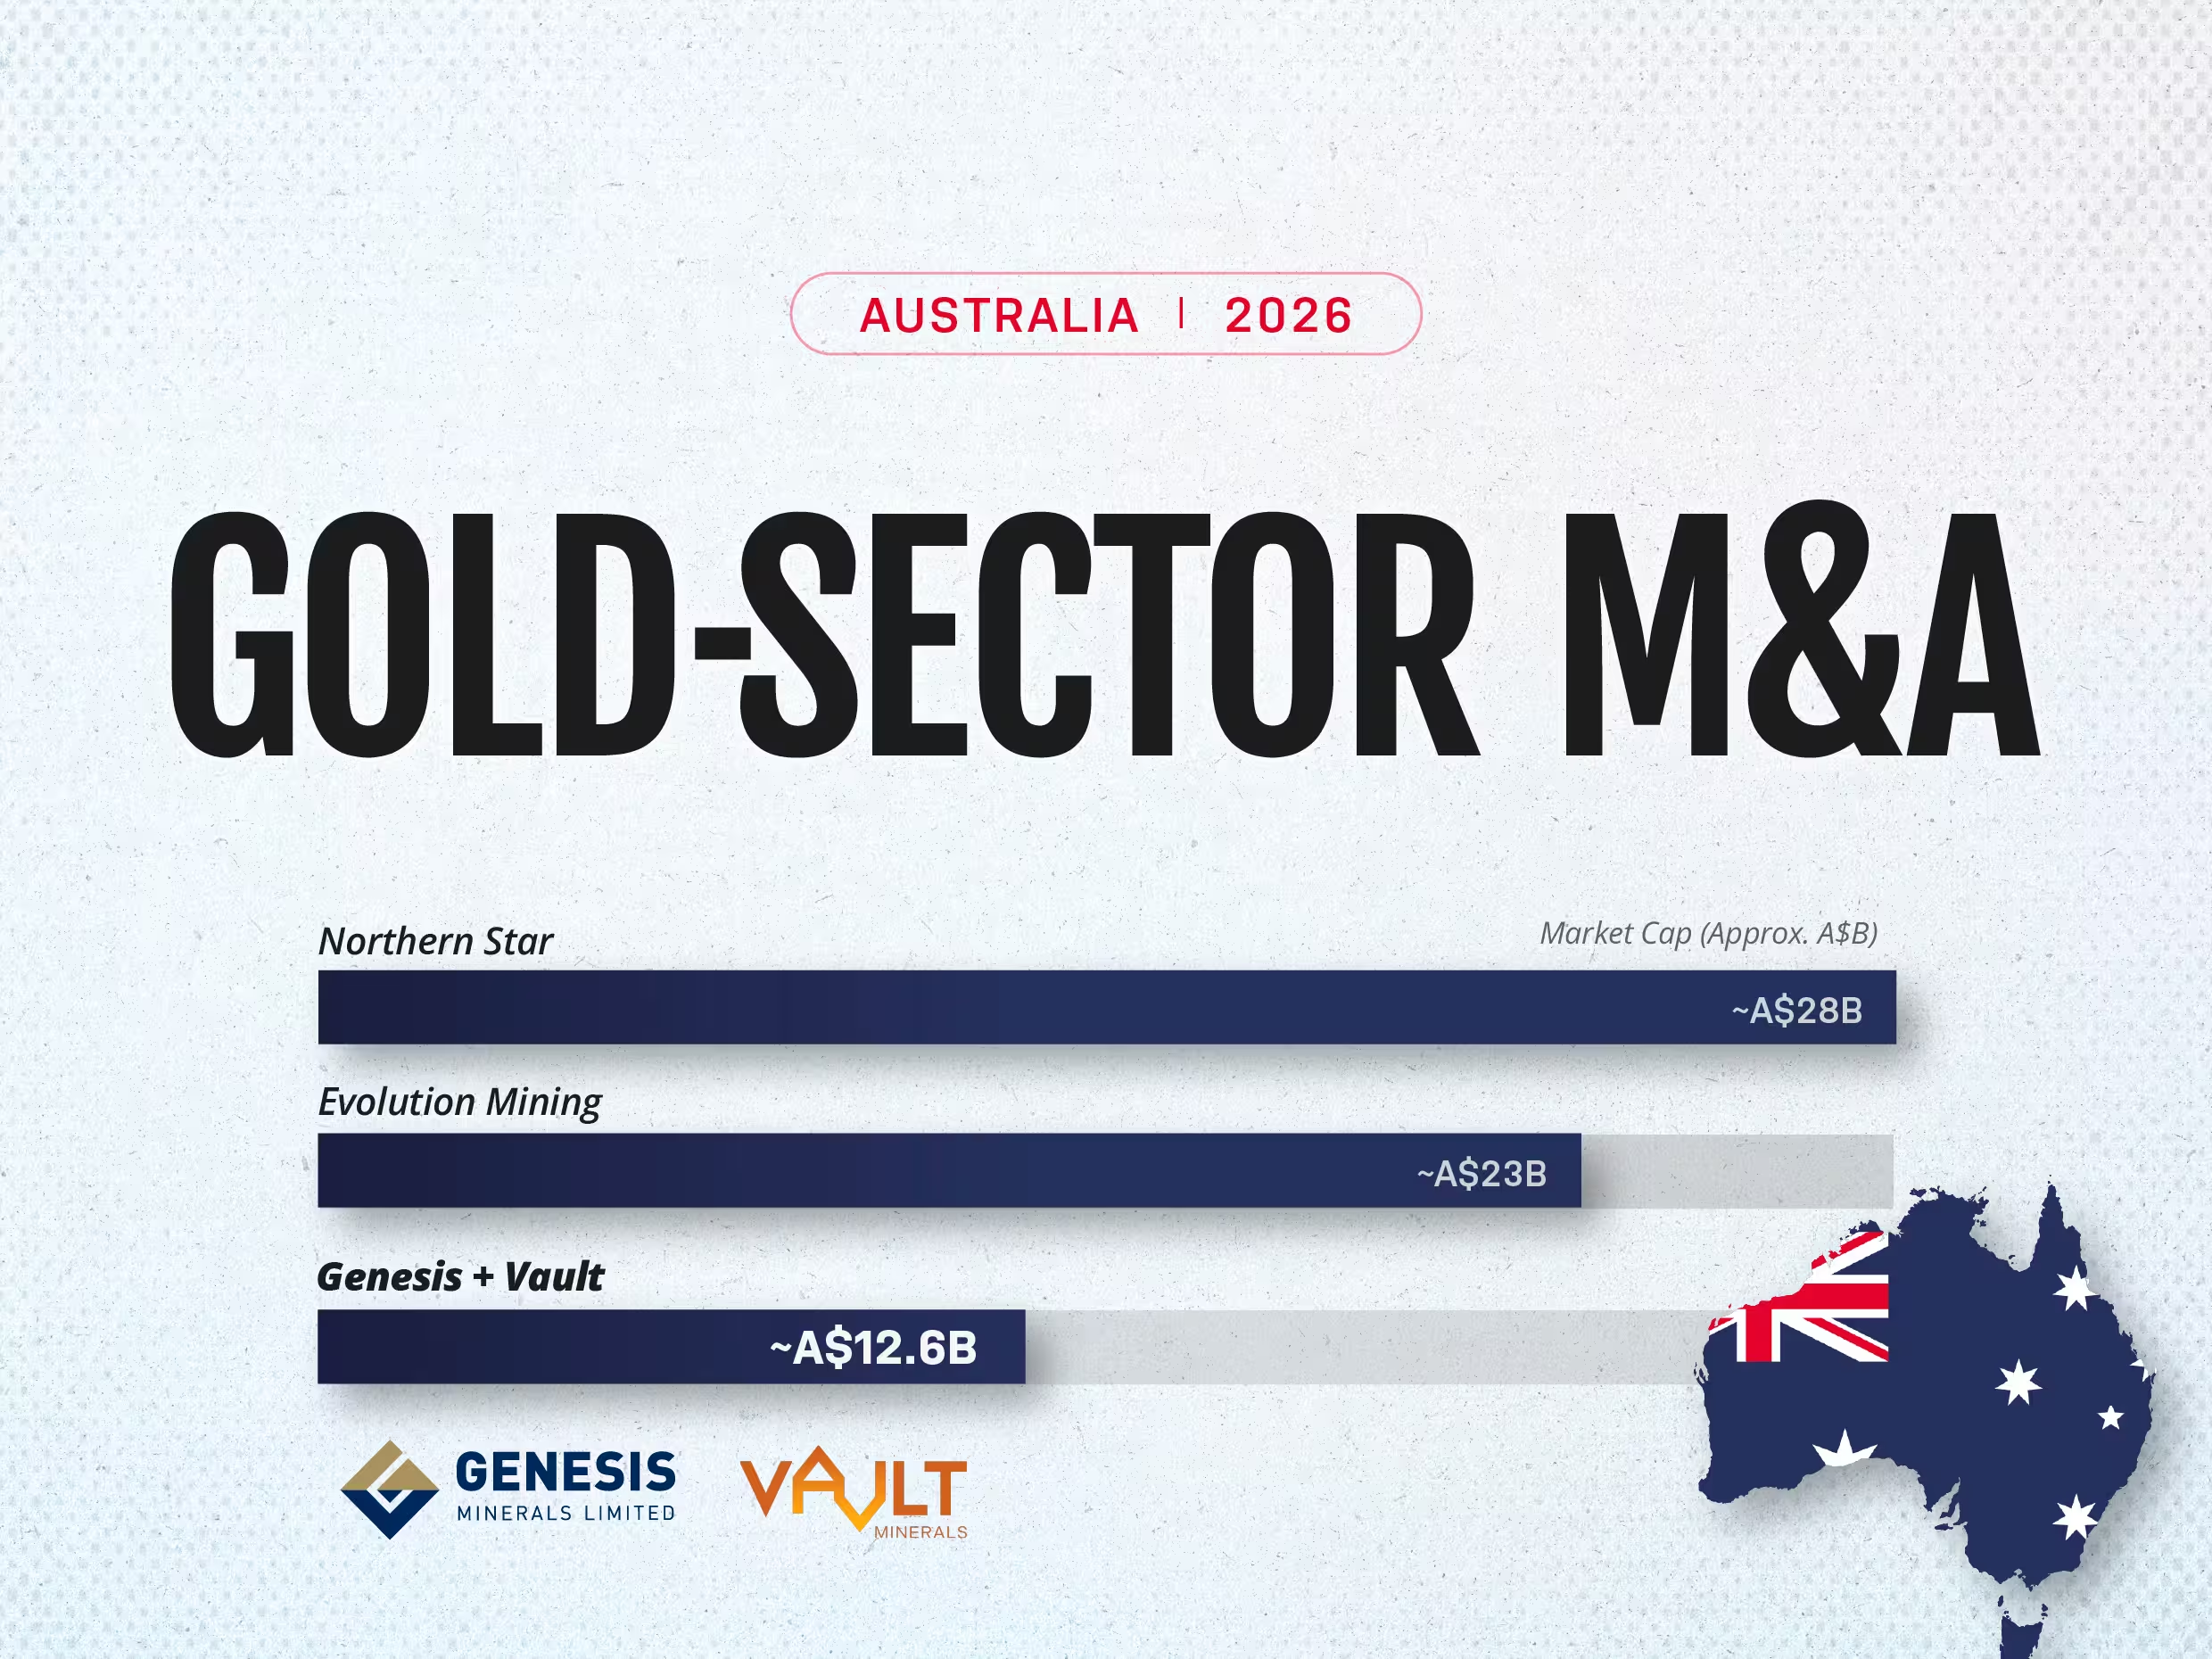
Gold hit an all-time high of about US$5,595 an ounce in January 2026 before settling near US$4,000, still far above the levels of a few years ago. That combination, record prices followed by a stable, still-profitable pullback, has done something a straight rally rarely does: it has opened a merger window.
Three Ancient Belts Carry Ghana's Gold, and Investment Keeps Flowing to Them
Three Ancient Belts Carry Ghana's Gold, and Investment Keeps Flowing to Them
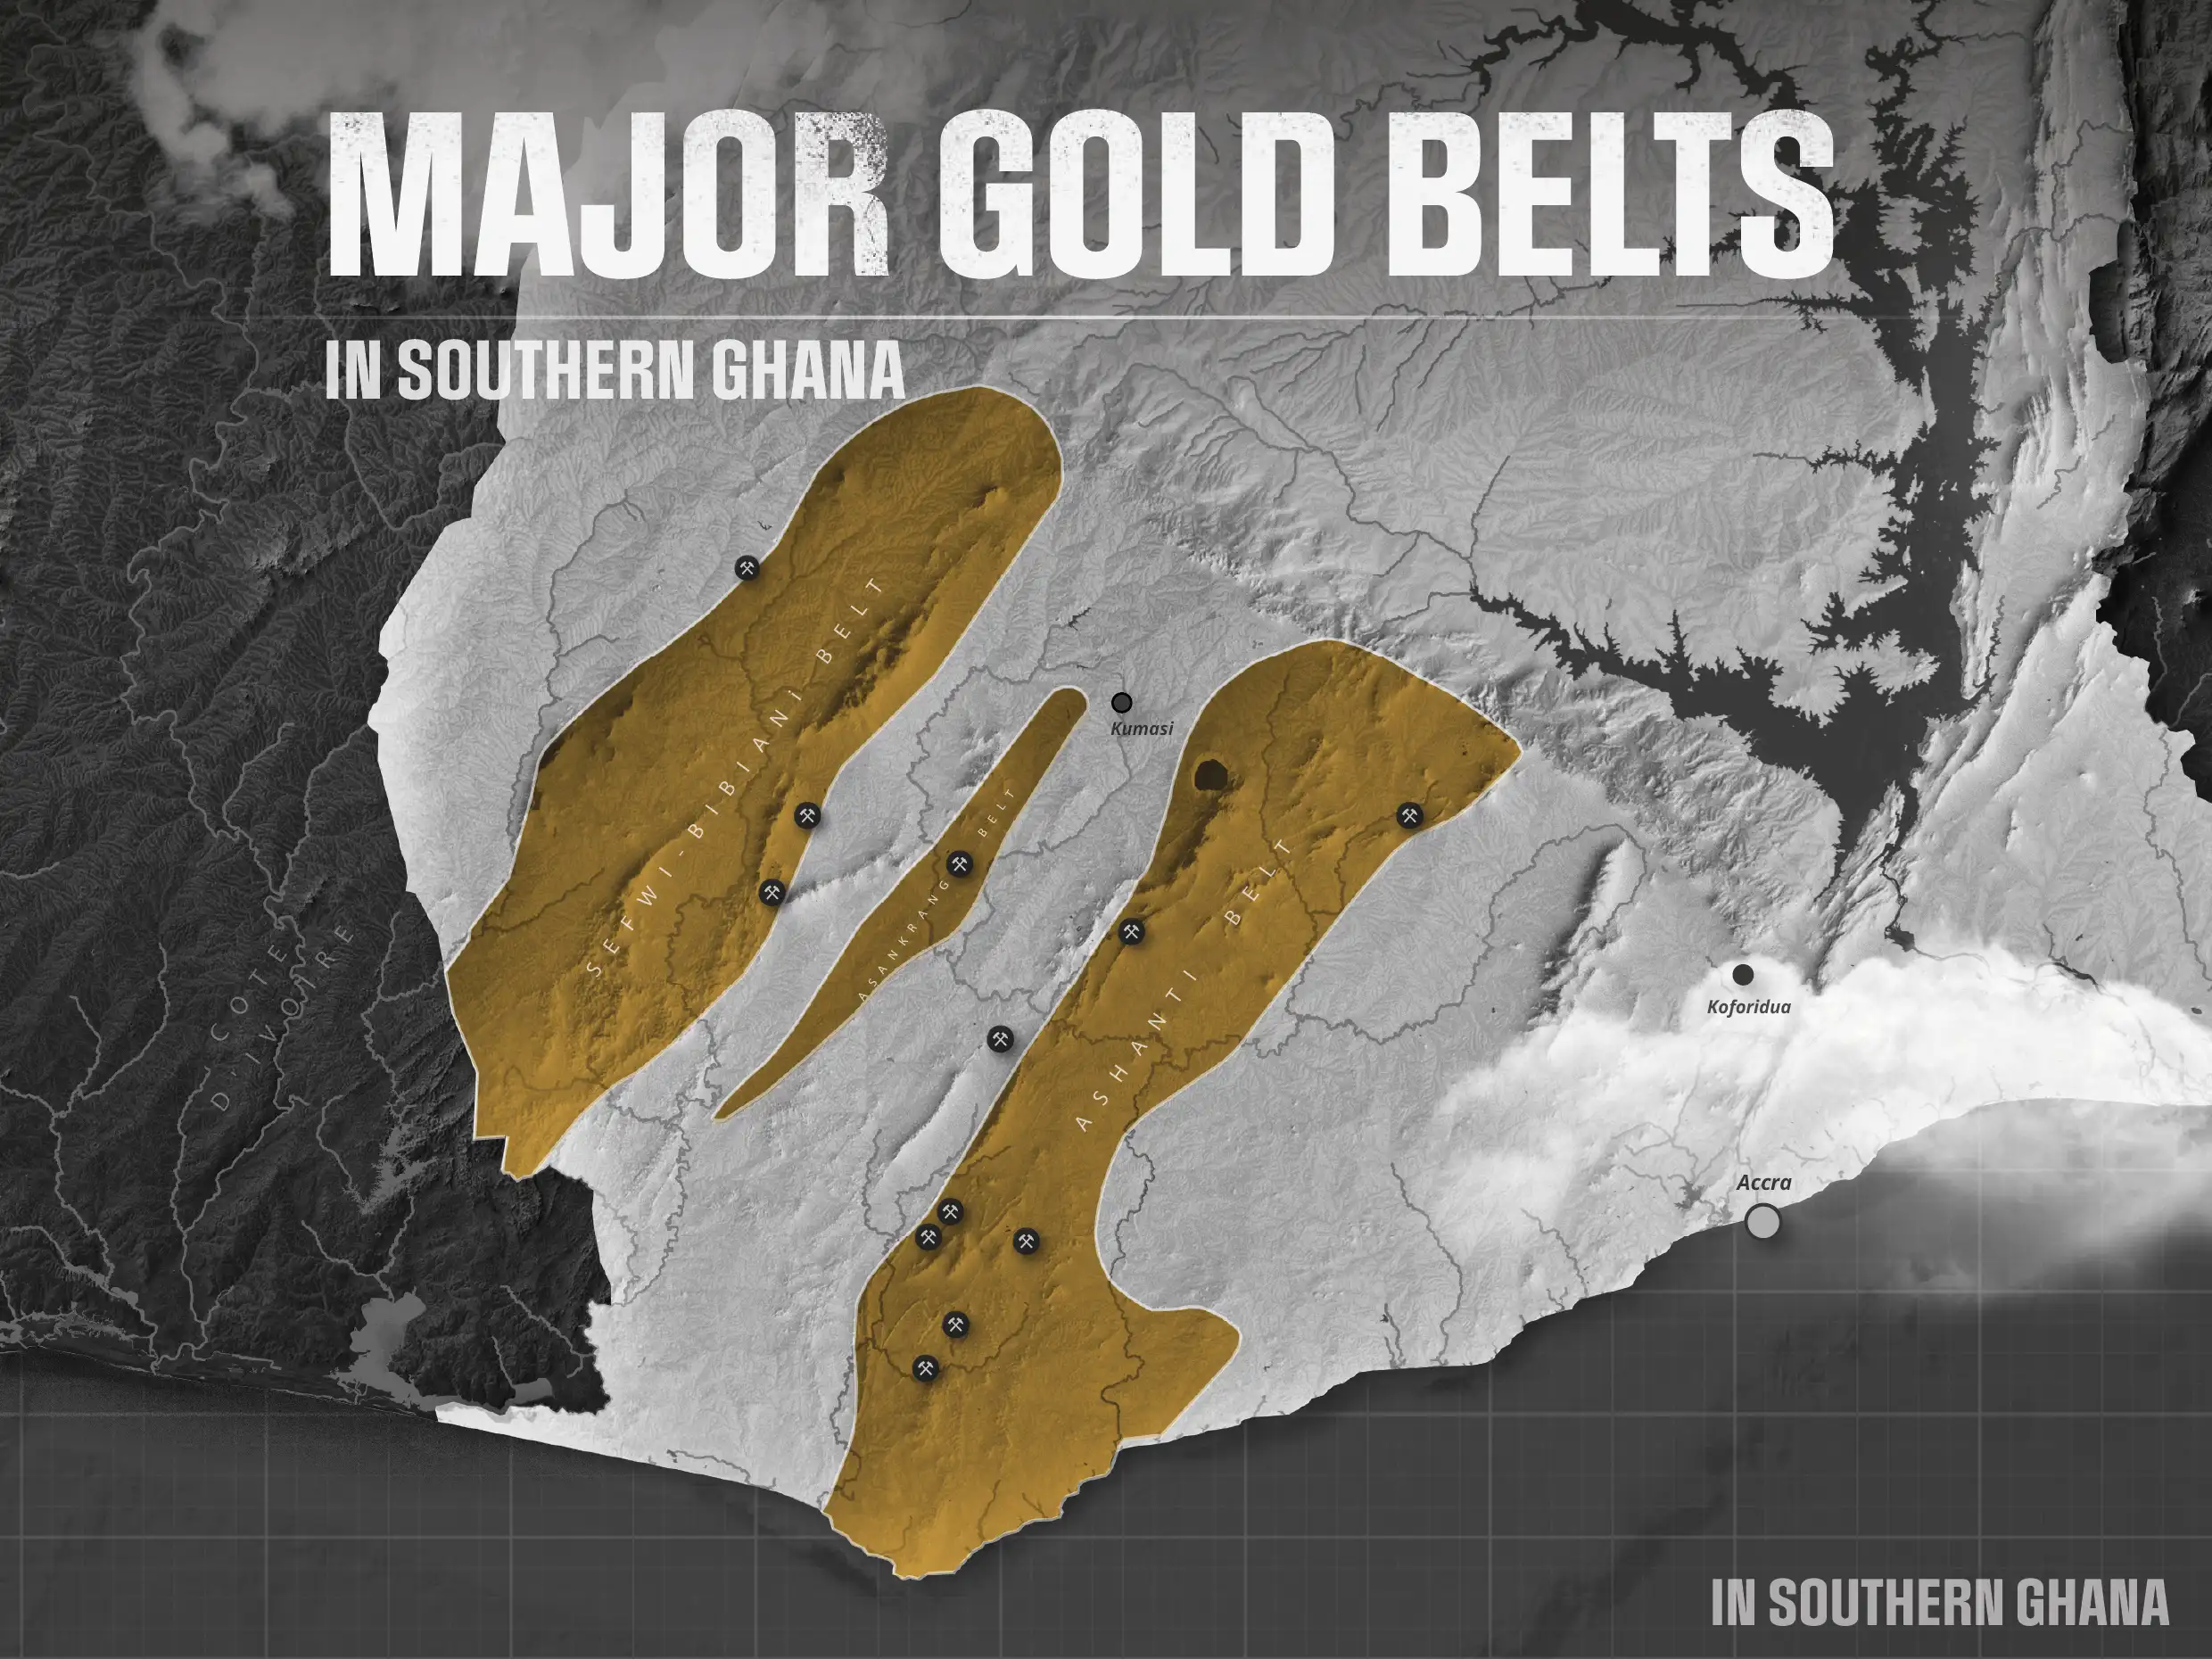
In March 2026, one of Ghana's own mining companies said it would invest about $1.2 billion in its operations at the Tarkwa and Damang gold mines. Both sit on the Ashanti belt, one of three narrow bands of ancient rock that carry almost all of Ghana's gold.