Precious Metals
September 1, 2025
3 min
Precious Metals


The global silver market is no longer defined by its historical roles in coinage or photography. A fundamental transformation has occurred, cementing a new foundation for demand built on technology and green energy. This isn't just a shift; it's a structural realignment where industrial applications have become the market's primary driver.
The Silver Survey 2025 provides the data to chart this industrialization. The accompanying infographic visualizes how silver's most critical sectors are forecast to evolve by 2025, using 2016 as a baseline for comparison.
The New Industrial Bedrock
The forecast for 2025 shows that silver's future is now inextricably linked to its non-substitutable industrial properties.
- Electrical & Electronics remains the single largest consumer, with forecast demand of 270 million ounces (Moz). This demand forms the new bedrock for the market, reflecting silver's essential role in everything from automotive electronics to consumer devices.
- Photovoltaics is the most powerful growth catalyst. Demand from the solar sector is projected to hit 196 Moz, a +140% increase from 2016. This explosive growth positions silver as a critical bottleneck and beneficiary of the global energy transition.

- Other Industrial applications provide further proof of silver's diverse utility. This category, forecast to grow by a robust +19.5%. This steady expansion highlights silver's versatility and its deepening integration into high-value manufacturing and technology worldwide.
Shifting Tides in Traditional Sectors
While the industrial core strengthens, traditional sectors are settling into new, smaller roles.
- Photography, once a pillar of silver demand, is forecast to fall a further 30.2% to just 24 Moz, marking the final chapter of its transition to digital.
- Coins and Bars: After years of heightened activity, physical investment in Coins and Bars is forecast to normalize at 204 Moz. While still a significant market, it is no longer the primary growth story it once was.
Conclusion: A Market Redefined
The 2025 forecast paints a clear picture of a market that has been fundamentally redefined. The narrative is no longer about a battle between old and new uses, but about the establishment of a powerful new industrial base. This "industrialization of silver" provides a strong, resilient foundation for demand, driven by the unstoppable trends of electrification, connectivity, and green energy. Understanding this structural shift is the key to understanding the modern silver market.
Sponsored by:
Outcrop Silver is a leading explorer and developer focused on advancing its flagship Santa Ana high-grade silver project in Colombia. Leveraging a disciplined and seasoned team of professionals with decades of experience in the region. Outcrop Silver is dedicated to expanding current mineral resources through strategic exploration initiatives.
At the core of our operations is a commitment to responsible mining practices and community engagement, underscoring our approach to sustainable development. Our expertise in navigating complex geological and market conditions enables us to consistently identify and capitalize on opportunities to enhance shareholder value.
With a deep understanding of the Colombian mining landscape and a track record of successful exploration, Outcrop Silver is poised to transform the Santa Ana project into a significant silver producer, contributing positively to the local economy and setting new standards in the mining industry.
Learn more about Outcrop Silver at https://outcropsilver.com/
Disclaimer: This article is for informational and illustrative purposes only, based on data sourced from the Silver Survey 2025.


Explore More
View All

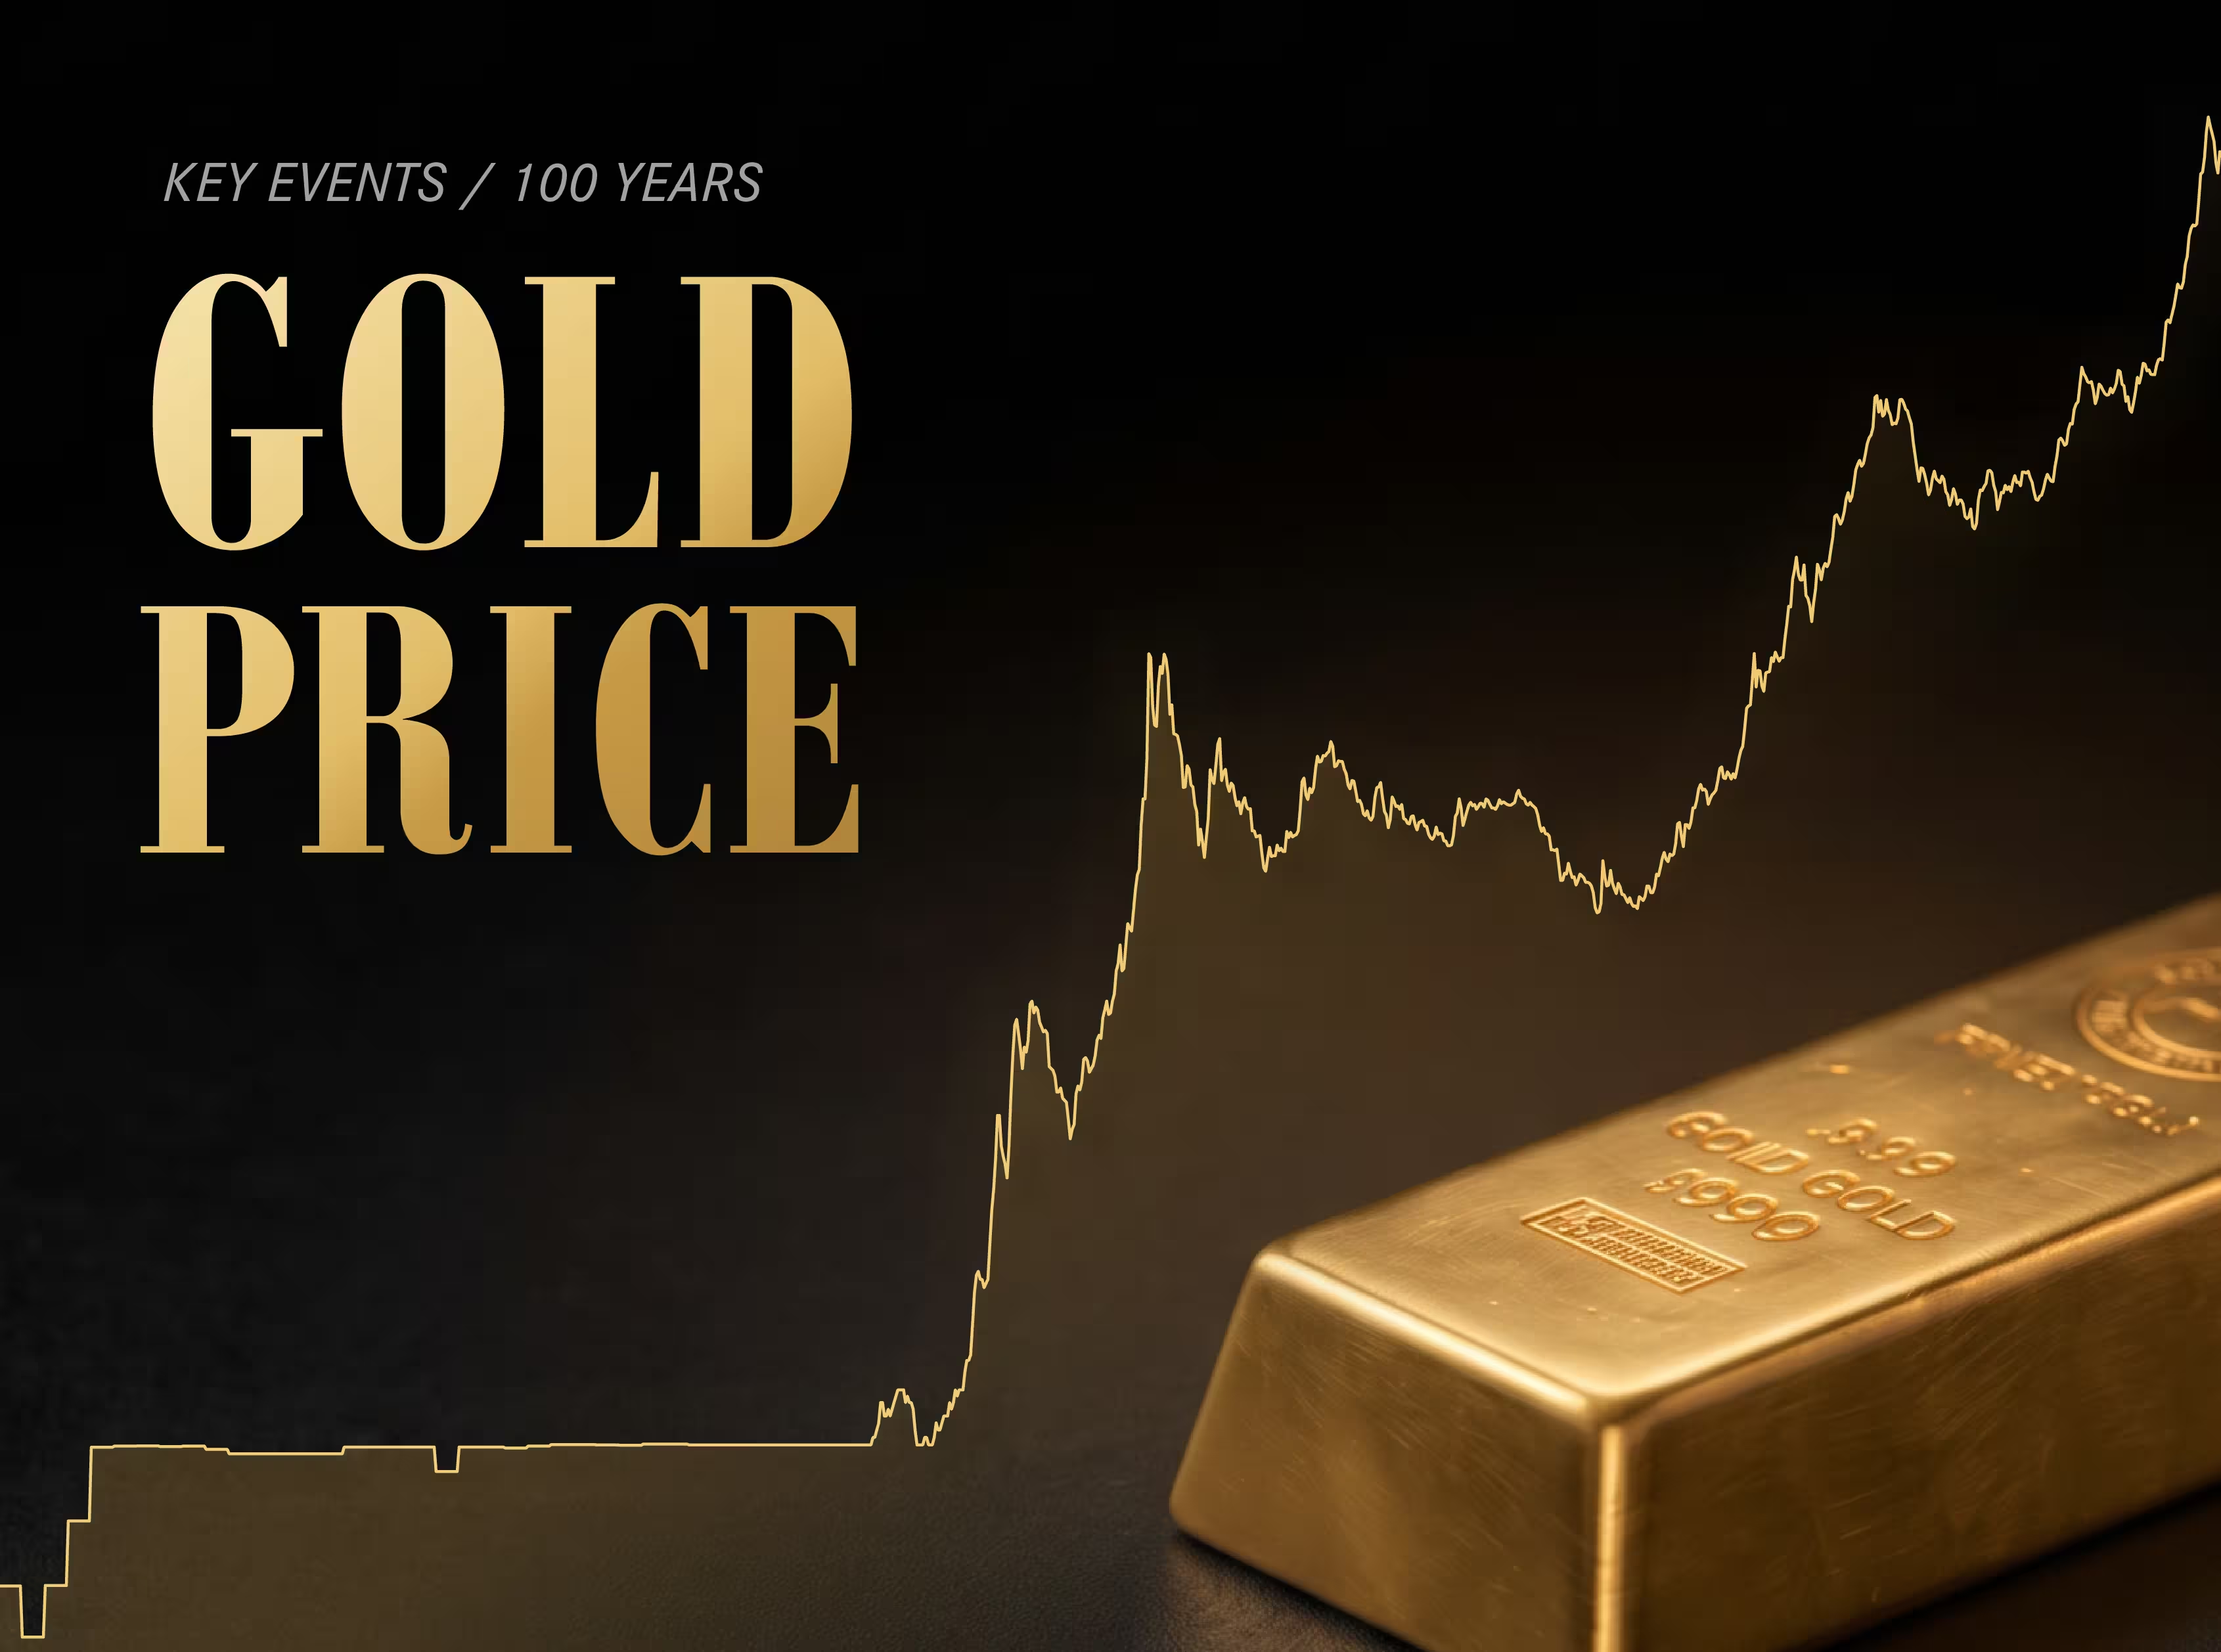
Seven Events That Shaped a Century of Gold Prices
Seven Events That Shaped a Century of Gold Prices
In 1934, the US government set the price of gold at $35 an ounce. In September 2026, the market price averaged $4,319. Measured in today's money, gold has done more than keep up with rising prices. An ounce is now worth almost five times what it was when the price was set in 1934, and more than at the famous 1980 peak. For the companies that mine it, that has meant record margins.

The World's 20 Largest Primary Silver Mines by 2025 Output
The World's 20 Largest Primary Silver Mines by 2025 Output
The largest silver producer among the world's primary silver mines in 2025 sat not in Mexico but in southwestern Bolivia. San Cristóbal, a large open-pit silver-zinc-lead mine run by Minera San Cristóbal, produced 17.6 million ounces of silver, narrowly ahead of Mexico's Juanicipio at the same rounded figure, in new Metals Focus data on the 20 largest primary silver mines. These are the operations where silver is a defining product rather than an incidental byproduct of lead, zinc and gold. The list runs from centuries-old mines in Mexico's silver belt to remote sites in the Andes, the Australian outback and the Alaskan wilderness. Eight of the 20 sit in Mexico, together about 44% of the total, while the rest are spread across the Americas, Asia, Africa and Australia.
Central Banks Have Been Net Gold Buyers Since 2010, After Two Decades of Net Selling
Central Banks Have Been Net Gold Buyers Since 2010, After Two Decades of Net Selling
Central banks bought more gold between April and June 2026 than in any second quarter on record, according to a World Gold Council report published on July 30. That keeps them net buyers this year, as they have been every year since 2010. Underneath, the picture is changing. Russia and Türkiye, both big buyers in the past, have been selling.

Gold Mines in West Africa: Two Billion Years in the Making
Gold Mines in West Africa: Two Billion Years in the Making
The nine West African countries with significant reported output produced about 15% of the world's mined gold in 2025, according to Metals Focus and World Gold Council data. Almost every mine on the map above was built in the past 25 years, and four more reached production in the last eighteen months: Lafigué in Côte d'Ivoire in June 2024, Kiaka in Burkina Faso in June 2025, Ahafo North in Ghana in October 2025 and Kiniero in Guinea in December 2025.