Precious Metals
September 19, 2024
3 min
Precious Metals


According to the US Geological Survey, identified economic gold reserves currently stand at just 59,000 MT globally in 2023. The majority of these reserves are concentrated in three key countries that dominate the global gold landscape: Australia, Russia, and South Africa. These nations collectively hold a significant portion of the world’s gold reserves.
- Australia holds some of the largest gold reserves in the ground, with an estimated 12,000 metric tons. These reserves are primarily concentrated in the states of Western Australia and South Australia, where major mines like Boddington and the Super Pit contribute to significant gold production.
- Russia ranks second with 11,100 metric tons of reserves. Its production is largely focused in Siberia, where abundant resources have helped Russia consistently grow its gold stockpiles, even in the face of geopolitical challenges.
- South Africa remains a prominent player in gold reserves, though its production has waned due to the increasing difficulty of mining deeper deposits. Despite this, it still possesses substantial underground reserves.
These vast reserves are critical for the future of gold mining, positioning these nations as key suppliers in meeting the growing global demand for gold. Other significant holders of gold reserves are USA, China, Indonesia, Brazil, Peru and Canada:
The United States holds approximately 3,000 metric tons of gold reserves in the ground. The U.S. is a significant player in global gold mining, with major deposits located in Nevada, which contributes the largest share of domestic production, followed by Alaska. Nevada's Carlin Trend remains one of the world’s most productive gold mining regions, hosting key mines like Goldstrike and Cortez.
China holds one of the largest in-ground gold reserves globally, estimated at 3,000 metric tons. China also remains the world's largest gold producer, with an output of around 370 metric tons for the year, despite the declining ore grades in some areas. Major mining companies like China Gold International Resources, Shandong Gold, and Zijin Mining are key players in developing and expanding these reserves.
Indonesia holds substantial gold reserves, largely due to the massive Grasberg mine in Papua, one of the world’s largest gold deposits. Despite shifting to underground operations, Grasberg remains crucial to the nation's gold production. Additionally, exploration projects like the Onto deposit in West Nusa Tenggara show great potential.
Brazil's hold approximately 2,400 tonnes in the ground, their largest gold deposits are mainly located in Minas Gerais. The Paracatu Mine (Kinross Gold) is the biggest, producing over 549,000 ounces annually. Other key sites include Vale’s Salobo Mine (380,000 ounces), alongside the Cuiabá, Jacobina, and Aurizona mines, contributing over 1.4 million ounces in total each year.
Peru's total gold reserves were estimated at around 2,300 tonnes, reflecting strong exploration activities and new discoveries. Major mining companies like Barrick Gold and Newmont are actively exploring and expanding their operations in the region. Barrick, for instance, has been replenishing its reserves and working on several projects, including the Tres Marias project in the Puno district
Canada holds an estimated 2,300 tonnes of gold reserves in the ground. Their largest gold deposits include the Detour Lake and Canadian Malartic mines, producing over 600,000 ounces each in 2023. Other key sites include the Meadowbank and Meliadine complexes in Nunavut.
Source: U.S. Geological Survey, Mineral Commodity Summaries, January 2024
The information presented here may contain inaccuracies and is subject to rounding. We do not guarantee that all information is complete or correct. We accept no responsibility for any errors, omissions, or outcomes resulting from the use of this information. This is not investment advice.


Explore More
View All

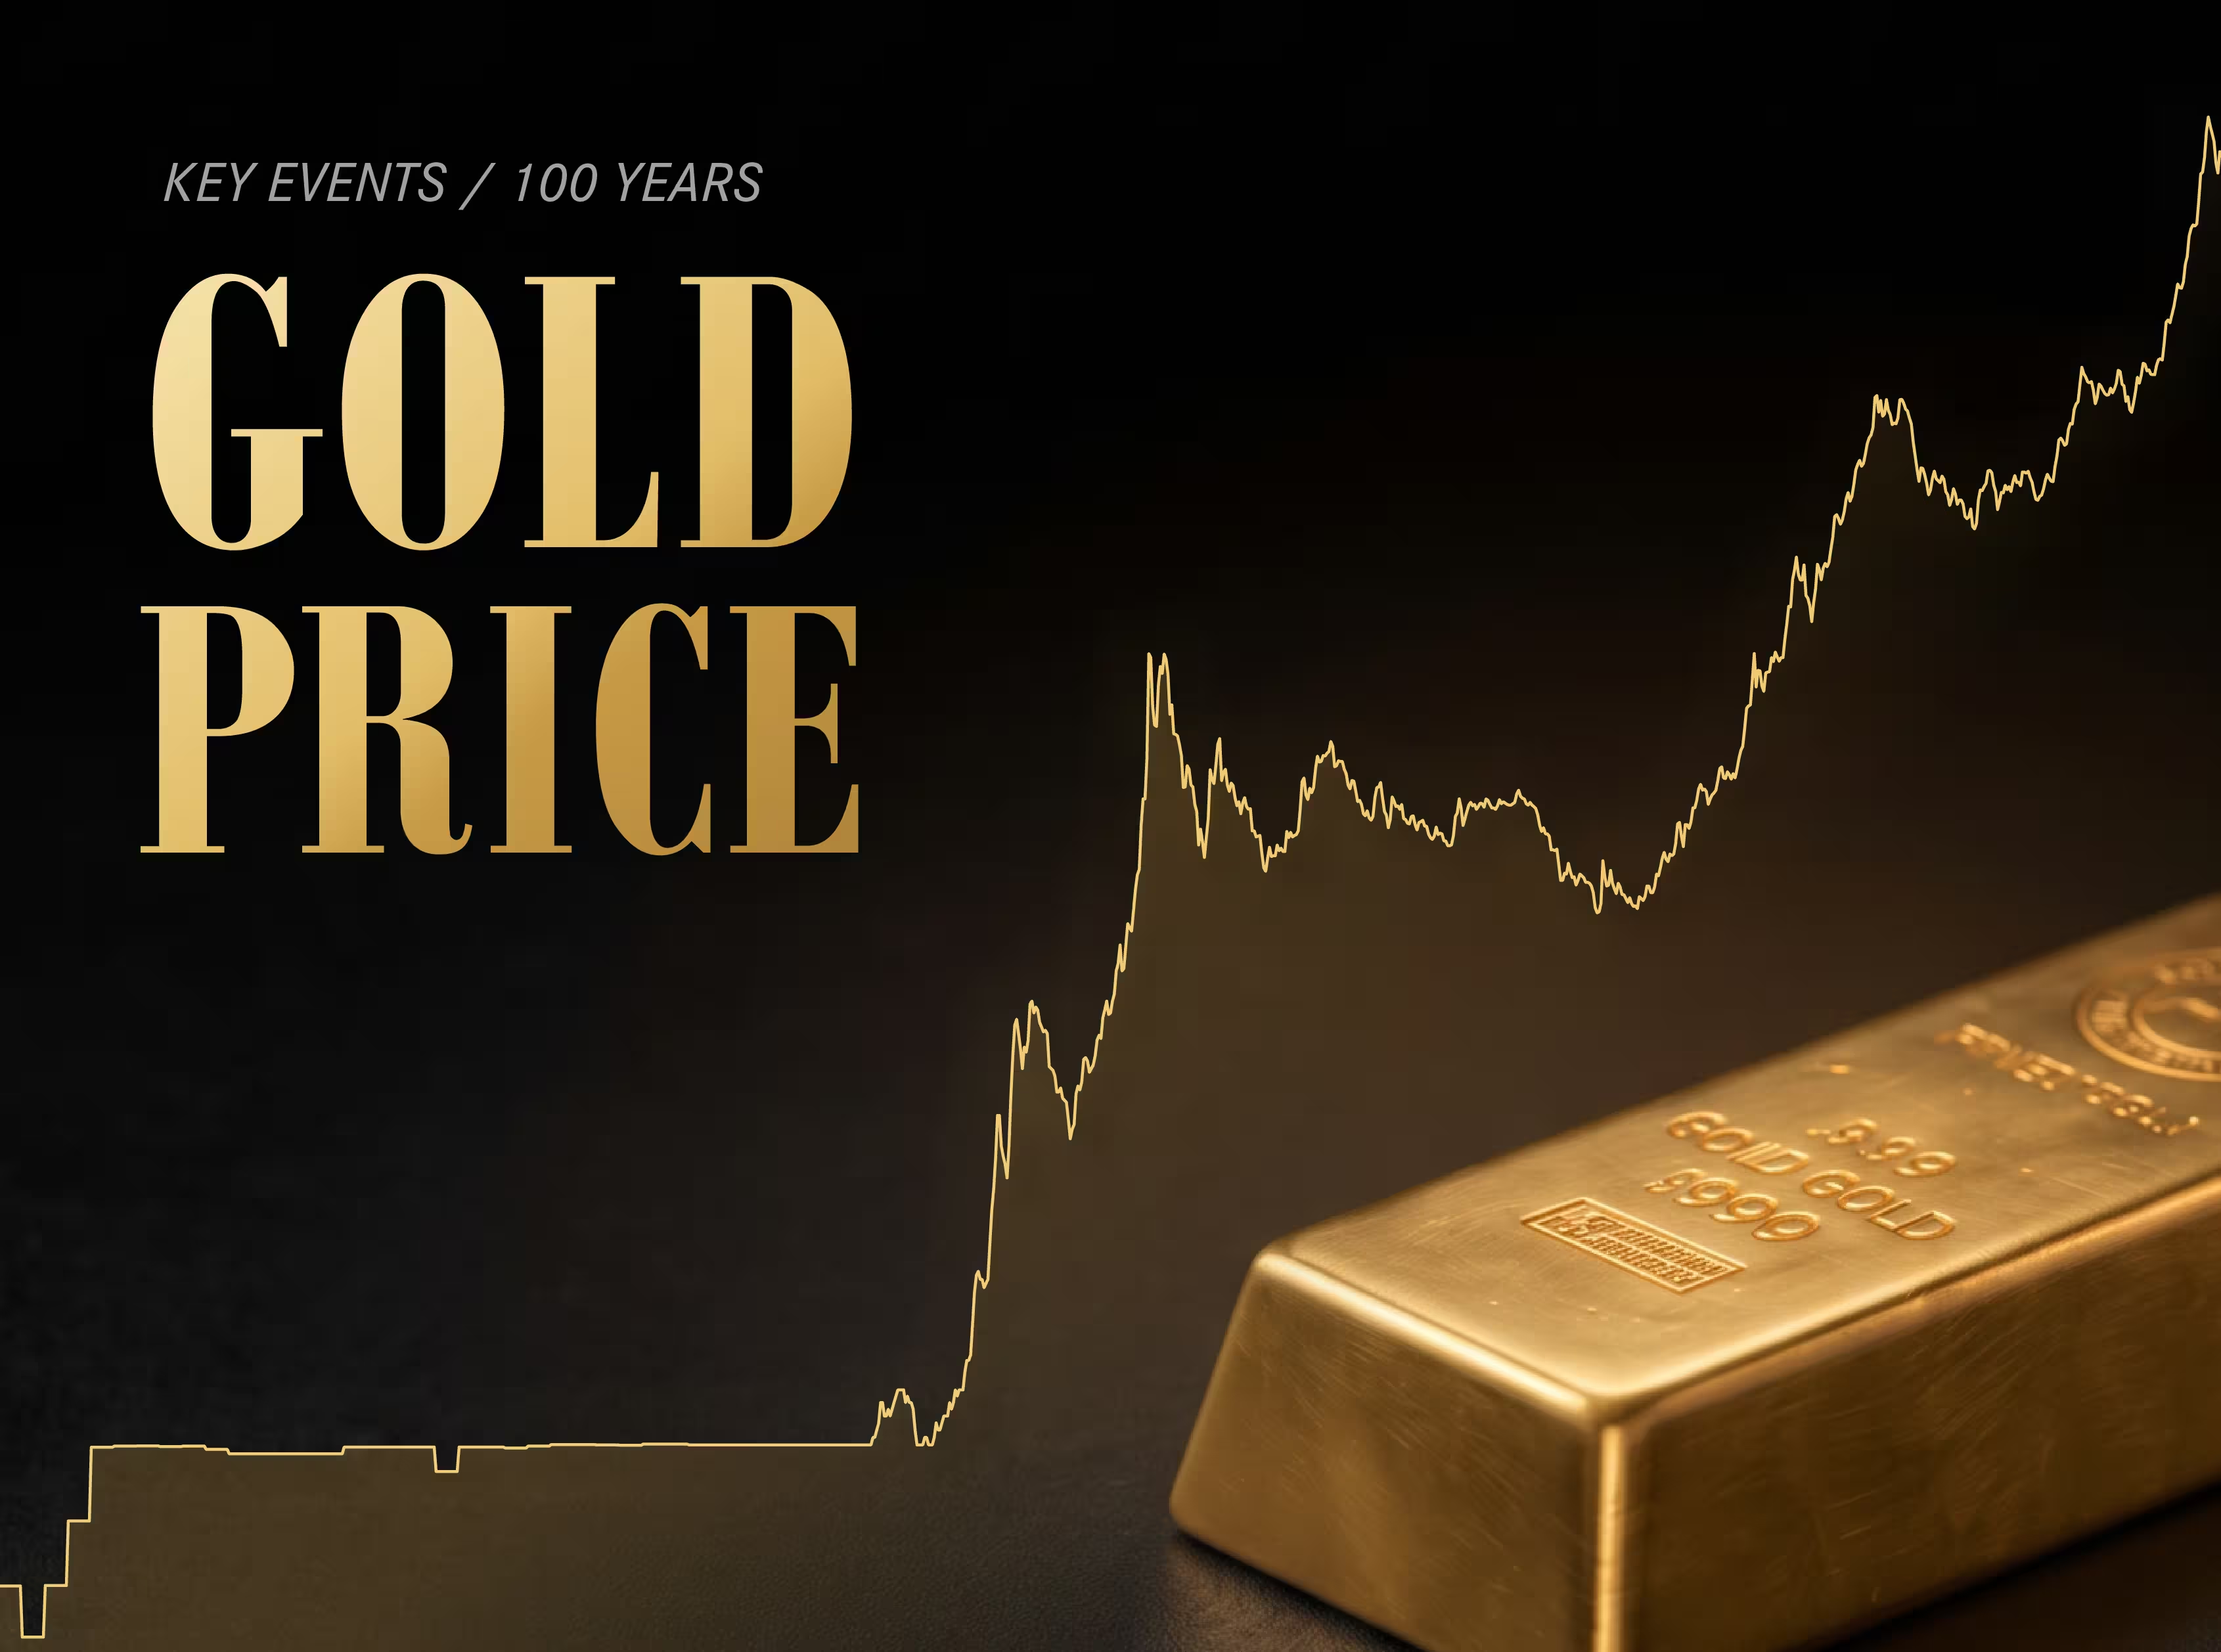
Seven Events That Shaped a Century of Gold Prices
Seven Events That Shaped a Century of Gold Prices
In 1934, the US government set the price of gold at $35 an ounce. In September 2026, the market price averaged $4,319. Measured in today's money, gold has done more than keep up with rising prices. An ounce is now worth almost five times what it was when the price was set in 1934, and more than at the famous 1980 peak. For the companies that mine it, that has meant record margins.

The World's 20 Largest Primary Silver Mines by 2025 Output
The World's 20 Largest Primary Silver Mines by 2025 Output
The largest silver producer among the world's primary silver mines in 2025 sat not in Mexico but in southwestern Bolivia. San Cristóbal, a large open-pit silver-zinc-lead mine run by Minera San Cristóbal, produced 17.6 million ounces of silver, narrowly ahead of Mexico's Juanicipio at the same rounded figure, in new Metals Focus data on the 20 largest primary silver mines. These are the operations where silver is a defining product rather than an incidental byproduct of lead, zinc and gold. The list runs from centuries-old mines in Mexico's silver belt to remote sites in the Andes, the Australian outback and the Alaskan wilderness. Eight of the 20 sit in Mexico, together about 44% of the total, while the rest are spread across the Americas, Asia, Africa and Australia.
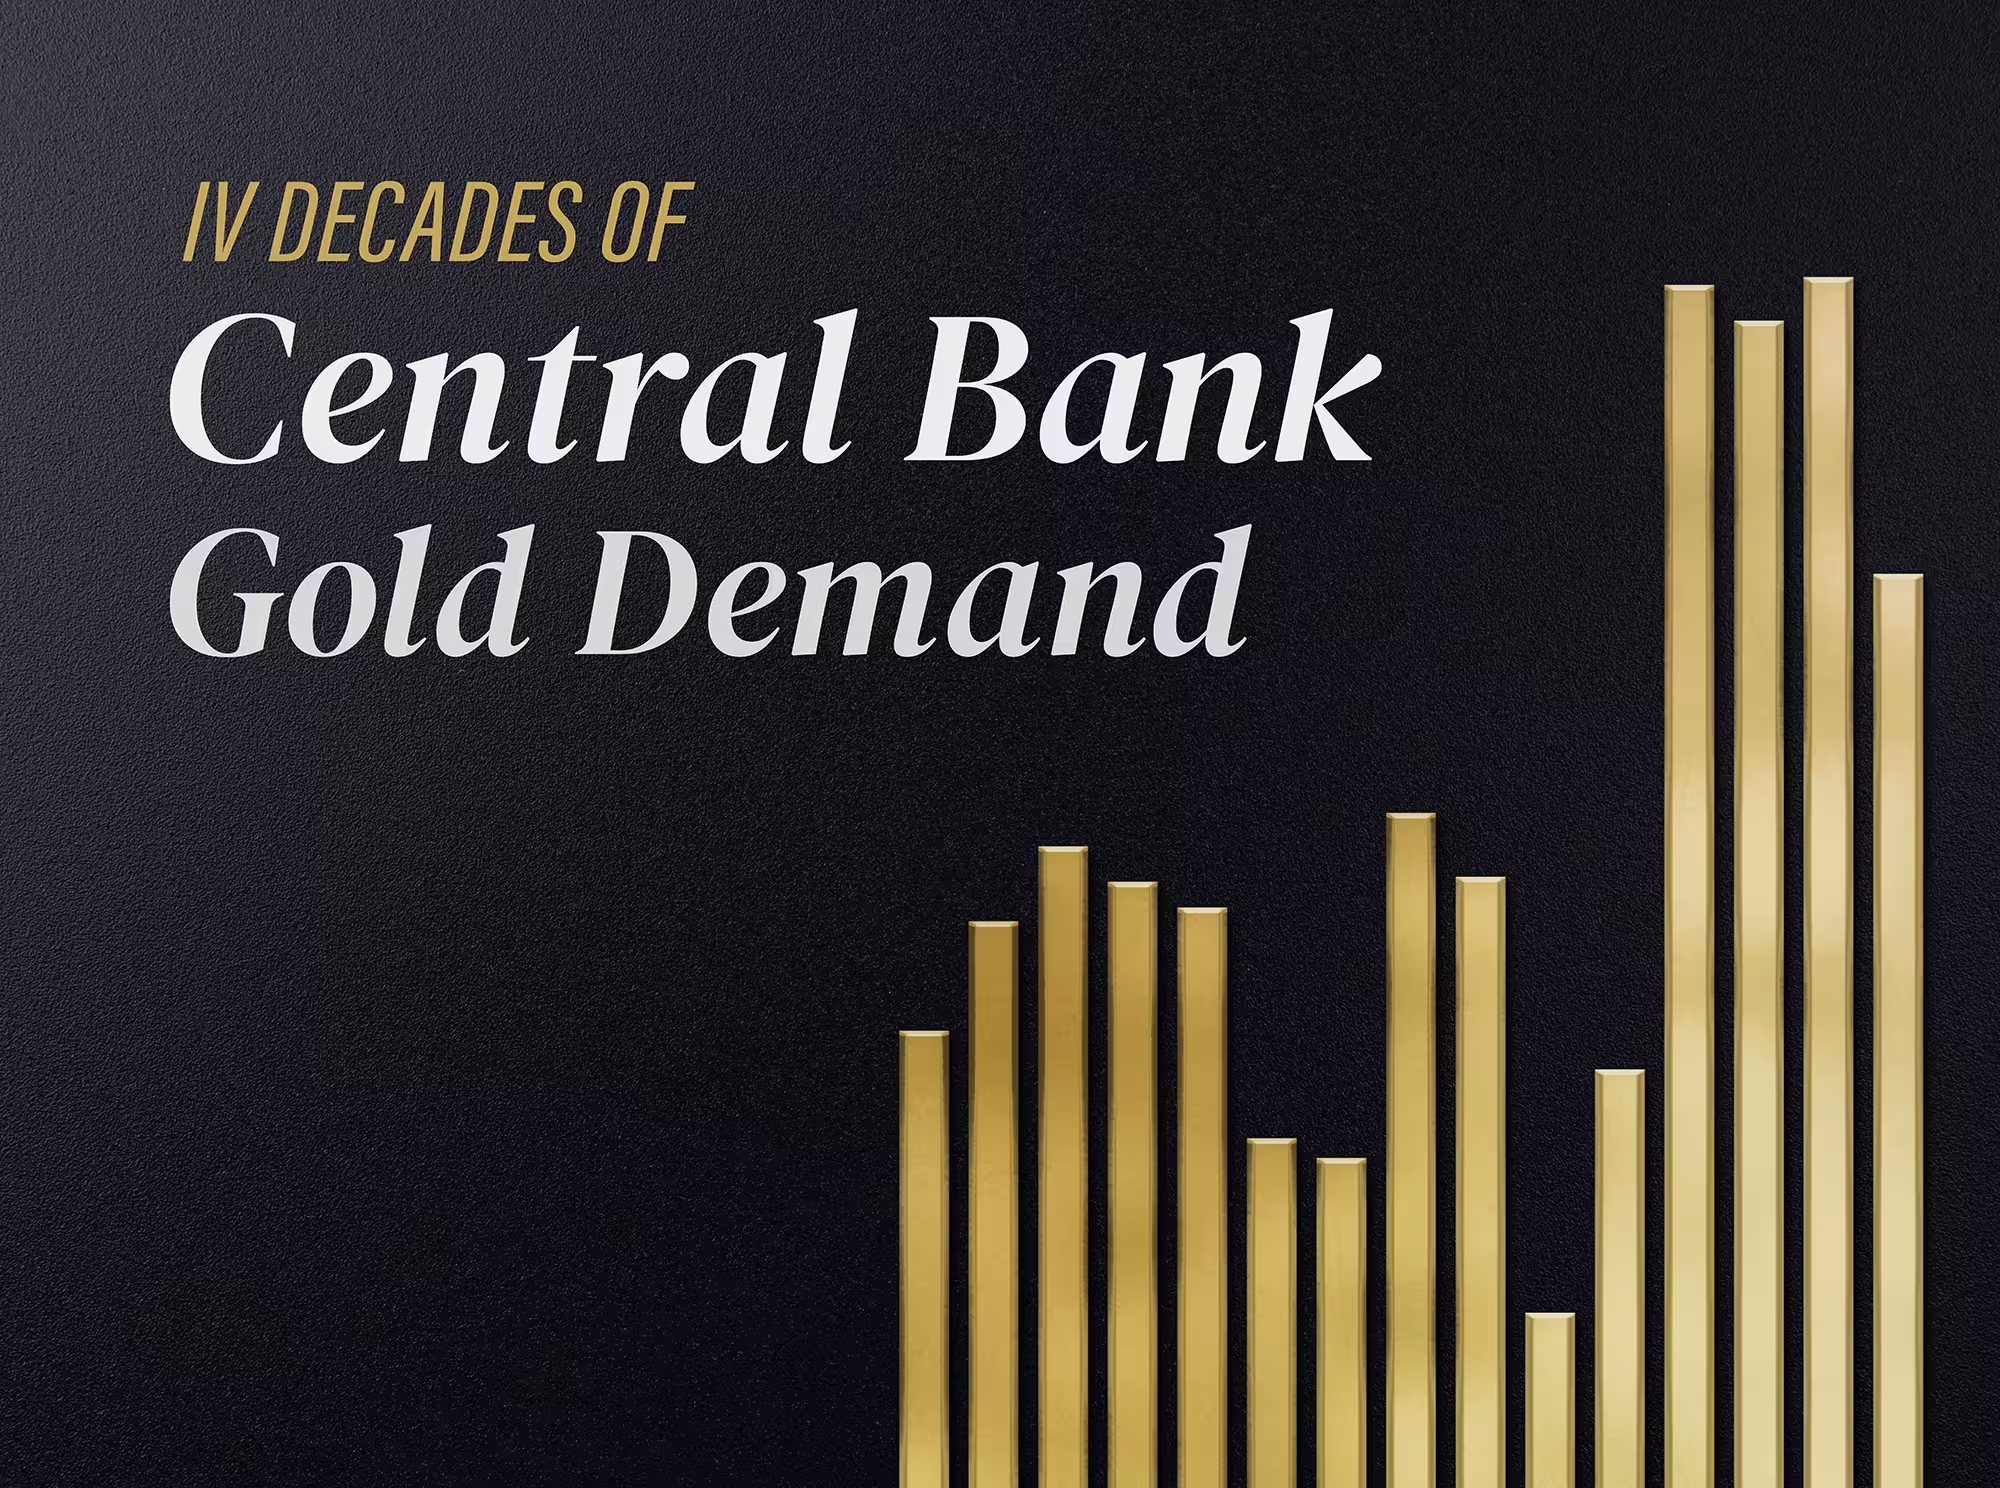
Central Banks Have Been Net Gold Buyers Since 2010, After Two Decades of Net Selling
Central Banks Have Been Net Gold Buyers Since 2010, After Two Decades of Net Selling
Central banks bought more gold between April and June 2026 than in any second quarter on record, according to a World Gold Council report published on July 30. That keeps them net buyers this year, as they have been every year since 2010. Underneath, the picture is changing. Russia and Türkiye, both big buyers in the past, have been selling.

Gold Mines in West Africa: Two Billion Years in the Making
Gold Mines in West Africa: Two Billion Years in the Making
The nine West African countries with significant reported output produced about 15% of the world's mined gold in 2025, according to Metals Focus and World Gold Council data. Almost every mine on the map above was built in the past 25 years, and four more reached production in the last eighteen months: Lafigué in Côte d'Ivoire in June 2024, Kiaka in Burkina Faso in June 2025, Ahafo North in Ghana in October 2025 and Kiniero in Guinea in December 2025.