Cobalt
January 17, 2025
1 min
Cobalt


This graphic and article explores cobalt production in 2023, spotlighting top producers and analyzing changes in supply, demand, and pricing.
Production and Supply
- Democratic Republic of Congo (DRC): The DRC maintained its position as the world's leading cobalt producer, contributing about 70% of global cobalt supply. However, the country aimed to reduce its heavy reliance on Chinese mining companies, which control approximately 80% of Congolese cobalt mines. To diversify, the DRC sought investments from Saudi Arabia, the European Union, and India. Major mines in the country include Kamoto (27,600t), Kisanfu (25,500t), Metalkol (22,610t), and Tenke Fungurume (22,500t). Key players include CMOC, Glencore, and Eurasian Resources. Rising output and Chinese investment drive the DRC's cobalt dominance.
- Indonesia: Indonesia emerged as the second-largest cobalt producer, providing 7% of global supply. This growth came largely from cobalt produced as a by-product of the country's expanding nickel industry, which is crucial for battery production. Major projects include the Weda Bay Project (a joint venture with Eramet and Tsingshan), PT Halmahera Persada Lygend (Harita Group and Ningbo Lygend), and PT Huayue Nickel Cobalt (Huayou Cobalt and Tsingshan). These projects focus on producing mixed hydroxide precipitate (MHP) for EV batteries, positioning Indonesia as a growing force in the global battery supply chain.
Market Dynamics
- Supply Surplus: The cobalt market faced a significant surplus in 2023, with inventory levels rising. By mid-year, 684 tons of cobalt were stockpiled in London Metal Exchange warehouses. This oversupply was driven by increased production in the DRC and Indonesia.
- Price Decline: Since November 2022, cobalt prices have experienced a notable decline. This price decline is primarily driven by a combination of factors, including increased global supply and softened demand.
Source: U.S. Geological Survey, Mineral Commodity Summaries, January 2024


Explore More
View All

What Each Part of the Mining Ecosystem Does
What Each Part of the Mining Ecosystem Does
Metal starts as rock that no one has found yet. Exploration and drilling turn it into a known deposit. The deposit is then financed, built, equipped and mined, and its concentrate is smelted and refined into metal. Each stage is its own industry, with its own listed companies, and their revenue depends on different things. The section below explains how each step works and makes its money, with a recent example from each.
Pakistan’s Mineral Export Outlook to 2039 and the Pipeline Behind It
Pakistan’s Mineral Export Outlook to 2039 and the Pipeline Behind It
Pakistan’s mineral export earnings could reach US$10.46 billion a year by 2039, up from US$932 million in 2025, according to a tentative outlook from the Petroleum Division. Other estimates start from a higher base: a projection by the Institute of Cost and Management Accountants of Pakistan, reported by APP, puts current mineral exports at about US$3 billion.
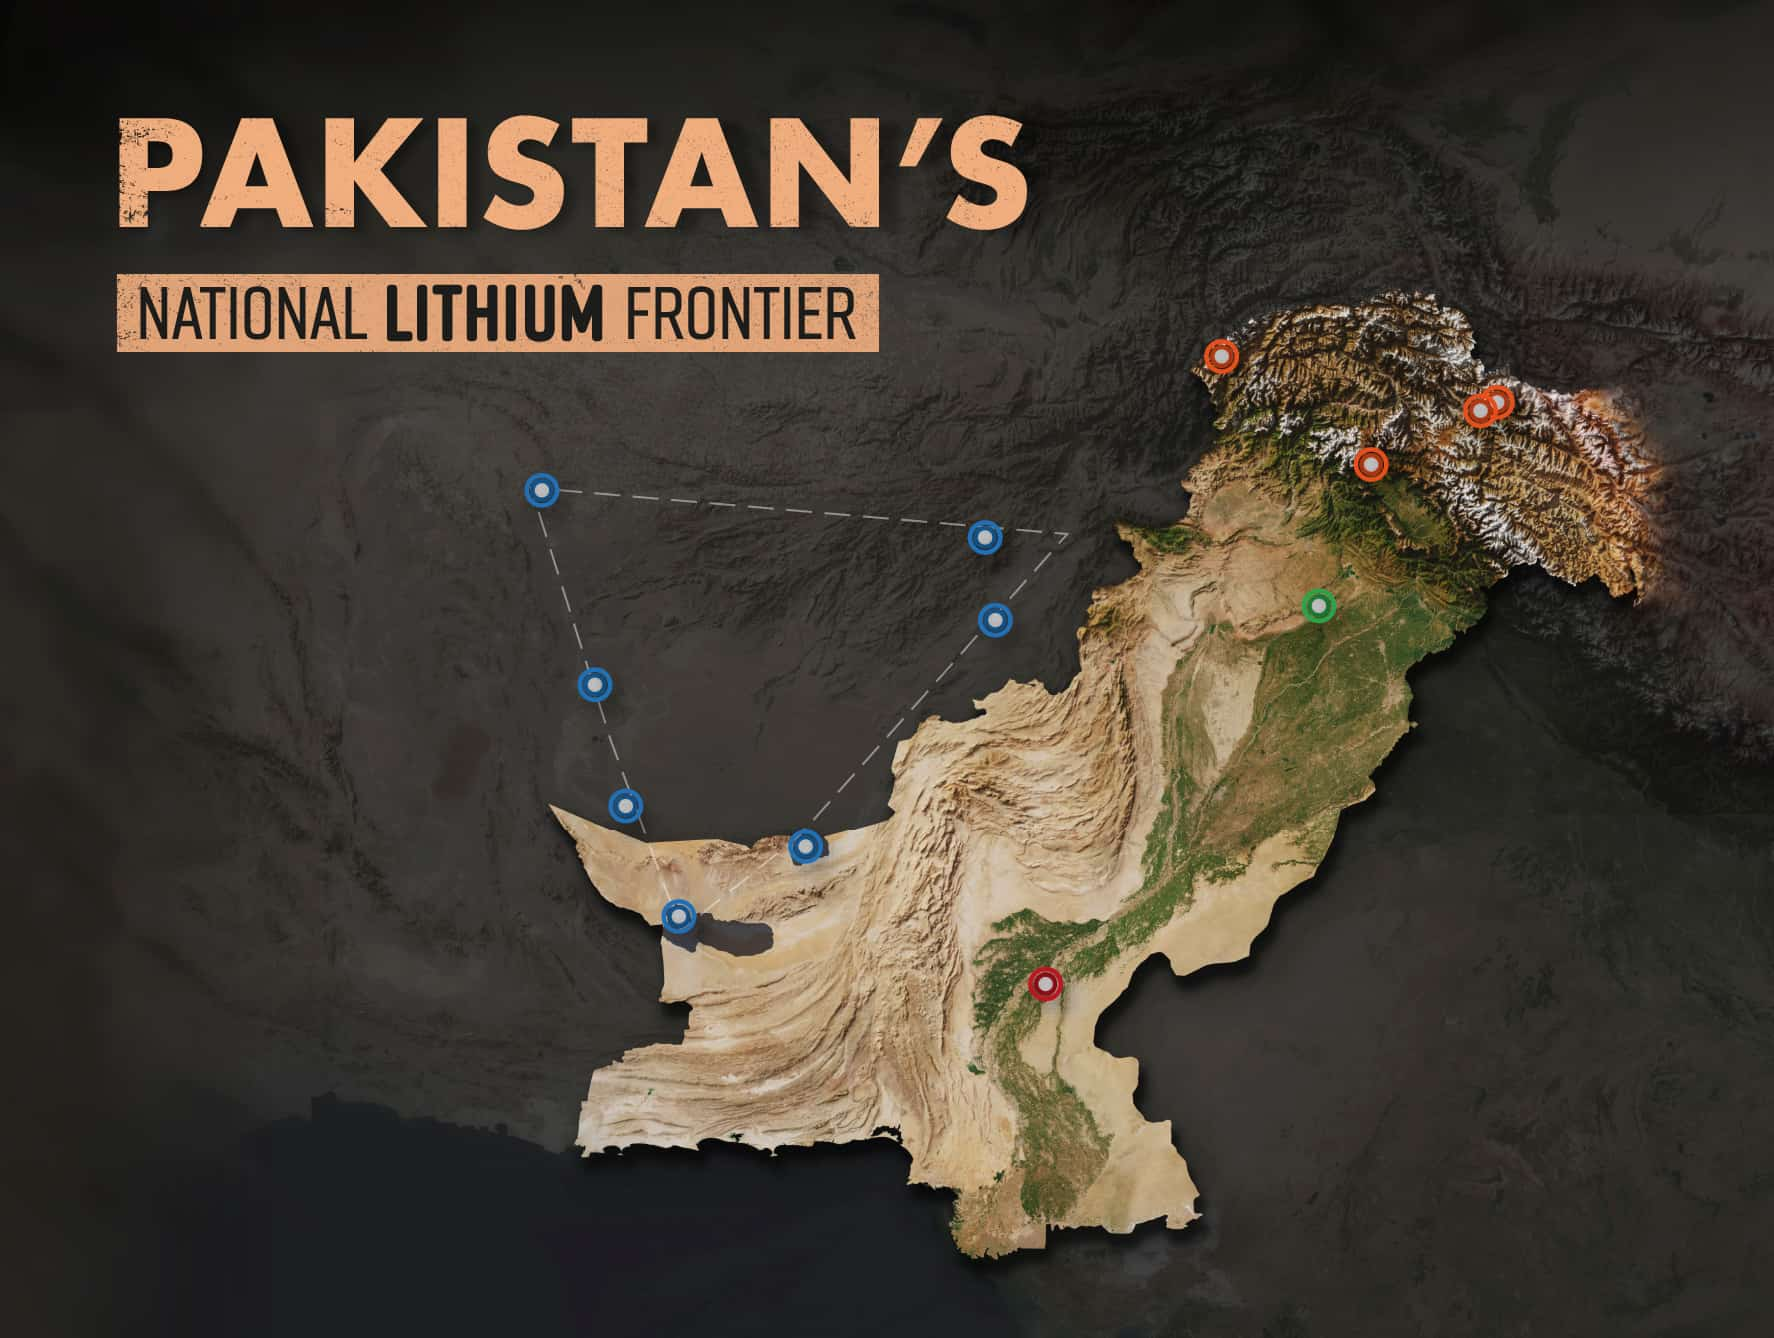
Where Lithium Has Been Identified Across Pakistan
Where Lithium Has Been Identified Across Pakistan
Lithium has been reported in four geological settings in Pakistan: brine lakes in Balochistan, geothermal well brine in Sindh, pegmatites in the northern mountains and clays in the Salt Range. A 2025 concept note by Geological Survey of Pakistan scientists describes these occurrences as potential and gives no resource estimates.
How Heat Sorts the Metals in a Polymetallic Deposit
How Heat Sorts the Metals in a Polymetallic Deposit
On November 6, 2025, the U.S. Interior Department added copper, silver and lead to its final critical minerals list, among 10 new entries. All three are main metals of a polymetallic deposit, where the USGS vein model places them in zones around a single intrusion. Silver shows how closely these metals are linked. The USGS says U.S. silver is "primarily obtained as a byproduct from lead-zinc, copper, and gold mines", and six smaller metals on the infographic reach the market the same way.