Copper
December 19, 2024
2 min
Copper


A recent S&P Global report reveals that the average time for copper mines to transition from discovery to production has lengthened significantly. Globally, this process now takes about 17.9 years, with the United States experiencing even longer timelines—nearly 29 years on average.
Zambia is the only country surpassing the U.S., with a staggering 34-year average.
Key contributors to these delays include lengthy permitting processes, regulatory challenges, and investment uncertainties. These bottlenecks contrast sharply with surging demand for copper, fueled by its critical role in technologies like electric vehicles and renewable energy infrastructure.
This growing supply-demand gap poses serious risks to meeting future copper needs, particularly as nations accelerate decarbonization efforts. Complex regulatory systems in the U.S. and elsewhere exacerbate these delays, making it difficult for new projects to meet rising global demand.
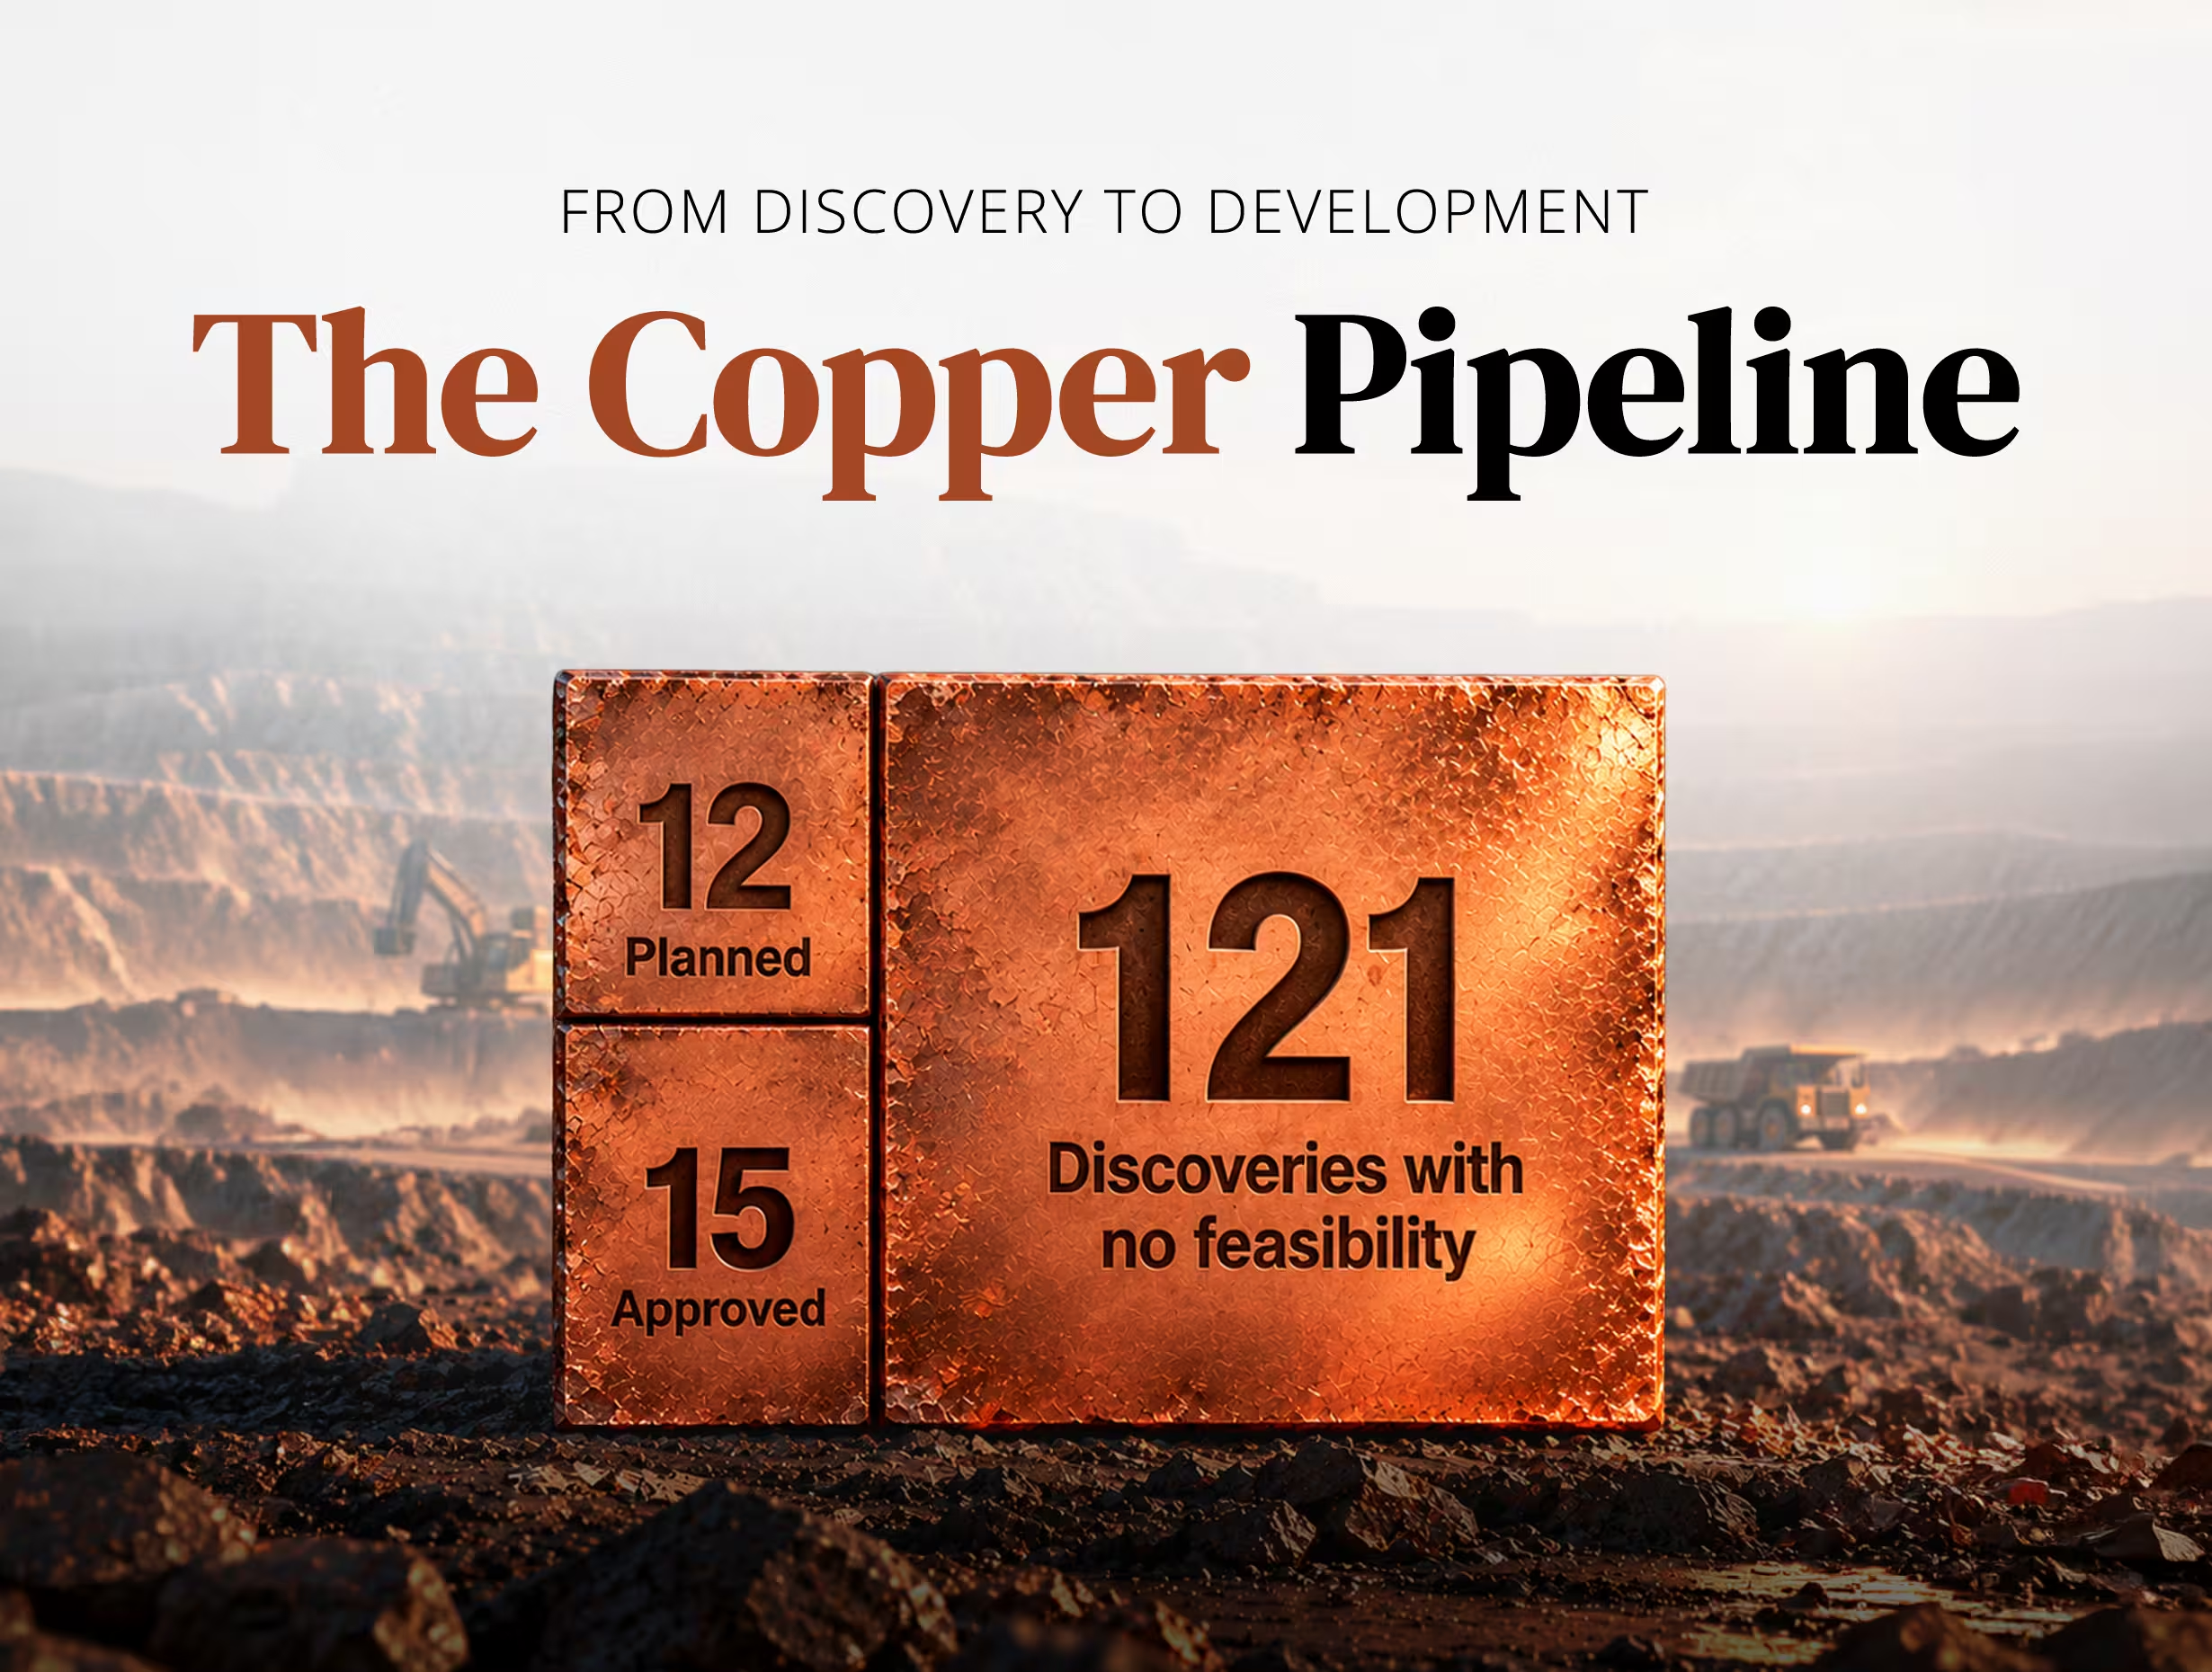
Worryingly, many projects are stalled before they even reach the development phase. Of 239 major discoveries analyzed in the report, 148 remain undeveloped, with 121 still undergoing feasibility studies. Only 15 have reached the construction stage and begun development.
Without significant reforms in permitting and development processes, the copper industry may struggle to meet the demands of a rapidly electrifying world.
Sponsored by:
Arras Minerals is a mining exploration company focused on copper and gold projects in northeast Kazakhstan, with key assets including Elemes, Tay, and Beskauga. The company also partners with Teck Resources on a 1,900 sq km exploration area funded by Teck. Arras aims to expand exploration in Kazakhstan's prolific mineral belts, leveraging untapped potential through drilling and geological surveys to define resources and grow its portfolio.
Learn more about Arras Minerals at https://www.arrasminerals.com/
S&P Global Market Intelligence
The information presented here may contain inaccuracies and is subject to rounding. We do not guarantee that all information is complete or correct. We accept no responsibility for any errors, omissions, or outcomes resulting from the use of this information. This is not investment advice.


Explore More
View All


The World’s Largest Operating Copper Mines Alongside Reko Diq
The World’s Largest Operating Copper Mines Alongside Reko Diq
Ten operating mines in six countries each produced between 359,000 and 1.32 million tonnes of copper in 2025, according to Wood Mackenzie estimates. Reko Diq in Pakistan appears alongside them with a figure from Barrick’s feasibility study, which refers to planned future production. More than half of the ten mines’ combined output came from the five in South America. The 2025 figures also reflect a disrupted year at Grasberg in Indonesia, while Reko Diq’s number points to a project planned in two phases.
Most Major Copper Discoveries Since 1990 Are Still Not Mines.
Most Major Copper Discoveries Since 1990 Are Still Not Mines.
In May 2025, a joint venture of Lundin Mining and BHP released a resource estimate for its Vicuña district in the Andes, which S&P Global ranked as home to the largest greenfield copper discovery in 30 years. Per the same resource statement, the combined Filo del Sol and Josemaria deposits hold 13 million tonnes of contained copper in measured and indicated resources.
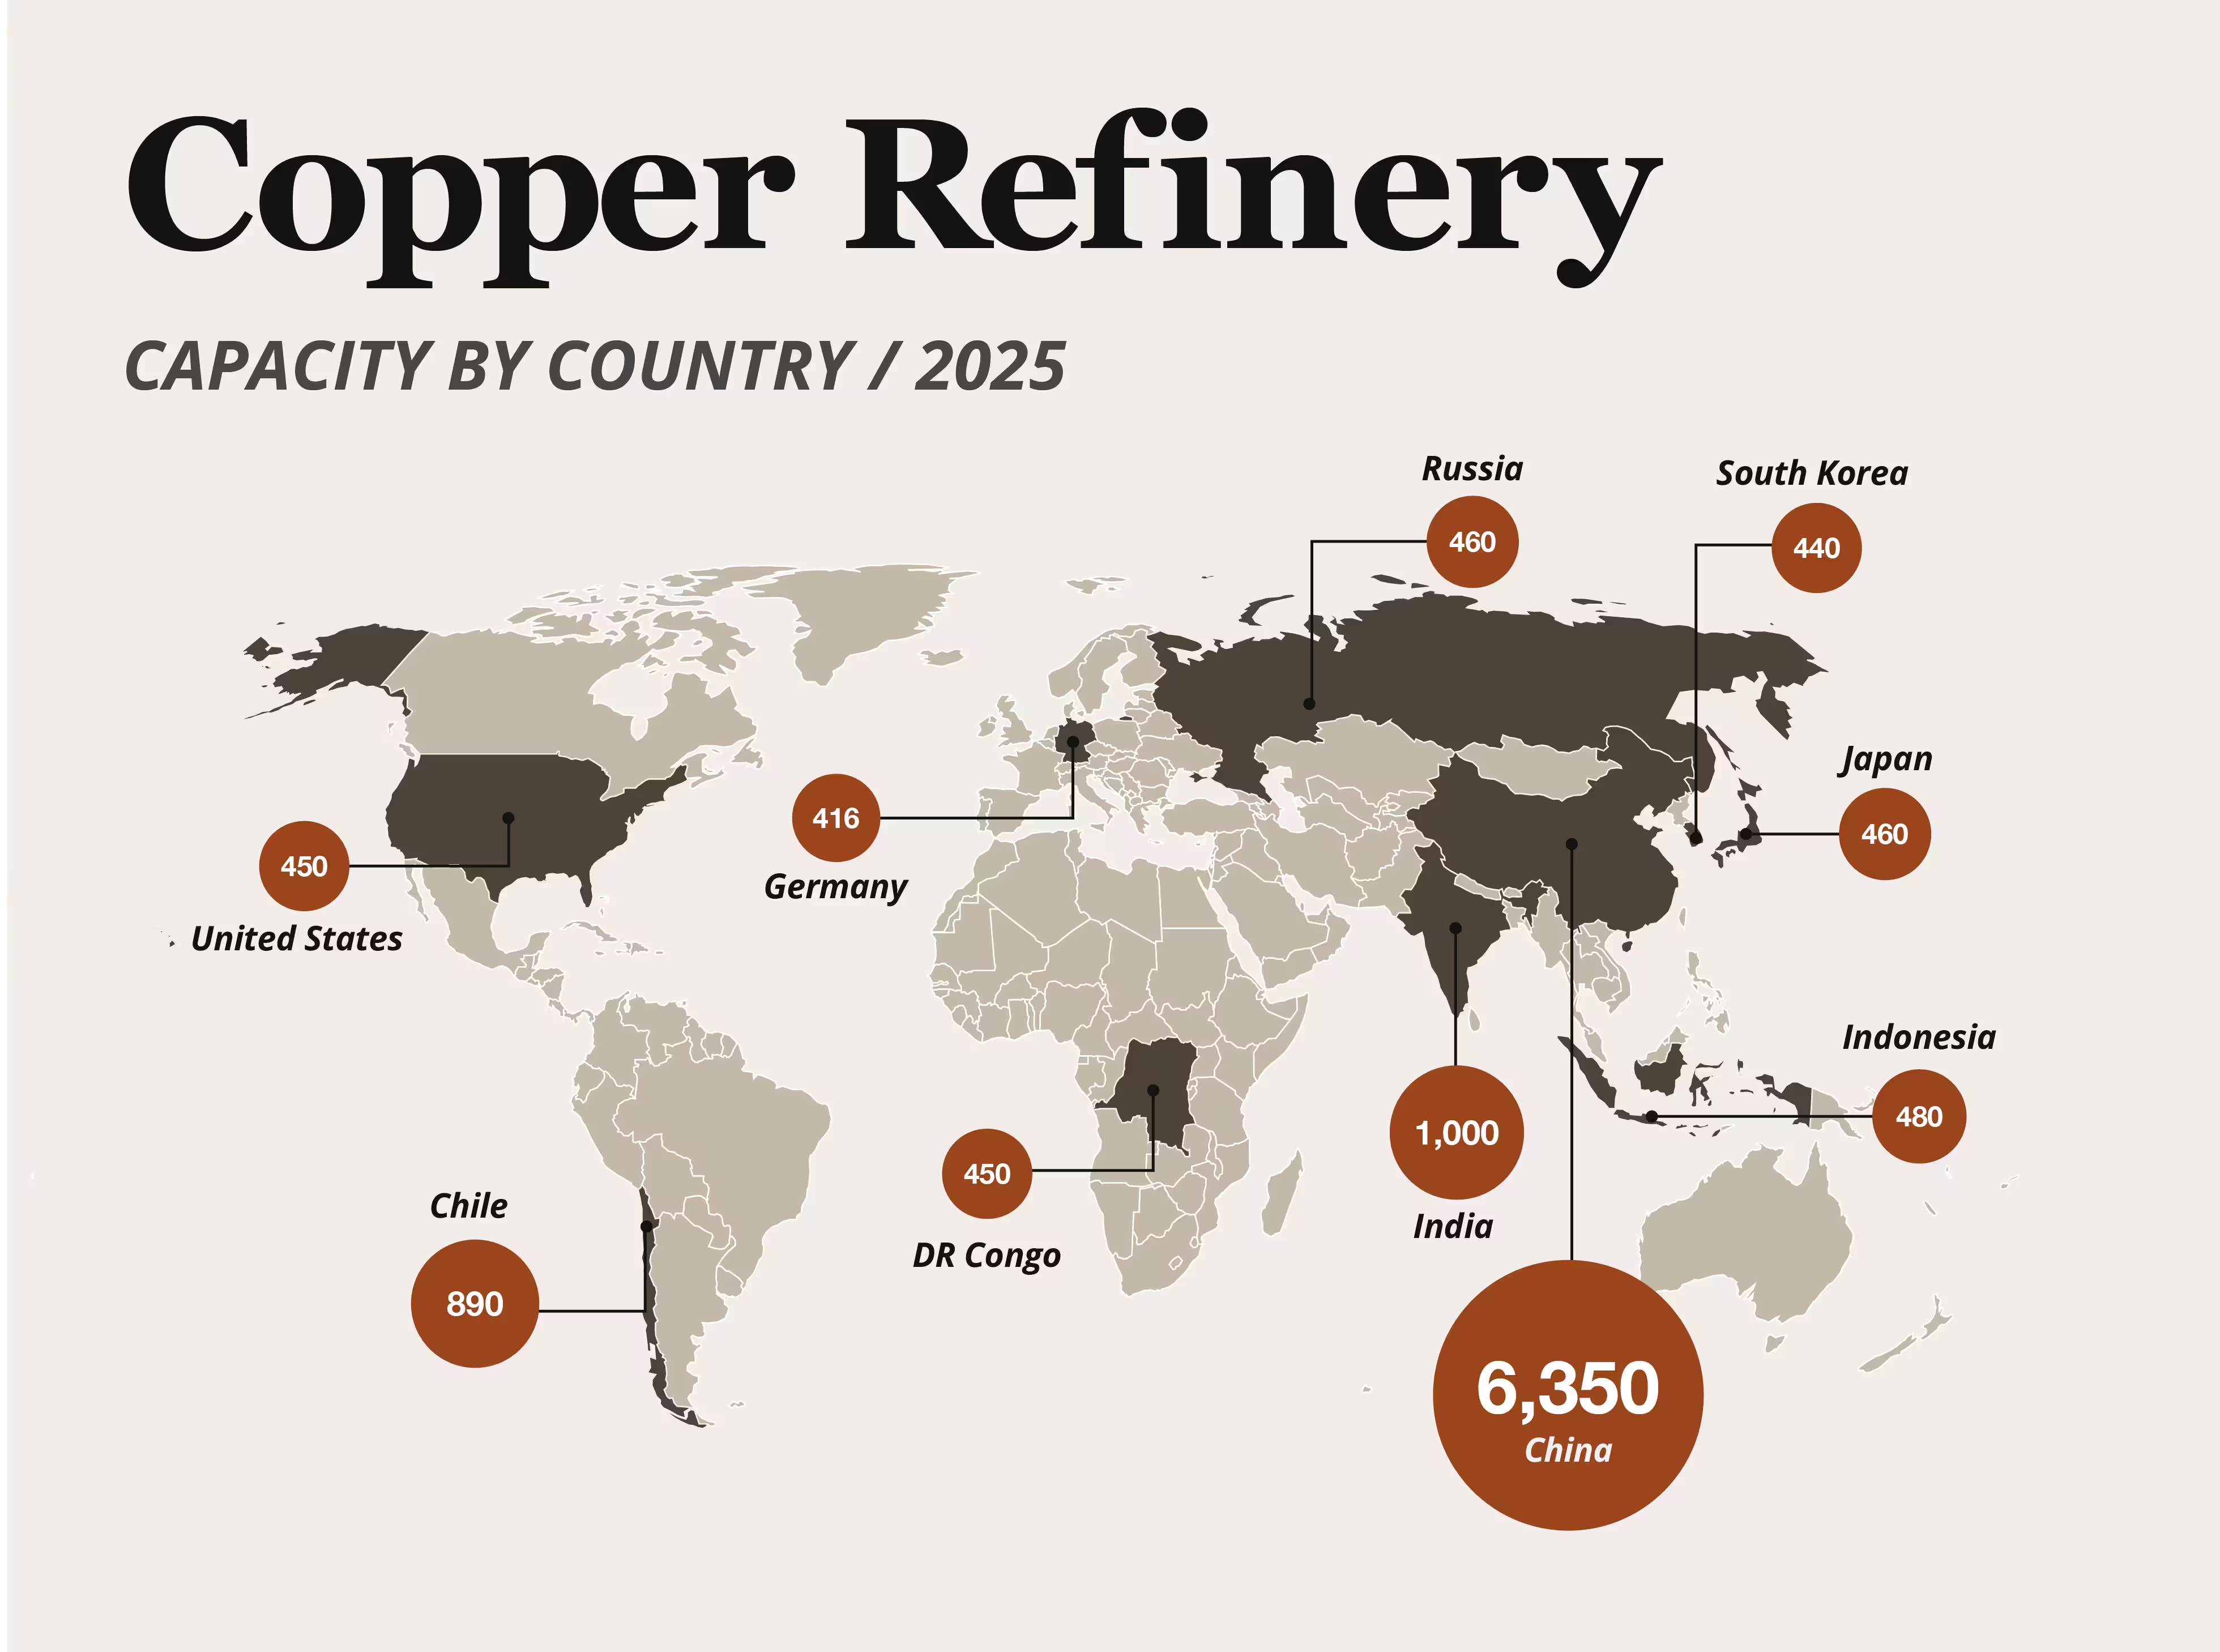
China Holds 56% of the Capacity at the World's 21 Largest Copper Refineries
China Holds 56% of the Capacity at the World's 21 Largest Copper Refineries
Indonesia's circle on the map above stands for a single plant: the Manyar refinery in East Java, operated by PT Freeport Indonesia, with 480,000 tonnes a year of capacity, according to the International Copper Study Group. It has been shut since the fourth quarter of 2025, after a mudflow at the Grasberg mine cut off its concentrate supply, and is due to restart this month at below 30% of capacity.
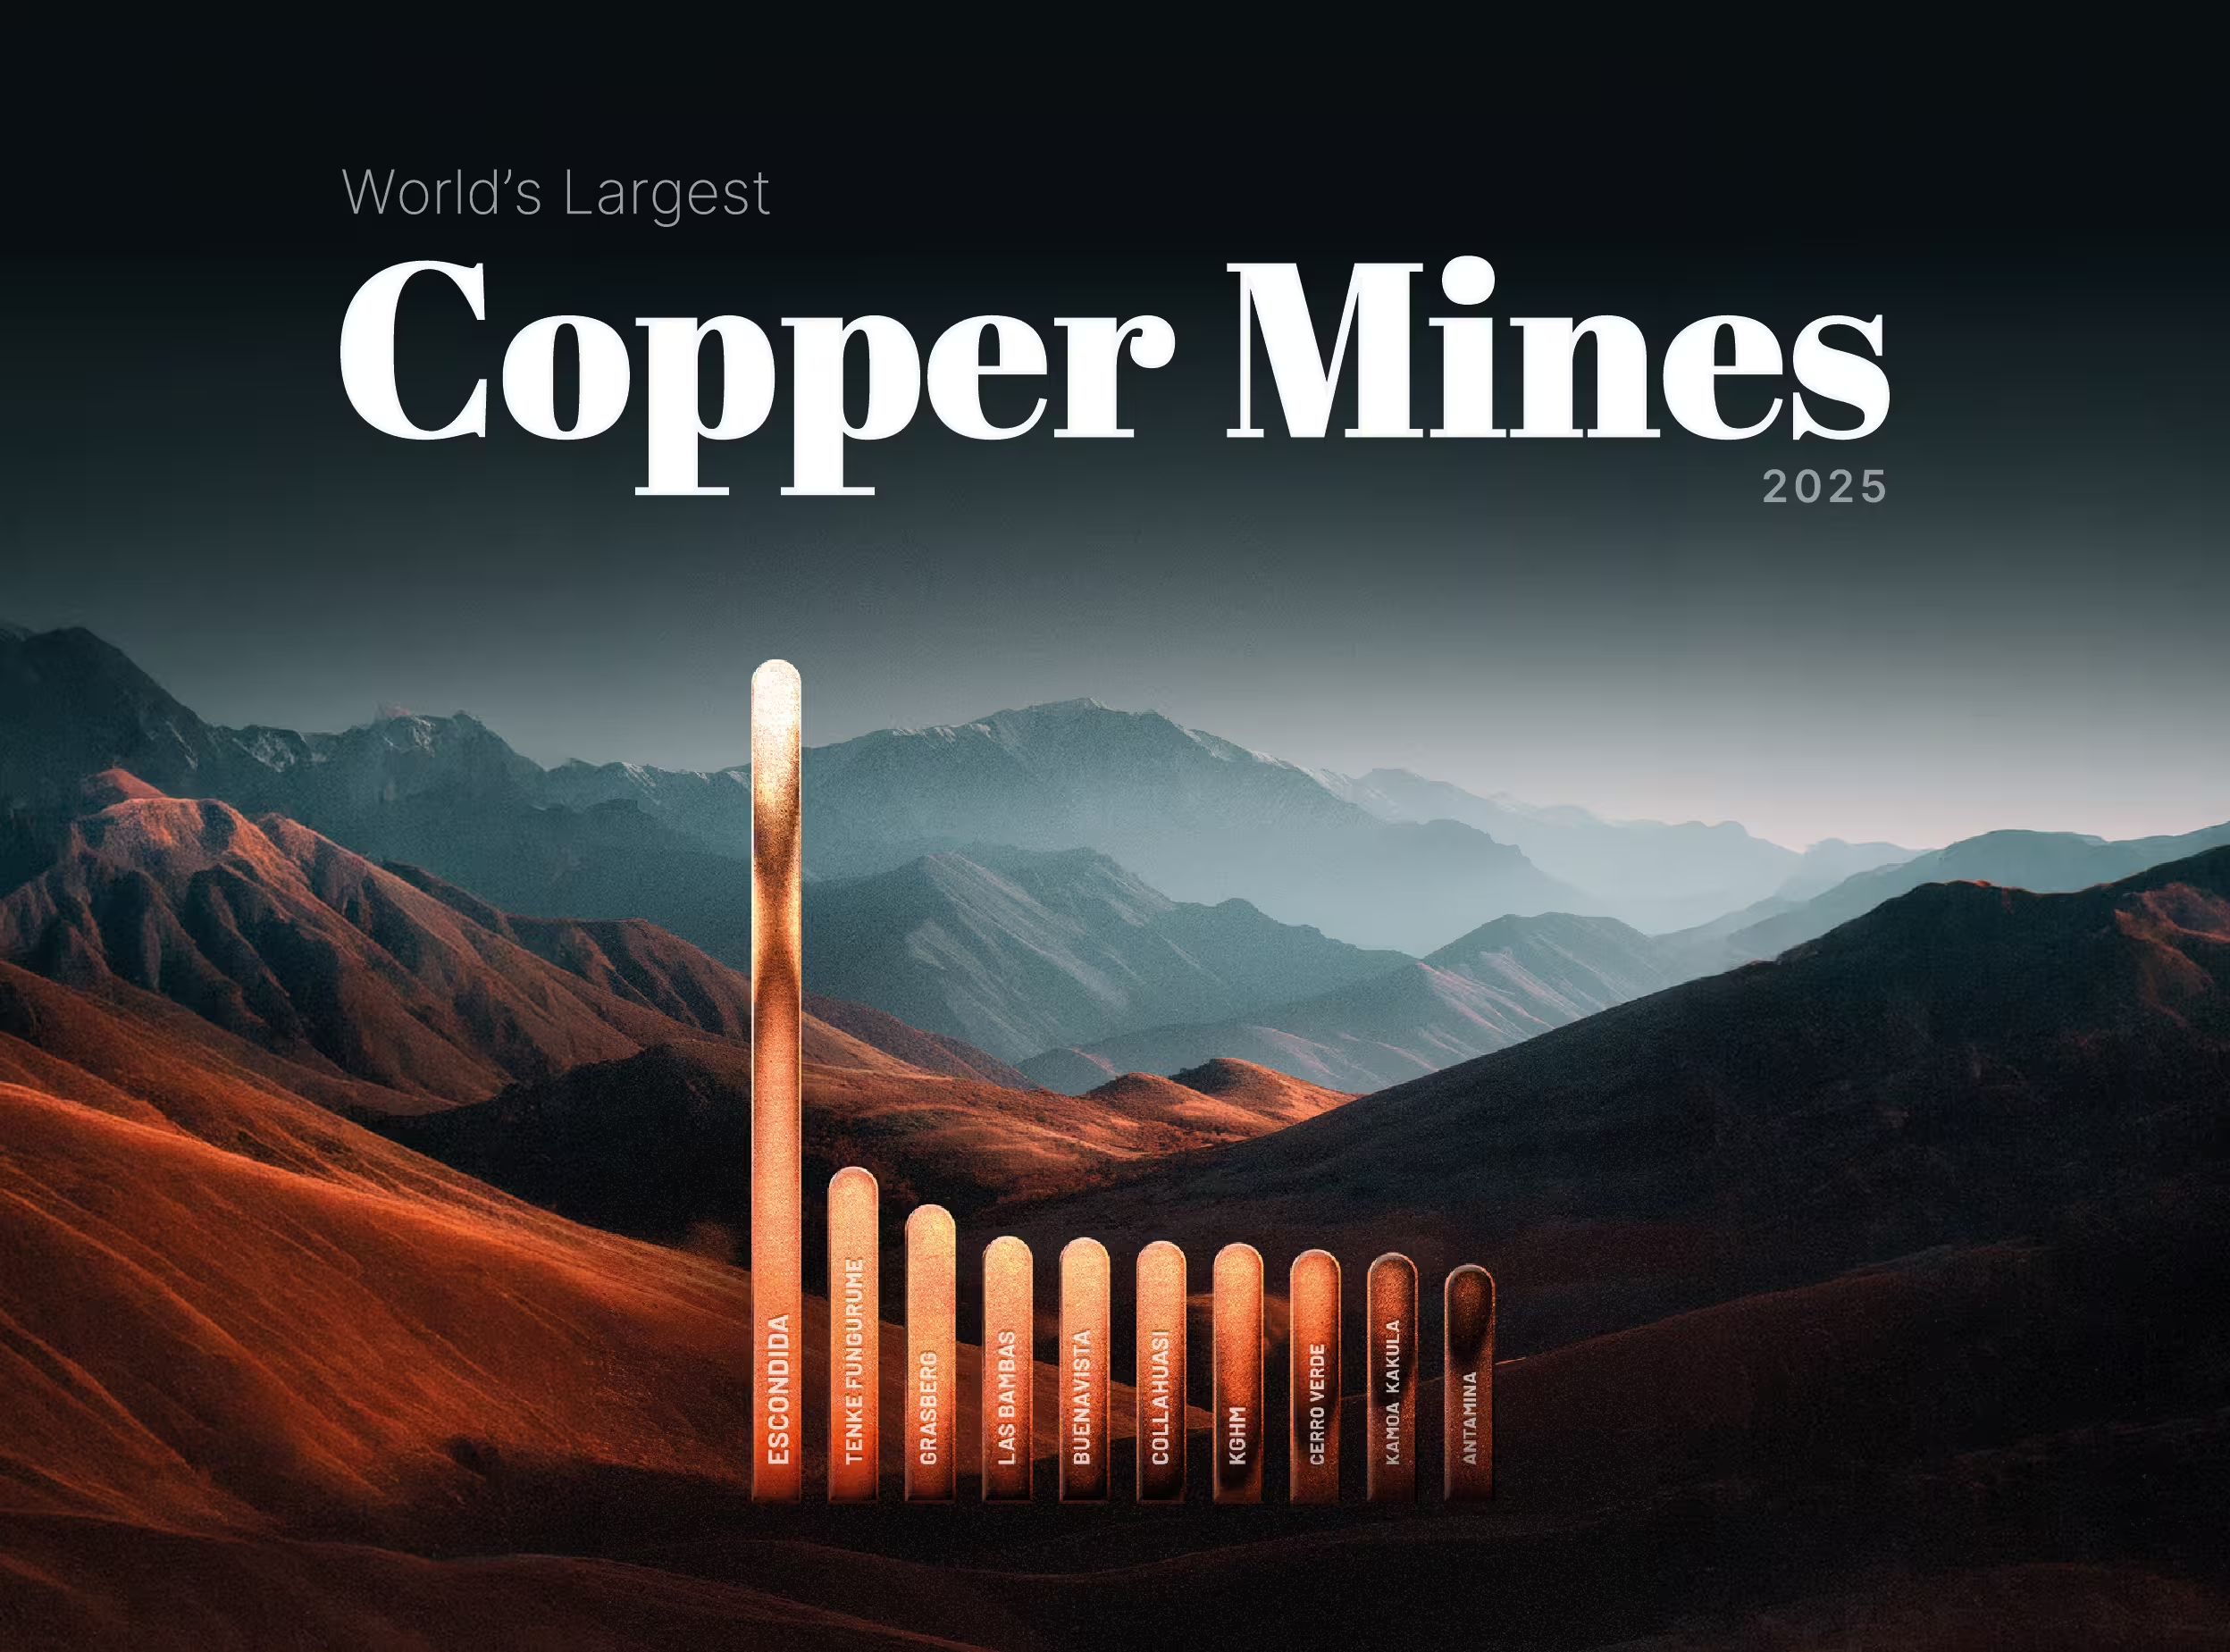
Ranked: The World's Largest Copper Mines (2025)
Ranked: The World's Largest Copper Mines (2025)
Copper has spent 2026 setting records, touching an intraday COMEX high of $6.71 per pound on May 13 amid AI-driven demand and supply shocks, against a backdrop where the ICSG now forecasts a 150,000-tonne deficit for 2026. In a market this tight, where the deficit thesis turns on lost tonnes, the question of where the world's copper actually comes from carries unusual weight.