Commodities
March 30, 2026
1 min
Commodities


Key takeaways
- Medical Essentiality: Magnetic resonance imaging (MRI) scanners represent 17% of U.S. demand. Because nothing substitutes for helium in cryogenic applications below -429 degrees Fahrenheit, healthcare faces strict dependencies.
- Tech Supply Chain Vulnerability: Controlled atmospheres, fiber optics, and semiconductors consume 15% of U.S. helium. Execs confirm this shortage is already impacting tech supply chains, forcing suppliers to strictly prioritize chipmakers.
- Domestic Supply Restructuring: The U.S. Federal Helium System was fully privatized and sold in two lots in January 2024. The U.S. market must now face this global supply shock entirely through private sector management.
The global helium market is currently buckling under an unprecedented crisis. Following recent geopolitical conflicts, a massive production halt at Qatar's LNG facilities has effectively removed roughly 30% of the world's helium supply from the market. The fallout has been immediate and severe, triggering force majeure declarations from major suppliers and causing spot prices to spike by 70% to 100%. While the public often ties helium to party balloons, the reality is far more critical. In 2024, estimated domestic apparent consumption of Grade-A and gaseous helium in the U.S. was 56 million cubic meters. Understanding exactly where this gas goes is essential for investors and industry professionals trying to navigate a market where advanced chip production is actively threatened.
Beyond Balloons: The True Drivers of Helium Demand
While lifting gas accounts for 18% of U.S. helium consumption, the vast majority of supply powers critical industrial, scientific, and healthcare processes. The bedrock of this demand is the science sector. Analytical, engineering, lab, science, and specialty gases represent the largest slice of the pie, consuming 22% of all U.S. helium.
In the medical field, helium is a non-negotiable asset. MRI operations rely completely on helium as a coolant for their superconducting magnets. This single application accounts for a rigid 17% of total domestic consumption.
The Tech and Heavy Industry Backbone
Helium's unique chemical properties extend deeply into advanced manufacturing. Controlled atmospheres, fiber optics, and semiconductors account for 15% of U.S. usage. As global supply chains face extreme pressure from the Middle East disruptions, AI chipmaking is uniquely vulnerable. The lack of process gases is creating cascading knock-on effects that are actively threatening the production cycles of electric vehicles (EVs) and smartphones.
Furthermore, heavy industry relies on helium for welding (8%), aerospace, pressuring, and purging (7%), leak detection (5%), diving (5%), and various minor applications (3%). With major industrial gas suppliers scrambling, allocation priorities are heavily skewed toward keeping the high-margin semiconductor industry online, leaving secondary industrial users to fight over the remaining, heavily inflated supply.
The Domestic Supply Squeeze
The U.S. is not insulated from global constraints, especially following significant structural changes to its own historical reserves. The Helium Stewardship Act of 2013 mandated the privatization of the Federal Helium System. On January 25, 2024, the Federal Helium System assets were sold to a private entity.
Adding to the complexity, the lease for the Crude Helium Enrichment Unit (CHEU) at the Cliffside Field ended on August 11, 2024. The District Court of Amarillo, TX, had to intervene to allow the new owner to operate the equipment and keep domestic supply flowing while negotiations continued.
Final Synthesis: A Fragile Balance Exposed
The 2026 global helium supply shock exposes the fragility of a highly consolidated market dependent on a few geopolitical chokepoints. With Qatar's production halted and U.S. reserves recently privatized, the buffer against severe disruption has vanished. Because the vast majority of U.S. helium is strictly allocated to irreplaceable, high-tech, and life-saving applications, the structural deficit will continue to ripple through the global economy until Middle Eastern supply lines are restored.
MiningVisuals Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice.
Source: U.S. Geological Survey, Mineral Commodity Summaries, January 2025


Explore More
View All

What Each Part of the Mining Ecosystem Does
What Each Part of the Mining Ecosystem Does
Metal starts as rock that no one has found yet. Exploration and drilling turn it into a known deposit. The deposit is then financed, built, equipped and mined, and its concentrate is smelted and refined into metal. Each stage is its own industry, with its own listed companies, and their revenue depends on different things. The section below explains how each step works and makes its money, with a recent example from each.
Pakistan’s Mineral Export Outlook to 2039 and the Pipeline Behind It
Pakistan’s Mineral Export Outlook to 2039 and the Pipeline Behind It
Pakistan’s mineral export earnings could reach US$10.46 billion a year by 2039, up from US$932 million in 2025, according to a tentative outlook from the Petroleum Division. Other estimates start from a higher base: a projection by the Institute of Cost and Management Accountants of Pakistan, reported by APP, puts current mineral exports at about US$3 billion.
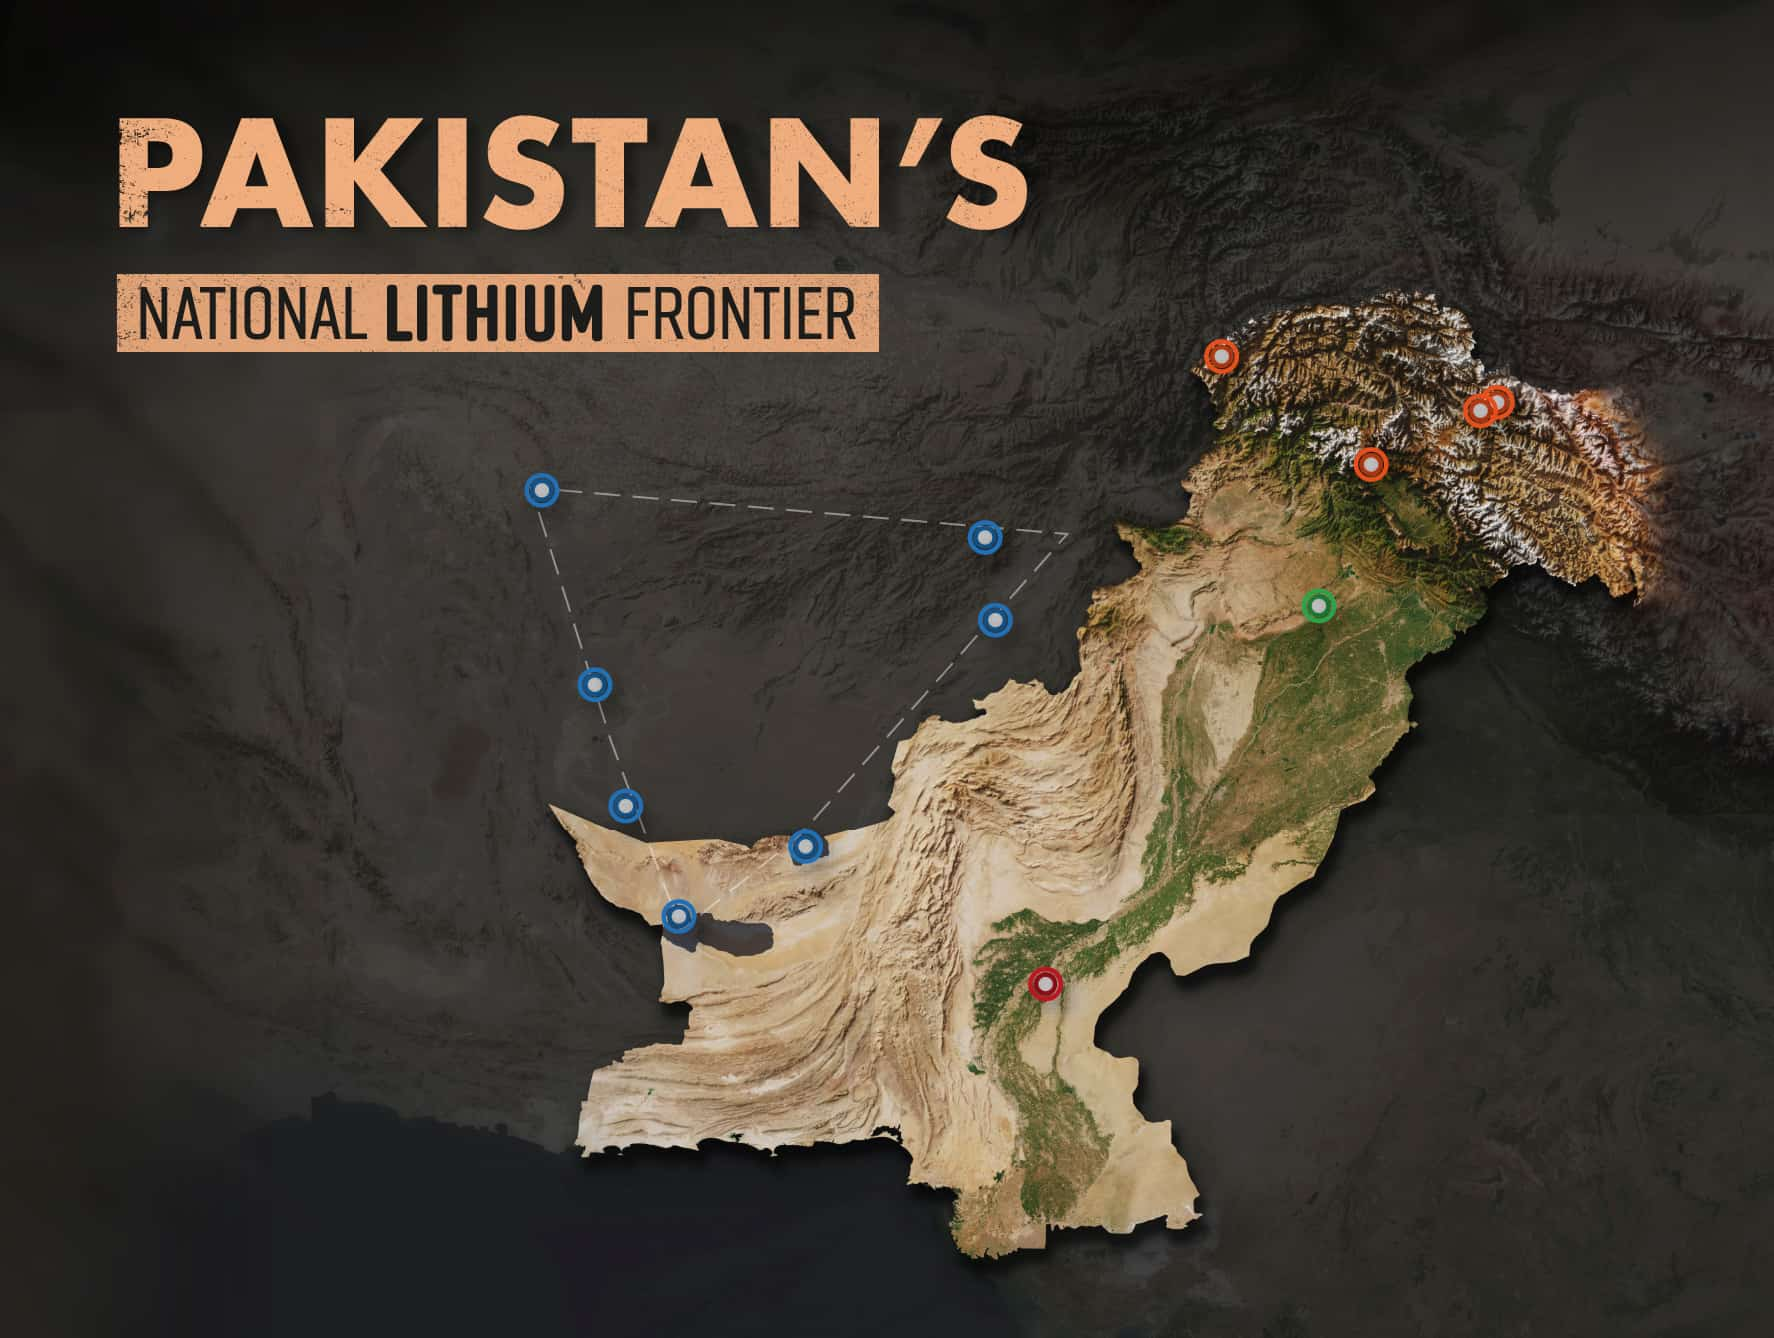
Where Lithium Has Been Identified Across Pakistan
Where Lithium Has Been Identified Across Pakistan
Lithium has been reported in four geological settings in Pakistan: brine lakes in Balochistan, geothermal well brine in Sindh, pegmatites in the northern mountains and clays in the Salt Range. A 2025 concept note by Geological Survey of Pakistan scientists describes these occurrences as potential and gives no resource estimates.
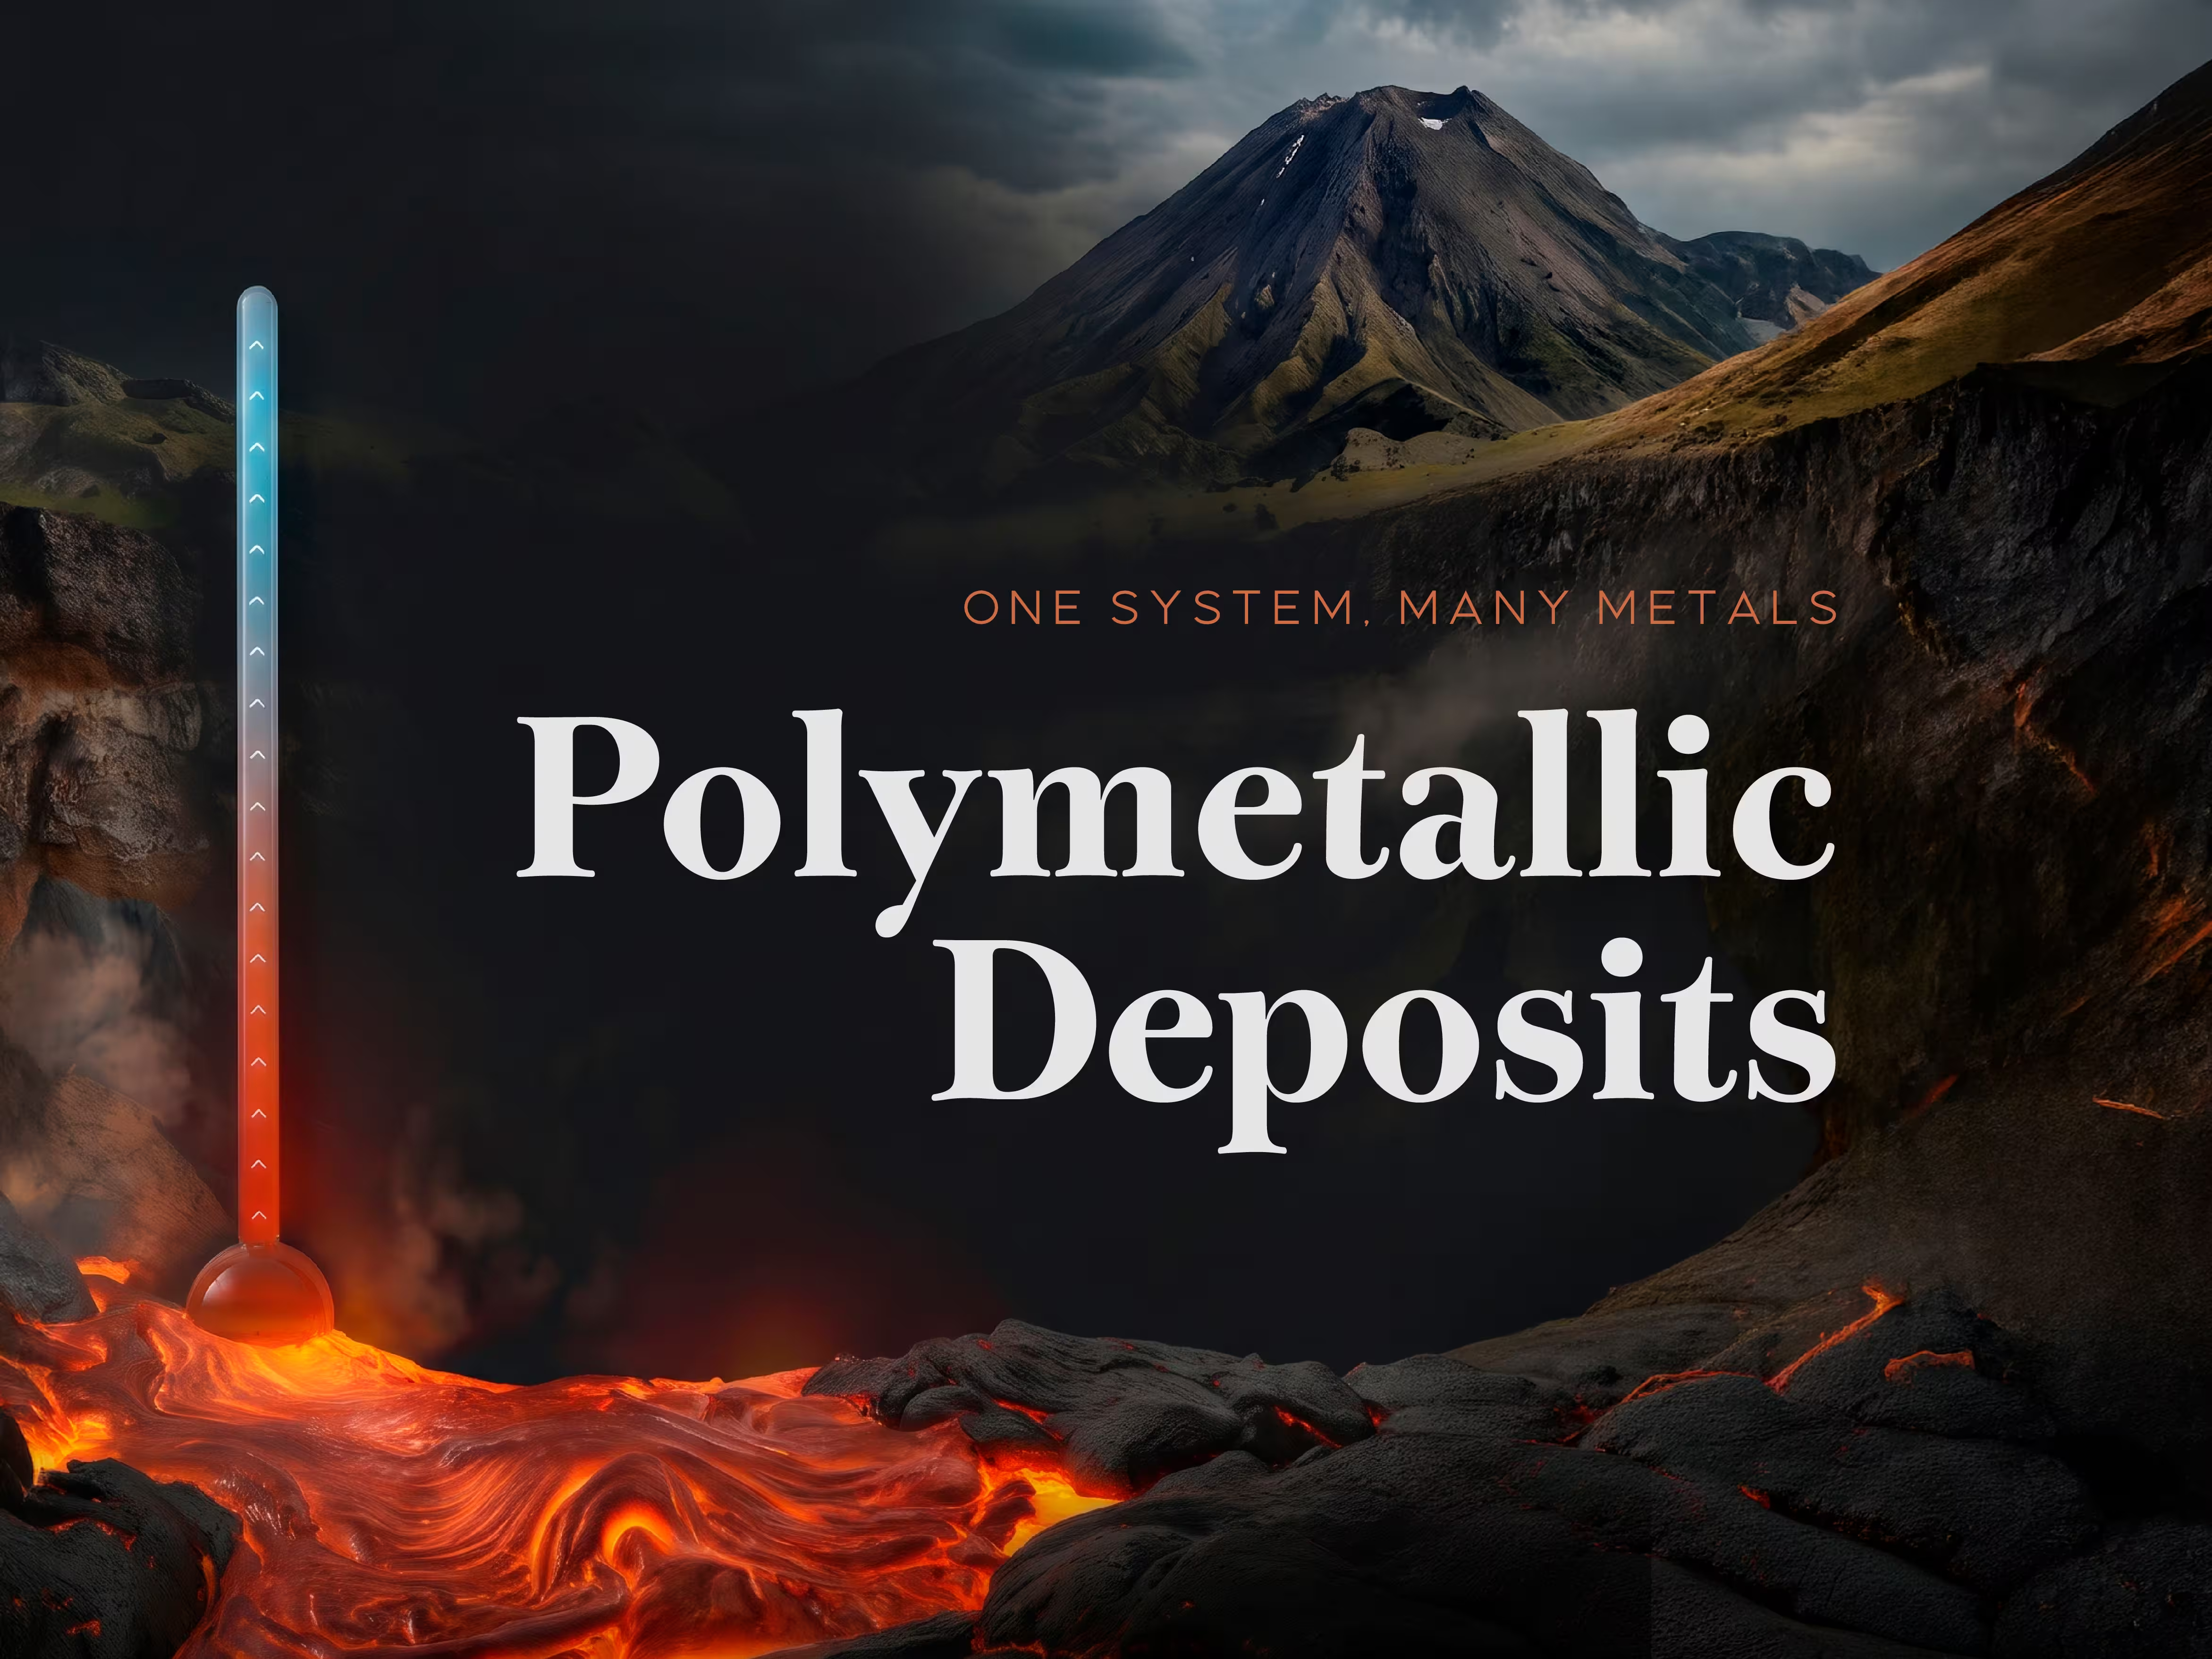
How Heat Sorts the Metals in a Polymetallic Deposit
How Heat Sorts the Metals in a Polymetallic Deposit
On November 6, 2025, the U.S. Interior Department added copper, silver and lead to its final critical minerals list, among 10 new entries. All three are main metals of a polymetallic deposit, where the USGS vein model places them in zones around a single intrusion. Silver shows how closely these metals are linked. The USGS says U.S. silver is "primarily obtained as a byproduct from lead-zinc, copper, and gold mines", and six smaller metals on the infographic reach the market the same way.