Copper
April 17, 2025
1 min
Copper


This infographic illustrates the significant evolution of global copper production among the world's largest producers from 1970 to approximately 2024. During this period, total world output has expanded considerably, reaching an estimated 23.0 million metric tons (MT) recently.
The data reveals notable shifts in production. While the United States was a leading producer in 1970, its relative global share has diminished over the decades.
Conversely, Chile experienced substantial growth, particularly from the late 1980s, emerging as the world's dominant copper producer – a position it maintains today with an estimated output of 5.3 MT.
More recent dramatic increases are evident for the Democratic Republic of Congo (DRC) and Peru, elevating them to the second and third largest producers, respectively (estimated at 3.1 MT and 2.8 MT). China also saw significant growth from the early 2000s, becoming another major producer (est. 1.8 MT).
Throughout this timeframe, Russia has maintained relatively consistent output, remaining one of the top six producers (est. 0.9 MT).
In summary, the global landscape for copper production has undergone a marked transformation over the past five decades, characterized by major shifts in the ranking of leading producer nations and substantial overall growth in supply.
Source: U.S. Geological Survey, Mineral Commodity Summaries, January 2025, https://ourworldindata.org/
Disclaimer: Data presented is sourced from the U.S. Geological Survey Mineral Commodity Summaries (January 2025) and ourworldindata.org, intended for general informational purposes only. Recent figures may be estimates. Accuracy and completeness are not guaranteed. This does not constitute financial or investment advice. Conduct your own research before making decisions.


Explore More
View All


The World’s Largest Operating Copper Mines Alongside Reko Diq
The World’s Largest Operating Copper Mines Alongside Reko Diq
Ten operating mines in six countries each produced between 359,000 and 1.32 million tonnes of copper in 2025, according to Wood Mackenzie estimates. Reko Diq in Pakistan appears alongside them with a figure from Barrick’s feasibility study, which refers to planned future production. More than half of the ten mines’ combined output came from the five in South America. The 2025 figures also reflect a disrupted year at Grasberg in Indonesia, while Reko Diq’s number points to a project planned in two phases.
Most Major Copper Discoveries Since 1990 Are Still Not Mines.
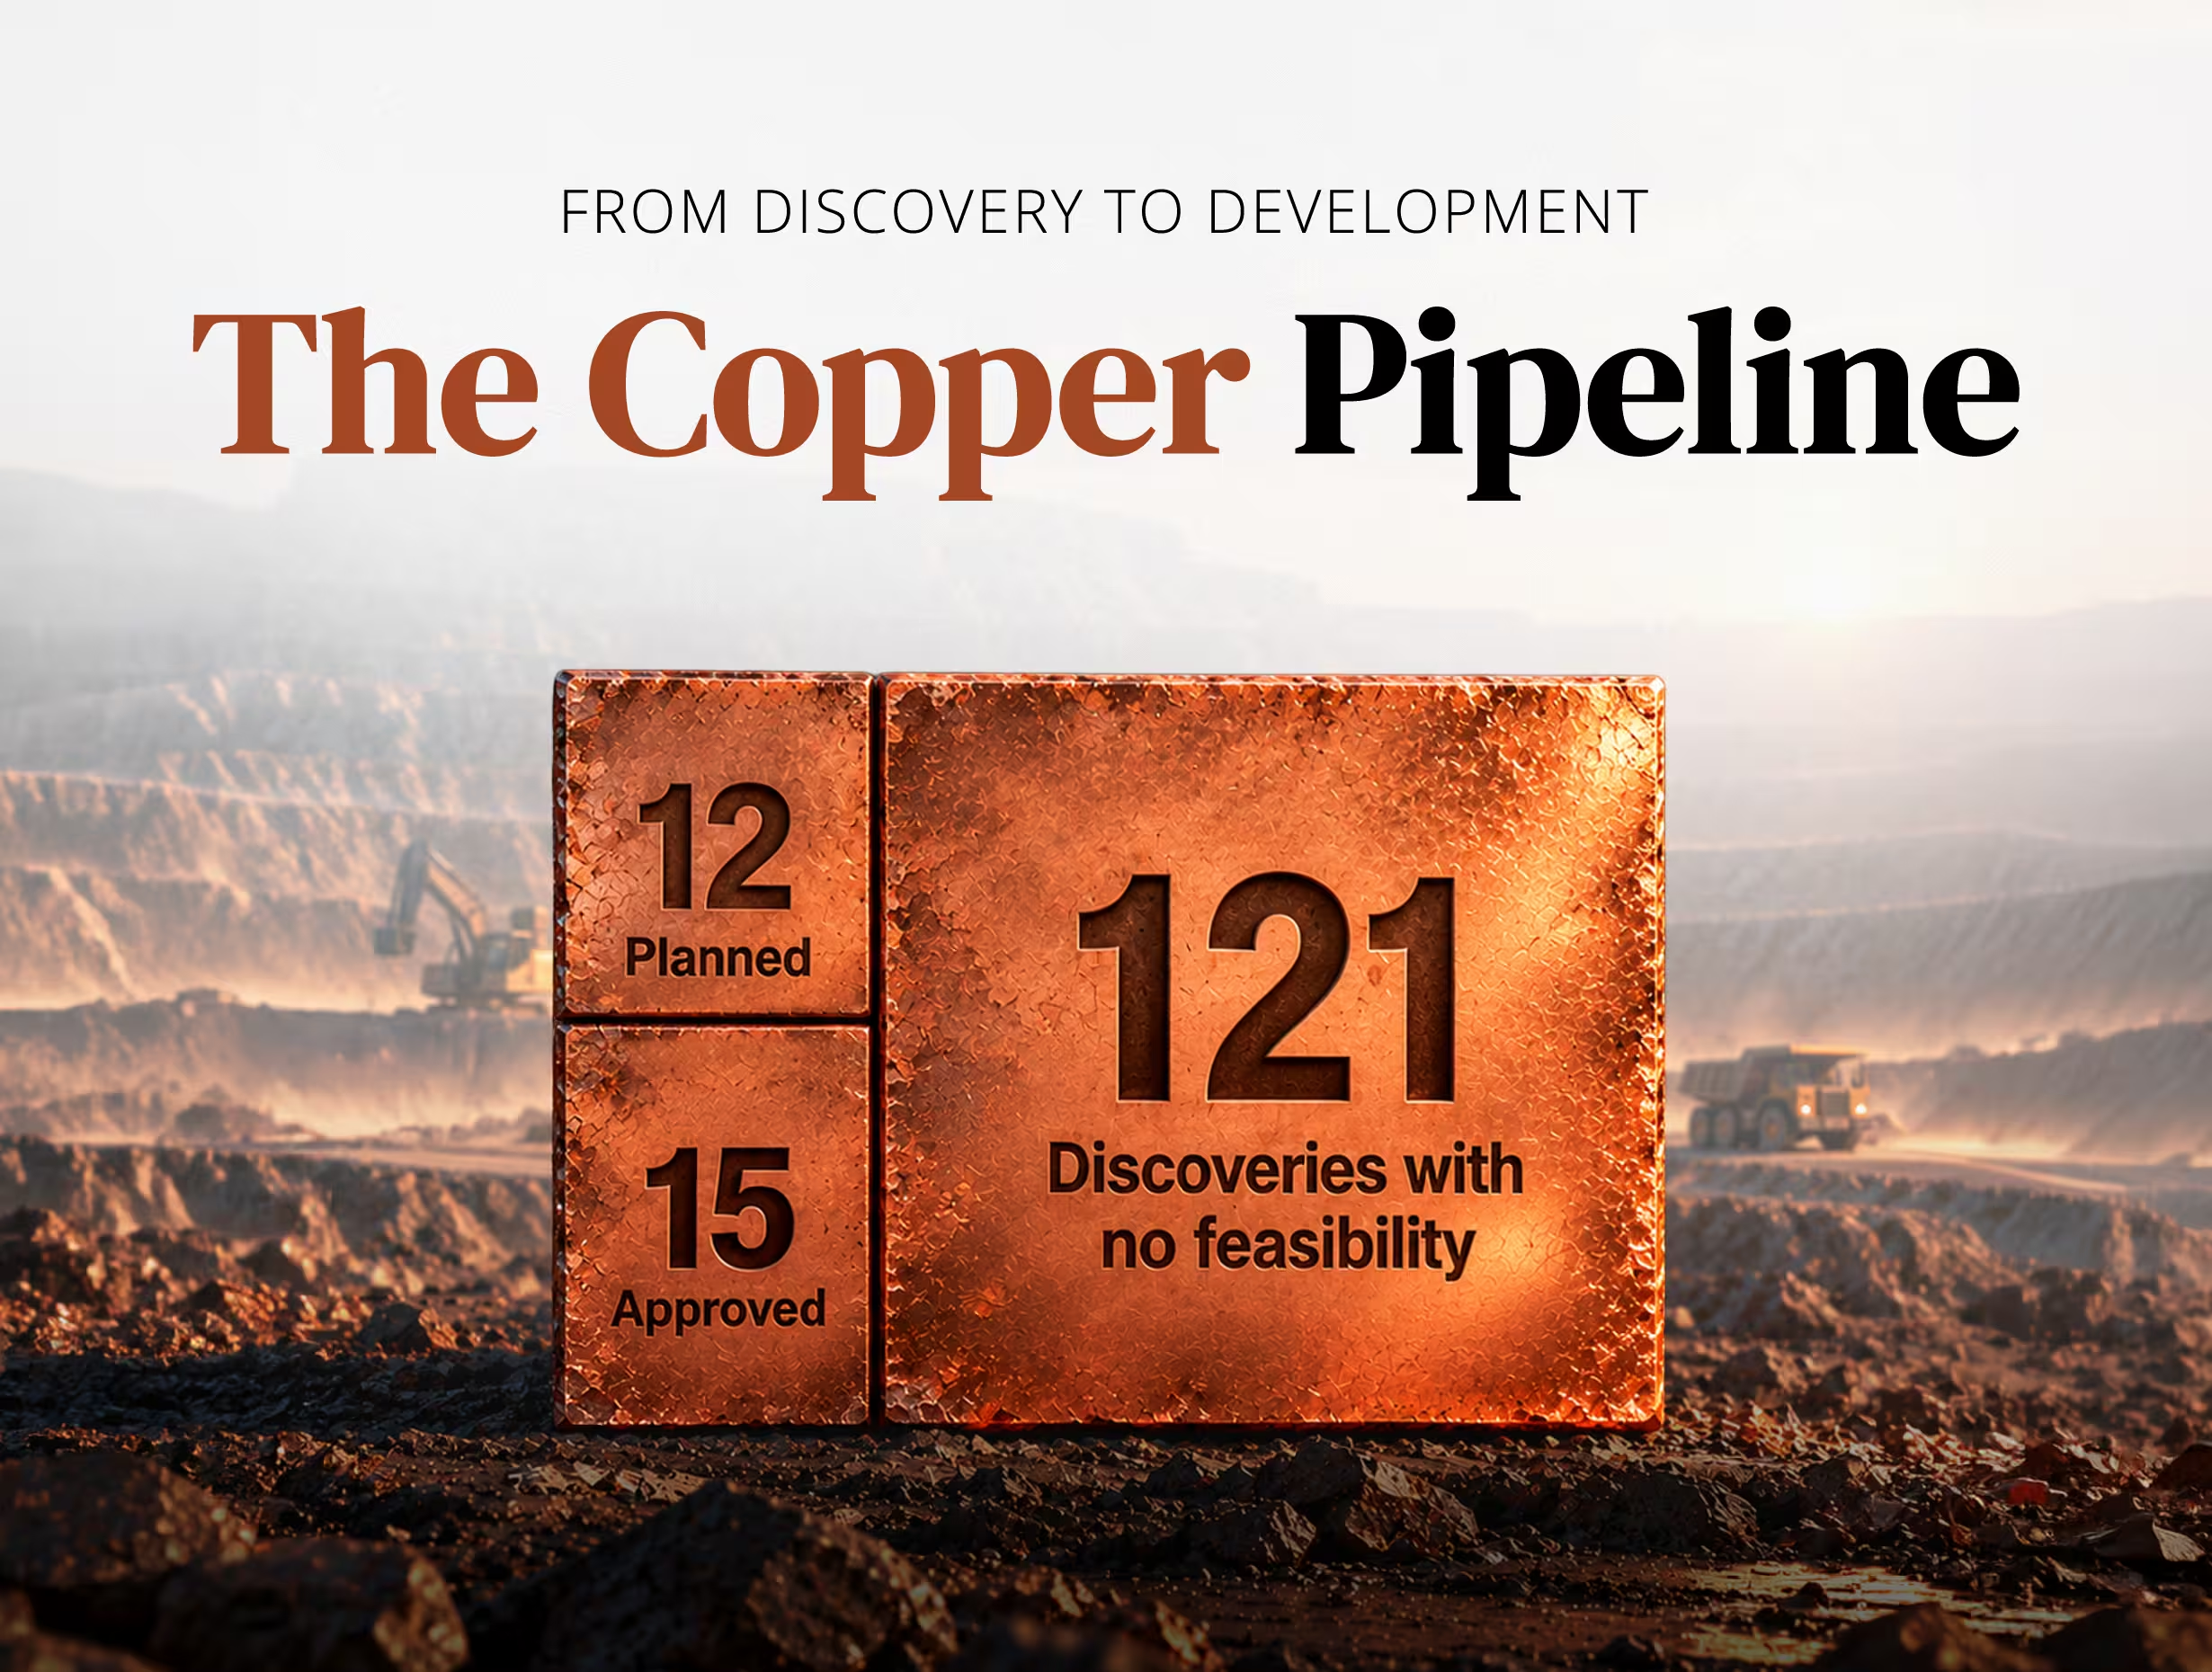
Most Major Copper Discoveries Since 1990 Are Still Not Mines.
In May 2025, a joint venture of Lundin Mining and BHP released a resource estimate for its Vicuña district in the Andes, which S&P Global ranked as home to the largest greenfield copper discovery in 30 years. Per the same resource statement, the combined Filo del Sol and Josemaria deposits hold 13 million tonnes of contained copper in measured and indicated resources.
China Holds 56% of the Capacity at the World's 21 Largest Copper Refineries
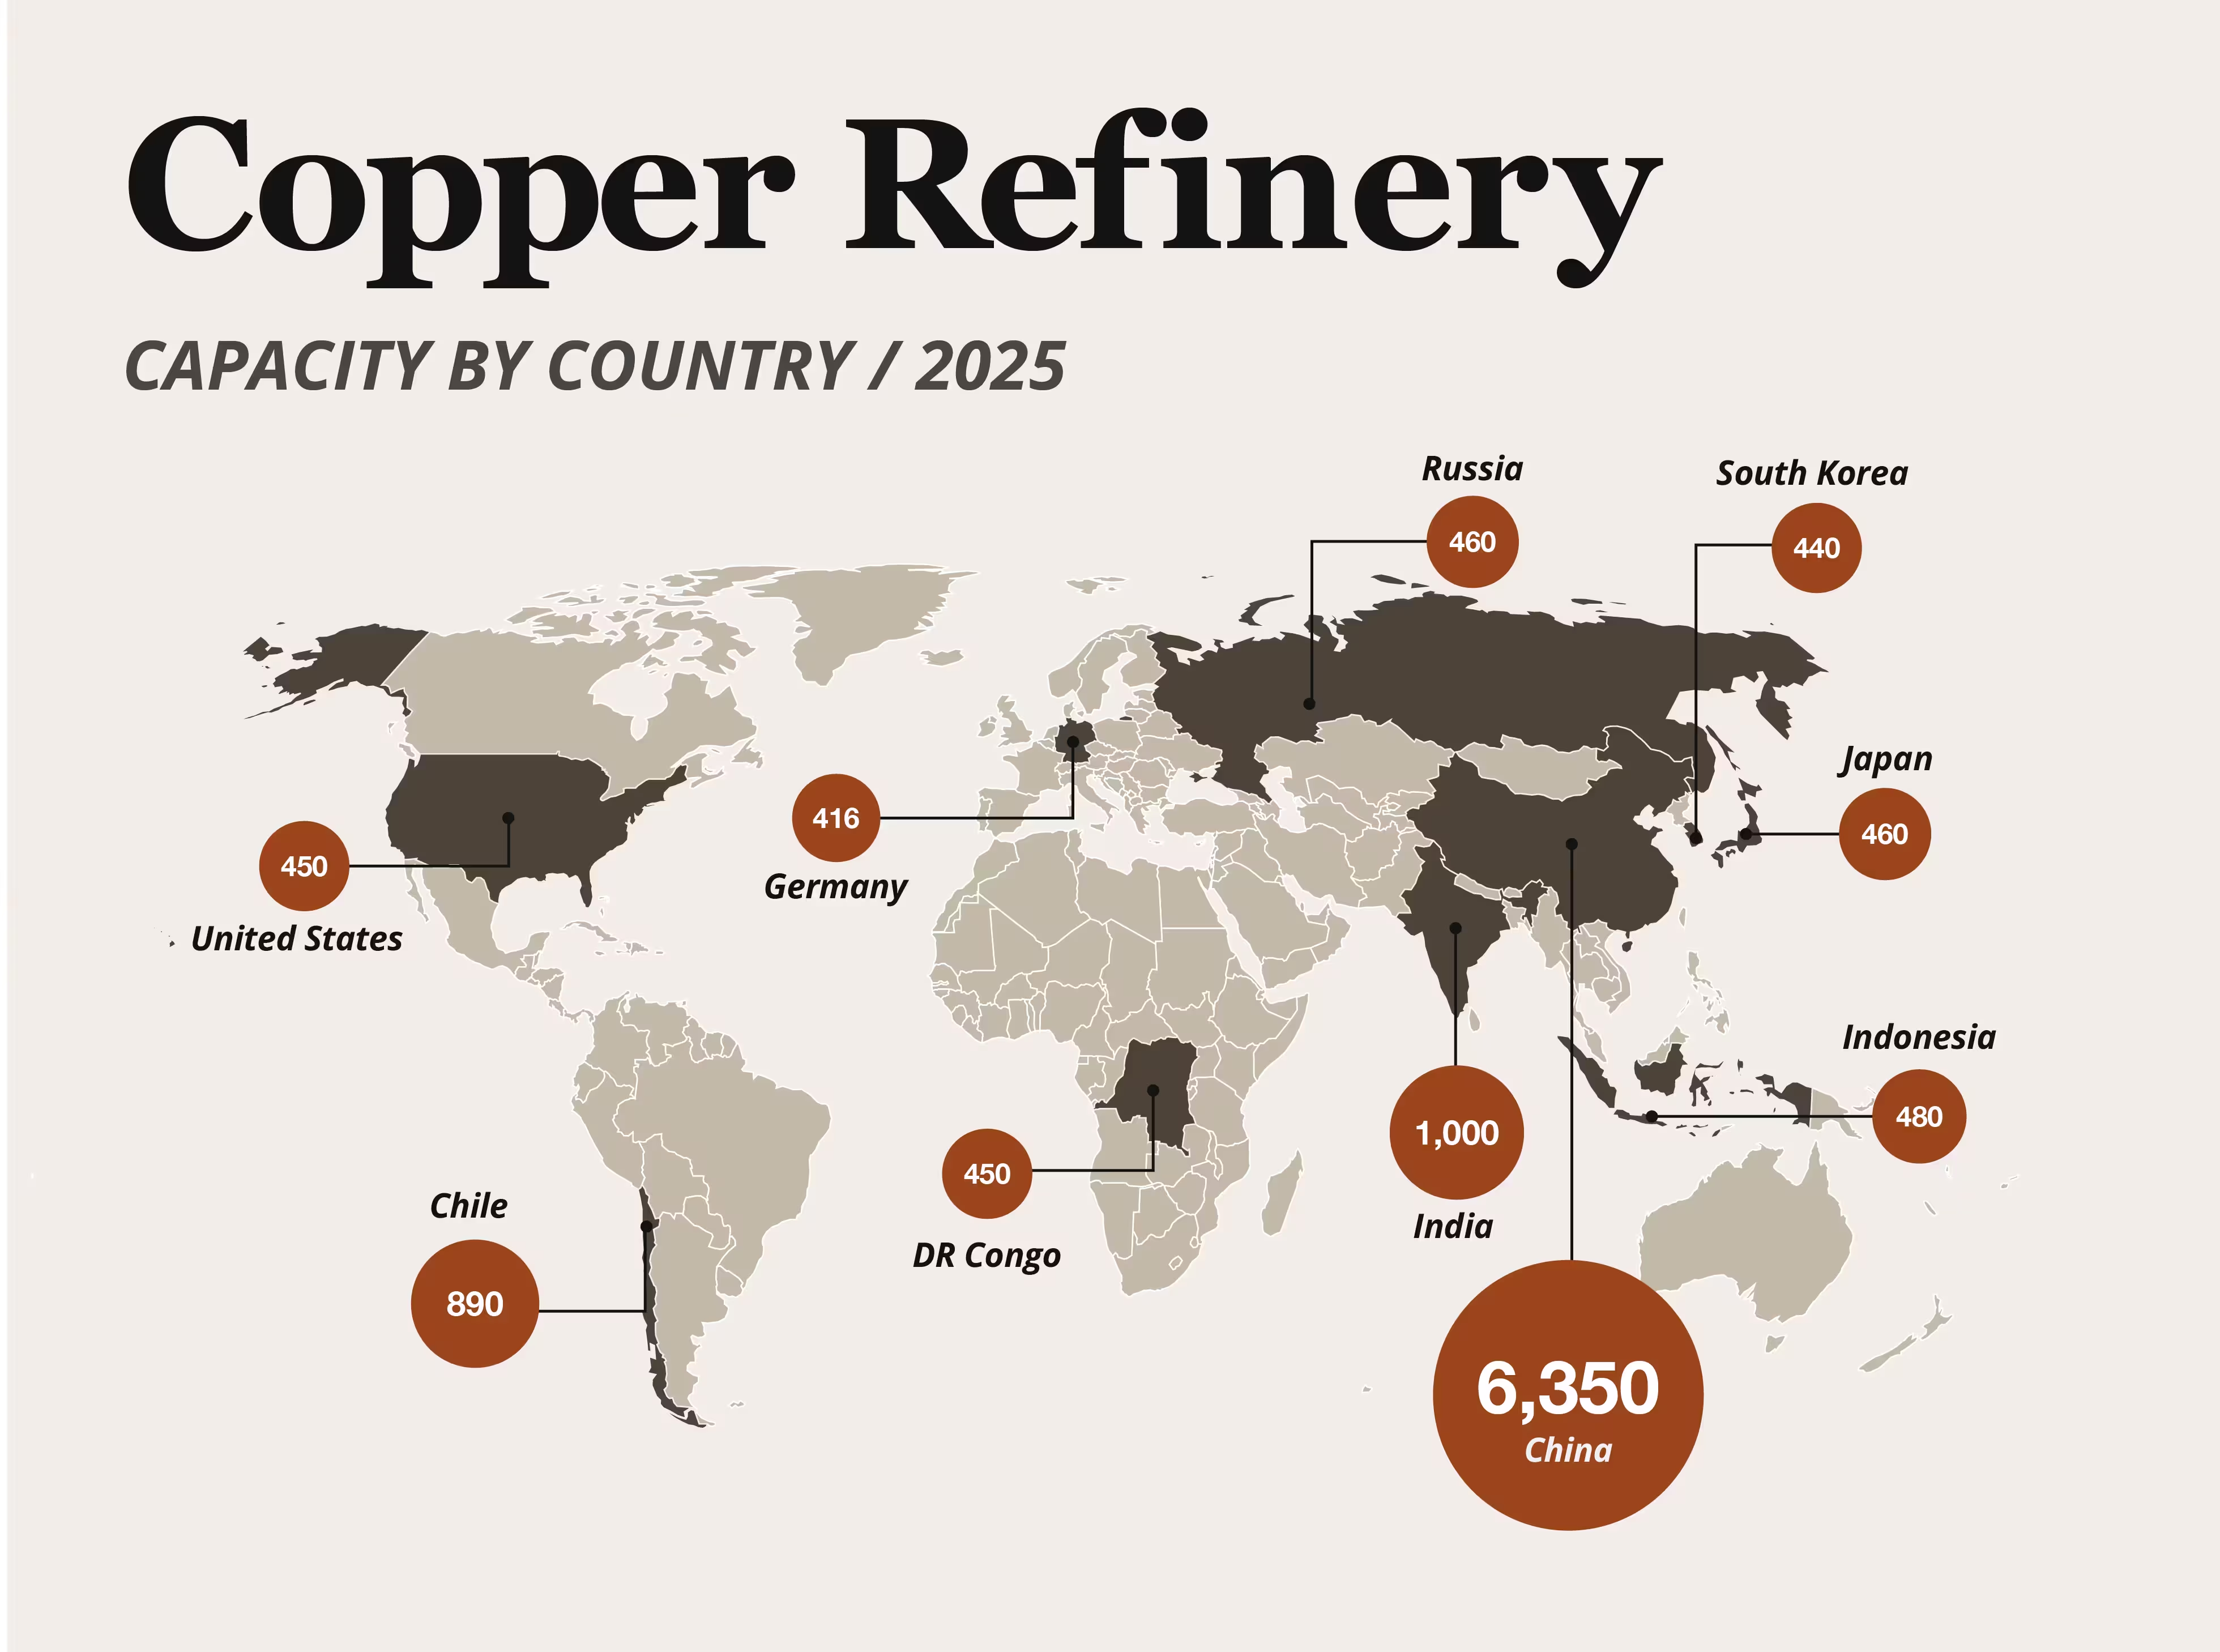
China Holds 56% of the Capacity at the World's 21 Largest Copper Refineries
Indonesia's circle on the map above stands for a single plant: the Manyar refinery in East Java, operated by PT Freeport Indonesia, with 480,000 tonnes a year of capacity, according to the International Copper Study Group. It has been shut since the fourth quarter of 2025, after a mudflow at the Grasberg mine cut off its concentrate supply, and is due to restart this month at below 30% of capacity.
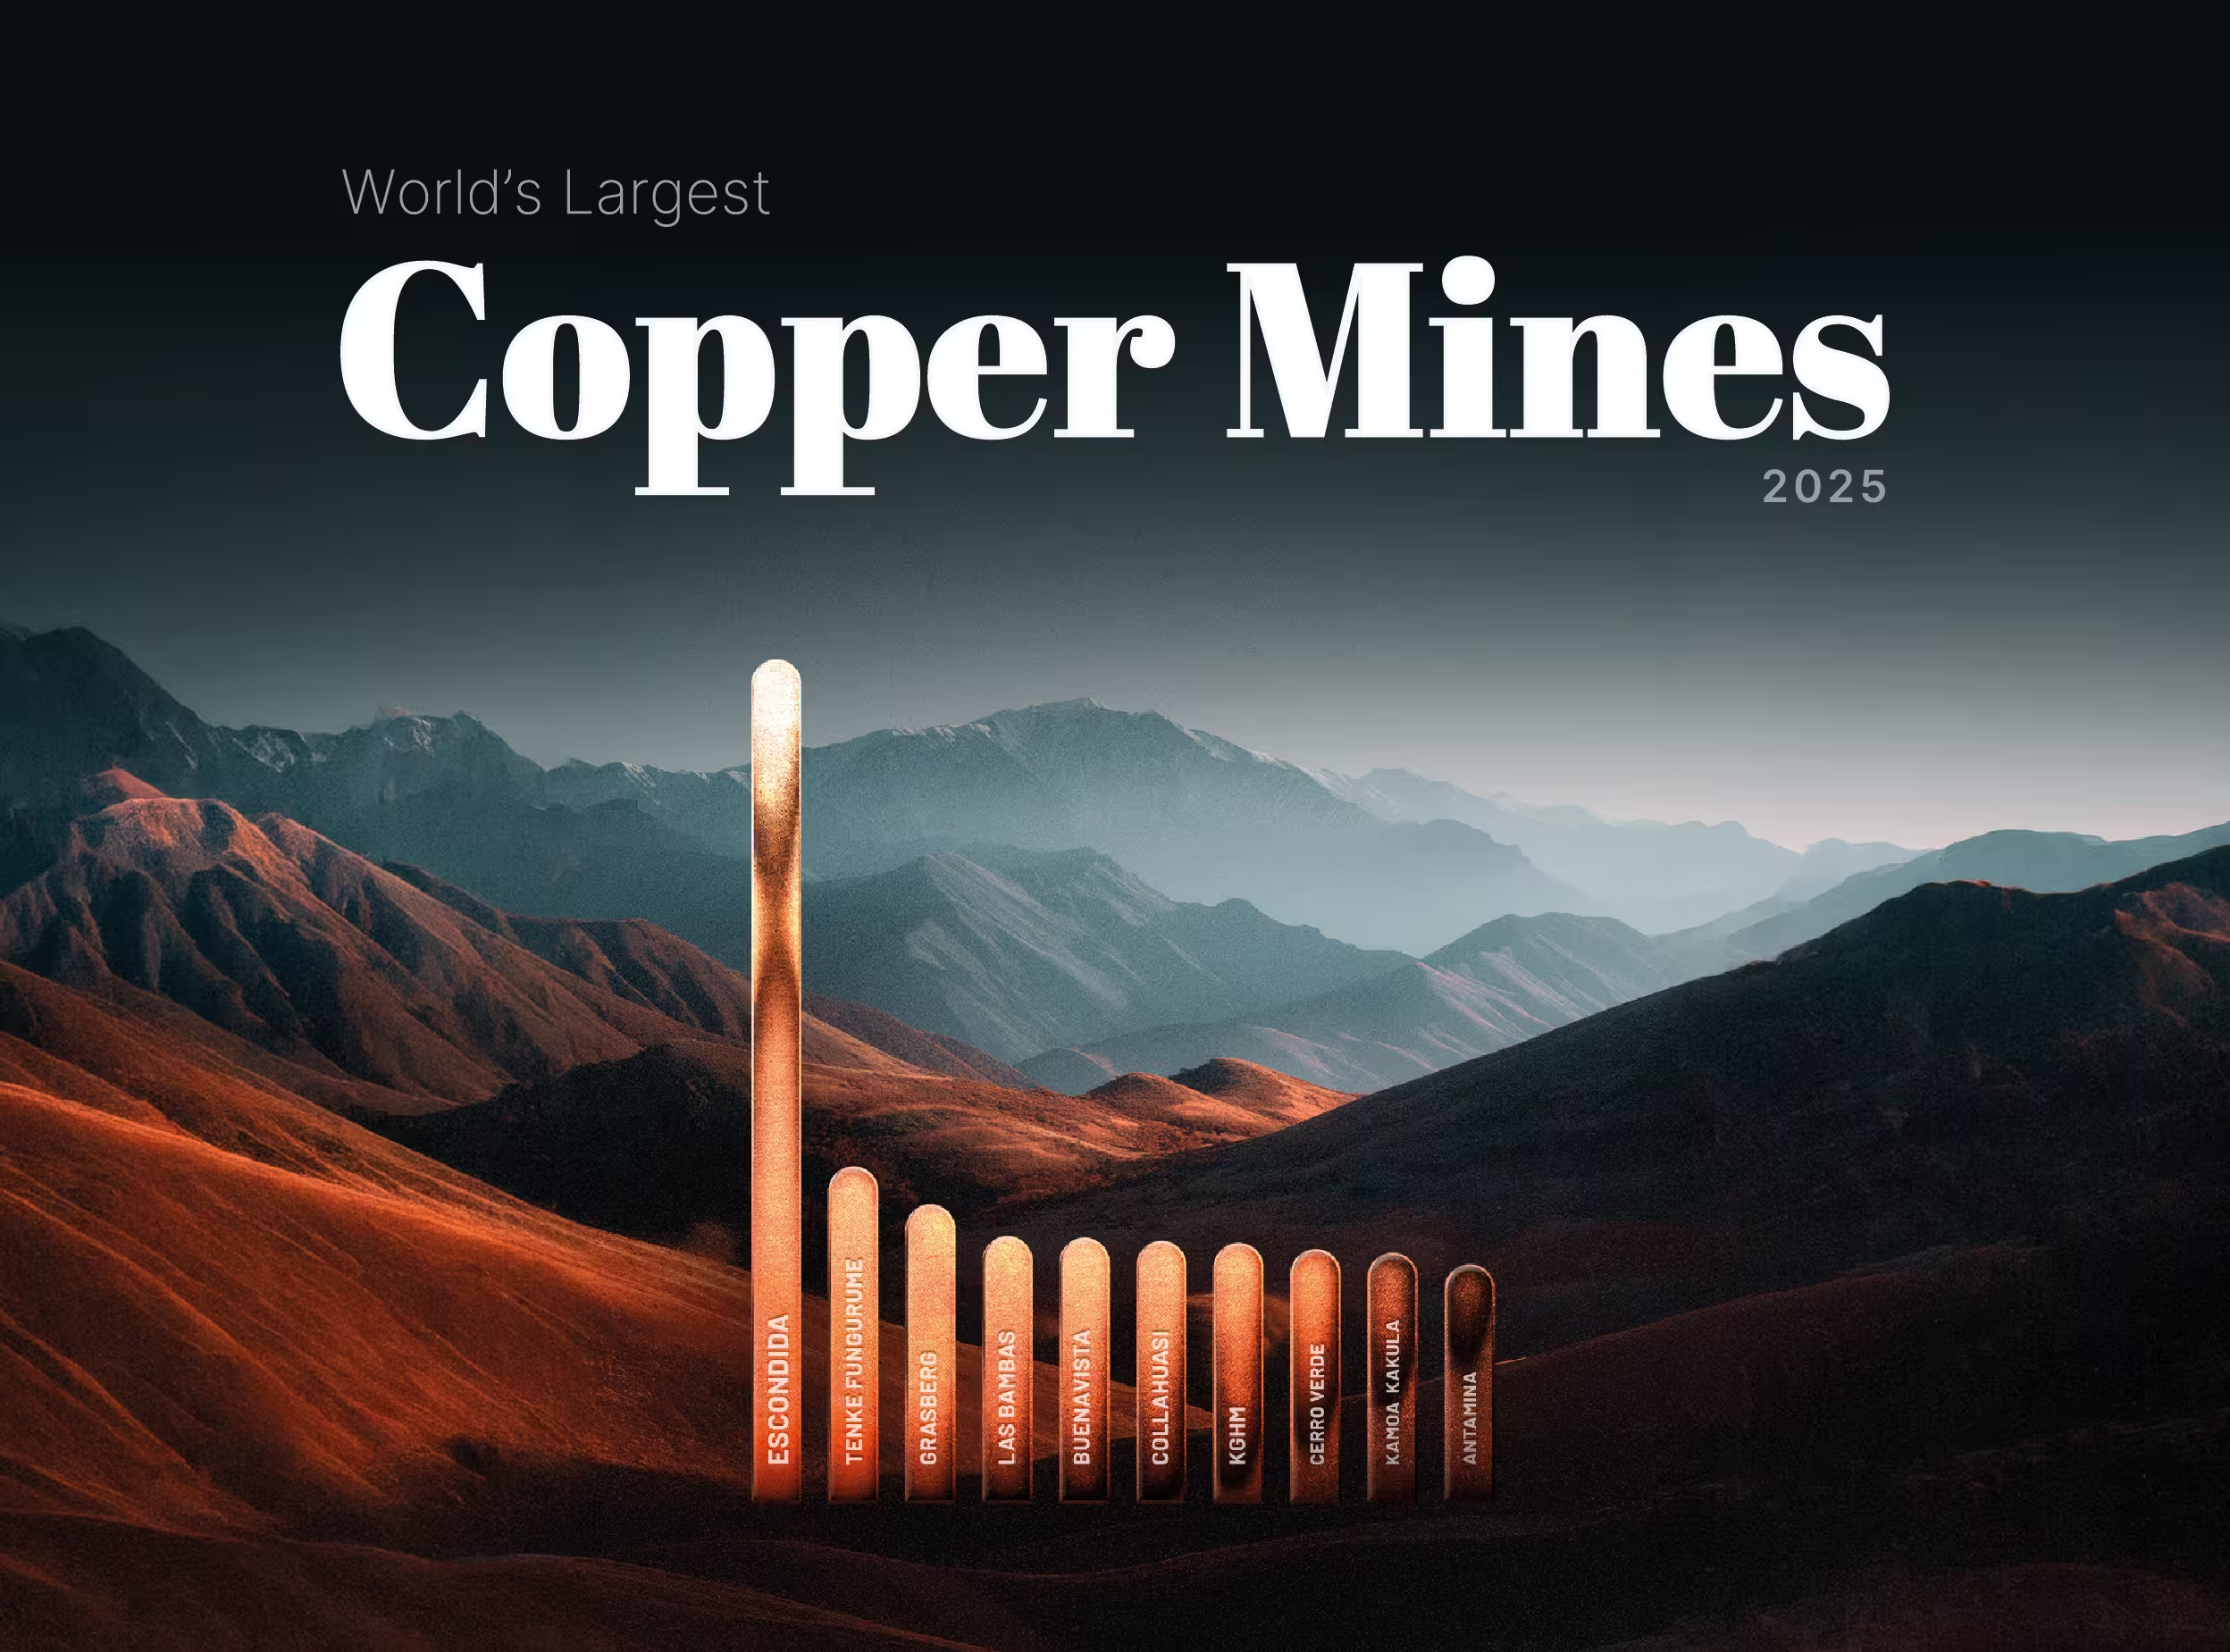
Ranked: The World's Largest Copper Mines (2025)
Ranked: The World's Largest Copper Mines (2025)
Copper has spent 2026 setting records, touching an intraday COMEX high of $6.71 per pound on May 13 amid AI-driven demand and supply shocks, against a backdrop where the ICSG now forecasts a 150,000-tonne deficit for 2026. In a market this tight, where the deficit thesis turns on lost tonnes, the question of where the world's copper actually comes from carries unusual weight.