Precious Metals
November 29, 2024
2 min
Precious Metals


In a recent tweet, Elon Musk declared that solar power will dominate future power generation. While ambitious, his statement aligns with compelling trends in solar capacity growth. This article delves into the data behind Musk’s vision, the transformative role of solar in the global energy transition, and the significant implications for the silver market.
"Solar power will be the vast majority of power generation in the future"
- Elon Musk, Nov 12, 2024
Solar's Exponential Growth
According to the International Energy Agency (IEA), solar photovoltaic (PV) capacity has experienced explosive growth in recent years. From 2016 to 2023, solar capacity additions increased from 83.3 GW to 405.5 GW, with projections for 2024 reaching 467 GW and an impressive 672.6 GW by 2028. In 2023 alone, solar PV accounted for three-quarters of renewable capacity additions worldwide, underscoring its pivotal role in reducing global reliance on fossil fuels.
Utility-scale solar PV has become the most cost-effective option for new electricity generation in most countries, even amid rising commodity prices. Meanwhile, distributed solar PV—such as rooftop systems on homes and businesses—is set for rapid expansion, driven by high retail electricity prices and supportive policies from governments seeking to meet ambitious climate targets.
The Silver Connection
The adoption of solar PV technologies has a direct and significant impact on the demand for silver, an essential material in solar panels. Between 2015 and 2024F, silver demand for photovoltaics has soared by an astonishing 289% (source). As the global solar market continues to scale, silver demand is expected to rise even further, creating opportunities for growth but also challenges for supply chains reliant on this critical metal.
The Road Ahead
Solar power is not only a cornerstone of the clean energy transition but also a key driver of technological and economic transformation. The rapid expansion of solar PV capacity—supported by declining costs, innovation, and strong policy frameworks—validates Elon Musk’s vision of a solar-dominated future.
However, achieving this vision will require sustained investment and strategic planning to overcome challenges such as supply chain disruptions and material constraints, particularly for silver. Continued progress will ensure that solar power remains a dominant force in energy generation, capable of meeting growing global demand sustainably.
With solar PV poised to set new records year after year, the future of energy looks brighter than ever—and silver will play a pivotal role in this transformation.
Silver PV demand data from World Silver Survey 2024. Solar PV data from IEA. This is a work derived by Miningvisuals from IEA material and Miningvisuals is solely liable and responsible for this derived work. The derived work is not endorsed by the IEA in any manner. The information presented here may contain inaccuracies and is subject to rounding. This is not investment advice.


Explore More
View All

Seven Events That Shaped a Century of Gold Prices
Seven Events That Shaped a Century of Gold Prices
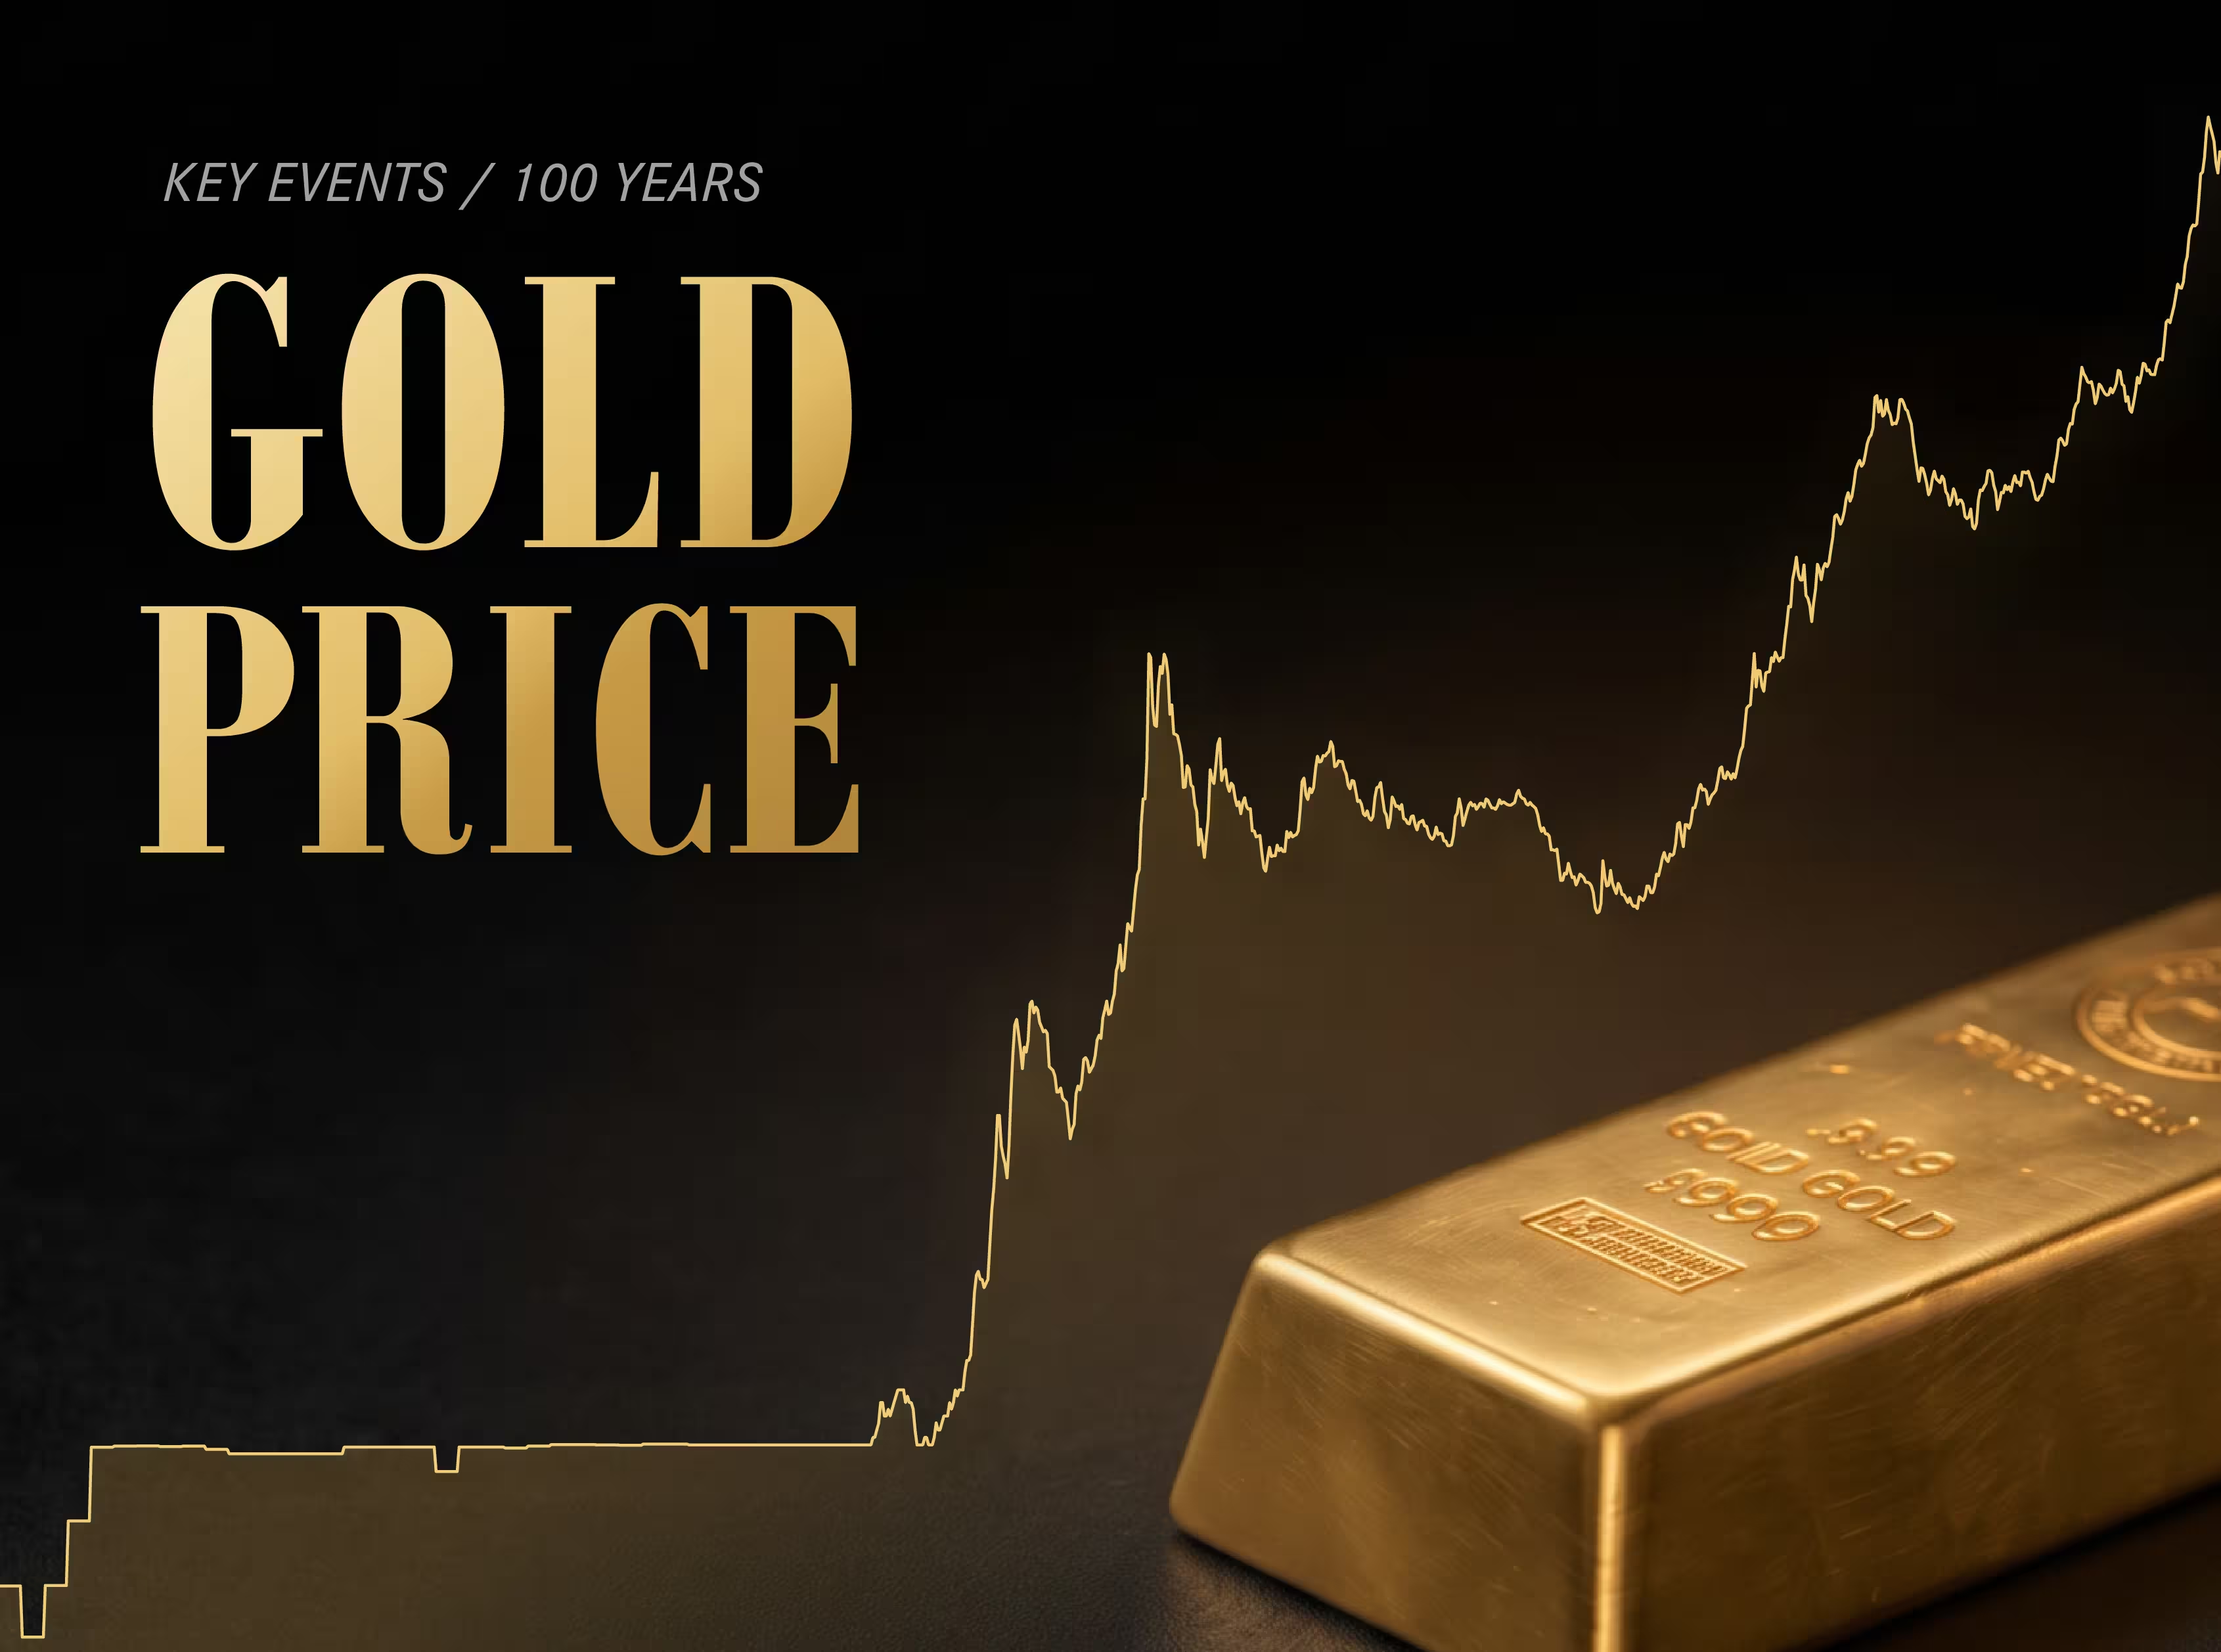
In 1934, the US government set the price of gold at $35 an ounce. In September 2026, the market price averaged $4,319. Measured in today's money, gold has done more than keep up with rising prices. An ounce is now worth almost five times what it was when the price was set in 1934, and more than at the famous 1980 peak. For the companies that mine it, that has meant record margins.

The World's 20 Largest Primary Silver Mines by 2025 Output
The World's 20 Largest Primary Silver Mines by 2025 Output
The largest silver producer among the world's primary silver mines in 2025 sat not in Mexico but in southwestern Bolivia. San Cristóbal, a large open-pit silver-zinc-lead mine run by Minera San Cristóbal, produced 17.6 million ounces of silver, narrowly ahead of Mexico's Juanicipio at the same rounded figure, in new Metals Focus data on the 20 largest primary silver mines. These are the operations where silver is a defining product rather than an incidental byproduct of lead, zinc and gold. The list runs from centuries-old mines in Mexico's silver belt to remote sites in the Andes, the Australian outback and the Alaskan wilderness. Eight of the 20 sit in Mexico, together about 44% of the total, while the rest are spread across the Americas, Asia, Africa and Australia.
Central Banks Have Been Net Gold Buyers Since 2010, After Two Decades of Net Selling
Central Banks Have Been Net Gold Buyers Since 2010, After Two Decades of Net Selling
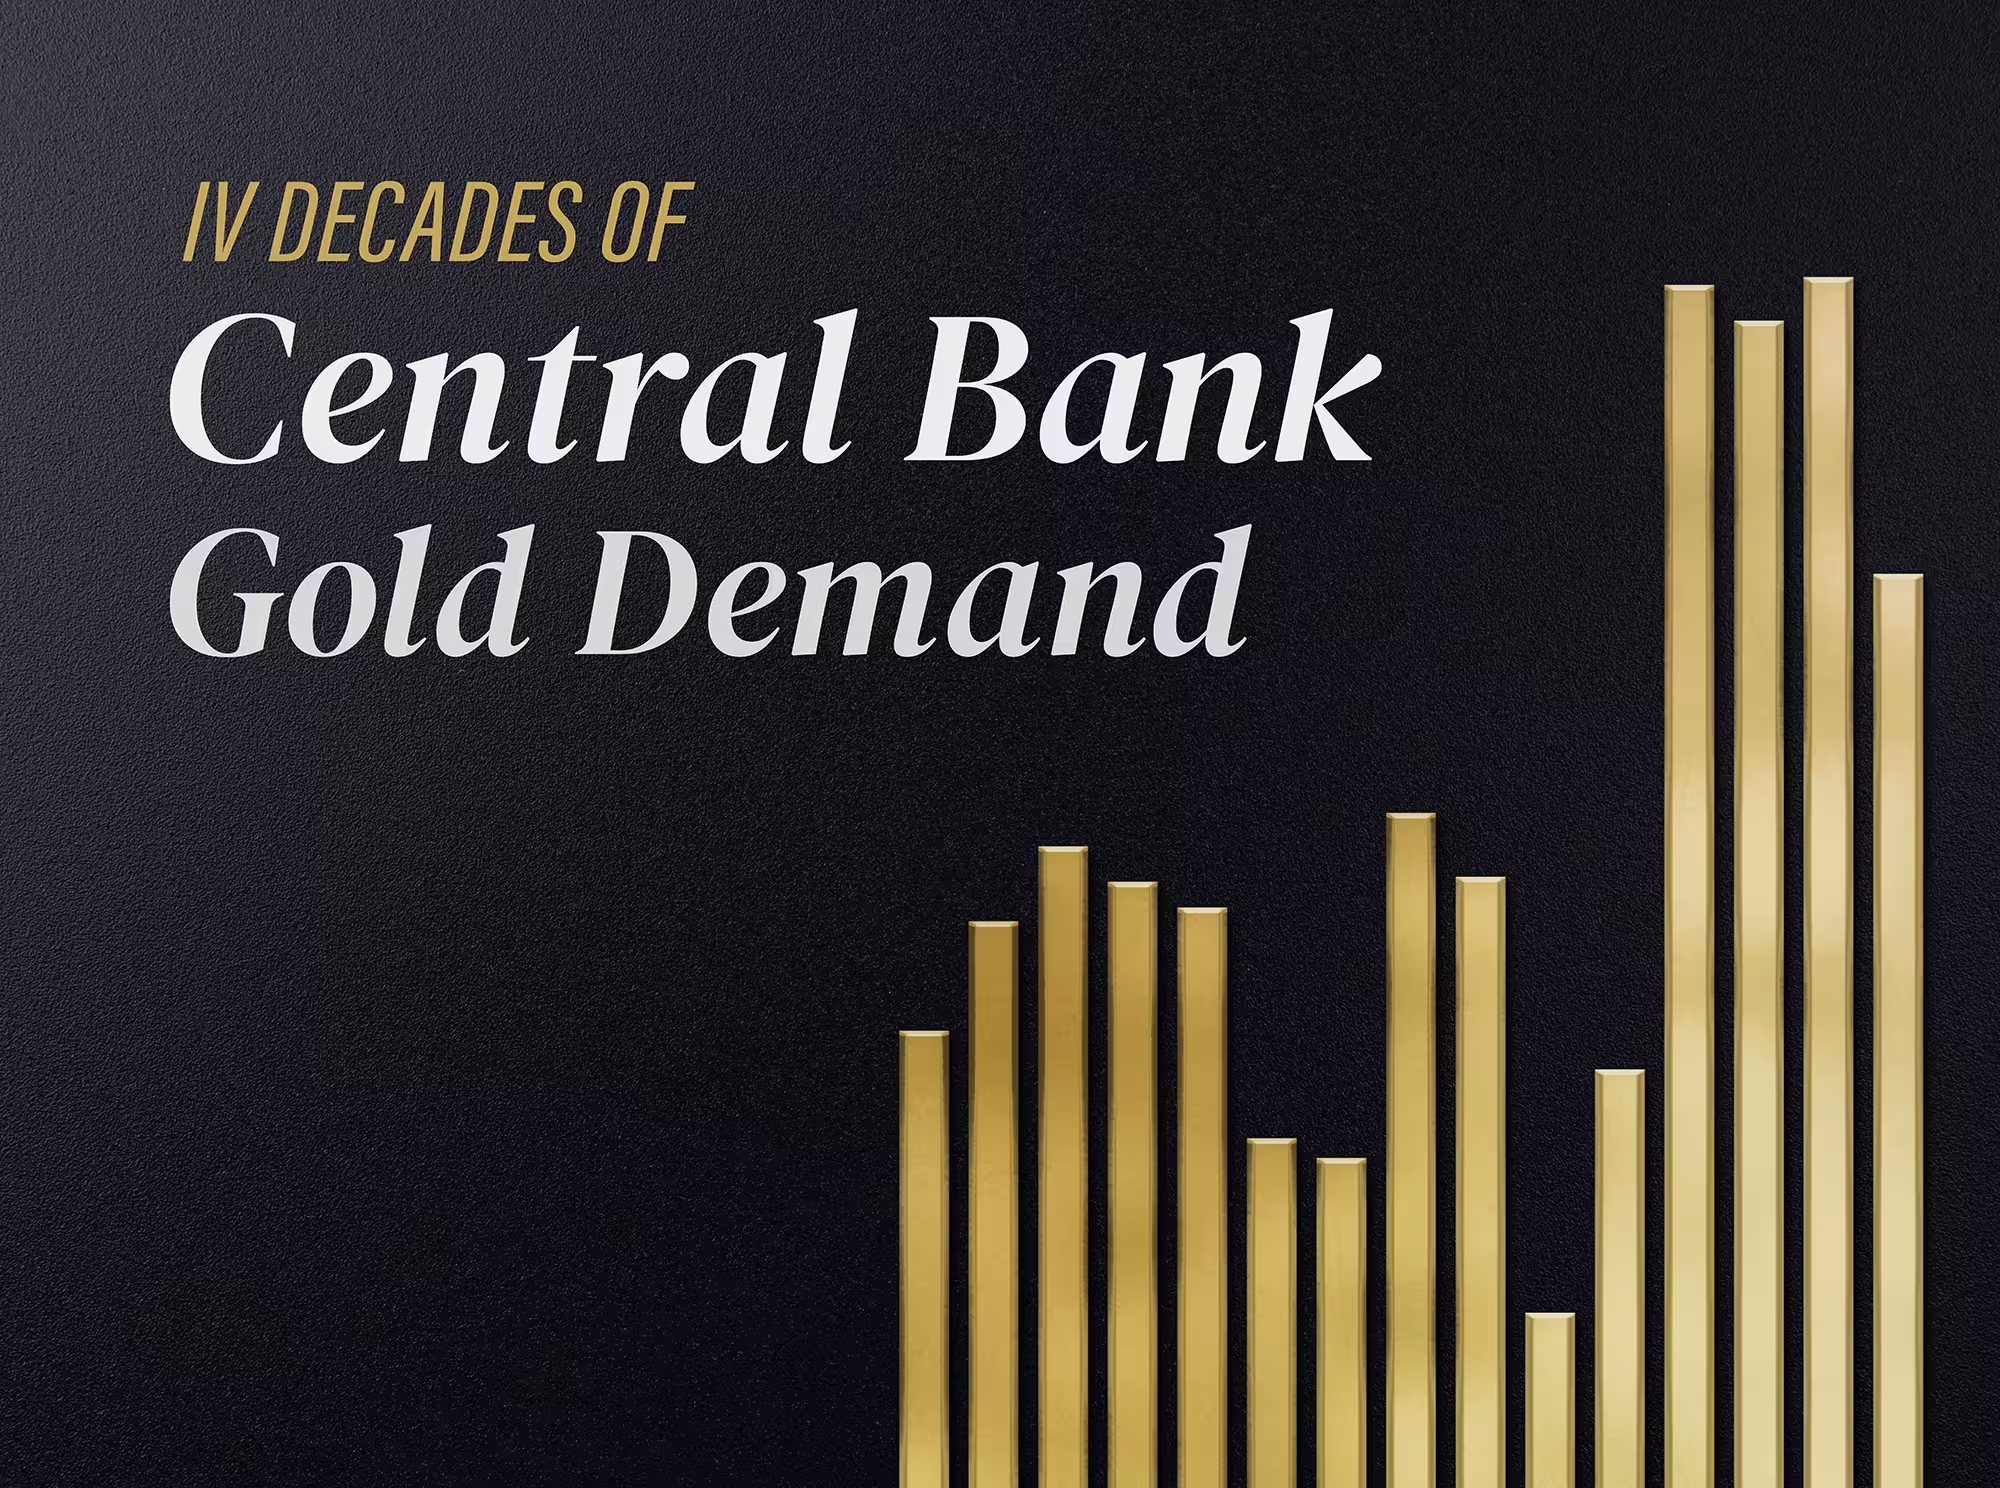
Central banks bought more gold between April and June 2026 than in any second quarter on record, according to a World Gold Council report published on July 30. That keeps them net buyers this year, as they have been every year since 2010. Underneath, the picture is changing. Russia and Türkiye, both big buyers in the past, have been selling.

Gold Mines in West Africa: Two Billion Years in the Making
Gold Mines in West Africa: Two Billion Years in the Making
The nine West African countries with significant reported output produced about 15% of the world's mined gold in 2025, according to Metals Focus and World Gold Council data. Almost every mine on the map above was built in the past 25 years, and four more reached production in the last eighteen months: Lafigué in Côte d'Ivoire in June 2024, Kiaka in Burkina Faso in June 2025, Ahafo North in Ghana in October 2025 and Kiniero in Guinea in December 2025.