Copper
November 5, 2025
2 min
Copper


Copper is an essential metal for modern civilization. While often working behind the scenes, it is a fundamental component in everything from household wiring to advanced electronics. An analysis of its production over the last century reveals a compelling story. As the global population has grown, so has the demand for copper.
More recently, however, its production trajectory has accelerated, reflecting a growing global need for connectivity, advanced technology, and new forms of energy. As the book "RED METAL, BLUE PLANET" illustrates, key moments in recent history have highlighted this growing demand.
The Industrial Baseline: A Parallel Growth
For much of the 20th century, copper's story was closely linked with basic industrial development. As global populations expanded and societies built out their infrastructure, the demand for copper increased at a similar, steady pace. This period showed a parallel growth between population and copper use. Homes needed wiring and pipes, cars required electrical systems, and factories used copper components.
The Digital Accelerator: More Copper Per Person
A notable shift began in the mid-1960s, and then accelerated in the mid-1990s. The "Digital Revolution," with the widespread adoption of personal computers, the internet, and early mobile phones, created new and significant demands for copper.
This wasn't just about more people; it was about more copper per person. Each new electronic device and the data infrastructure to support it added to the global copper requirement. This trend was amplified by the "Rise of a New Consumer" in 1999. China's rapid industrialization and urbanization, in particular, drove substantial new demand for construction materials, electronics, and infrastructure, creating a strong "super-cycle" for copper that pushed production levels higher.
Supply Challenges
Unlike in the past—such as the 1990s “supply flood” from Chile—today’s supply growth faces tougher conditions. New high-grade deposits are harder to find, ore grades are declining, and mine development takes longer due to regulatory hurdles.
This growing imbalance highlights the need for greater efficiency, recycling, and continued investment in mining innovation.
Source: Data source: USGS - Mineral Commodity Summaries (2024); USGS - Historical Statistics for Mineral and Material Commodities (2023)


Explore More
View All


The World’s Largest Operating Copper Mines Alongside Reko Diq
The World’s Largest Operating Copper Mines Alongside Reko Diq
Ten operating mines in six countries each produced between 359,000 and 1.32 million tonnes of copper in 2025, according to Wood Mackenzie estimates. Reko Diq in Pakistan appears alongside them with a figure from Barrick’s feasibility study, which refers to planned future production. More than half of the ten mines’ combined output came from the five in South America. The 2025 figures also reflect a disrupted year at Grasberg in Indonesia, while Reko Diq’s number points to a project planned in two phases.
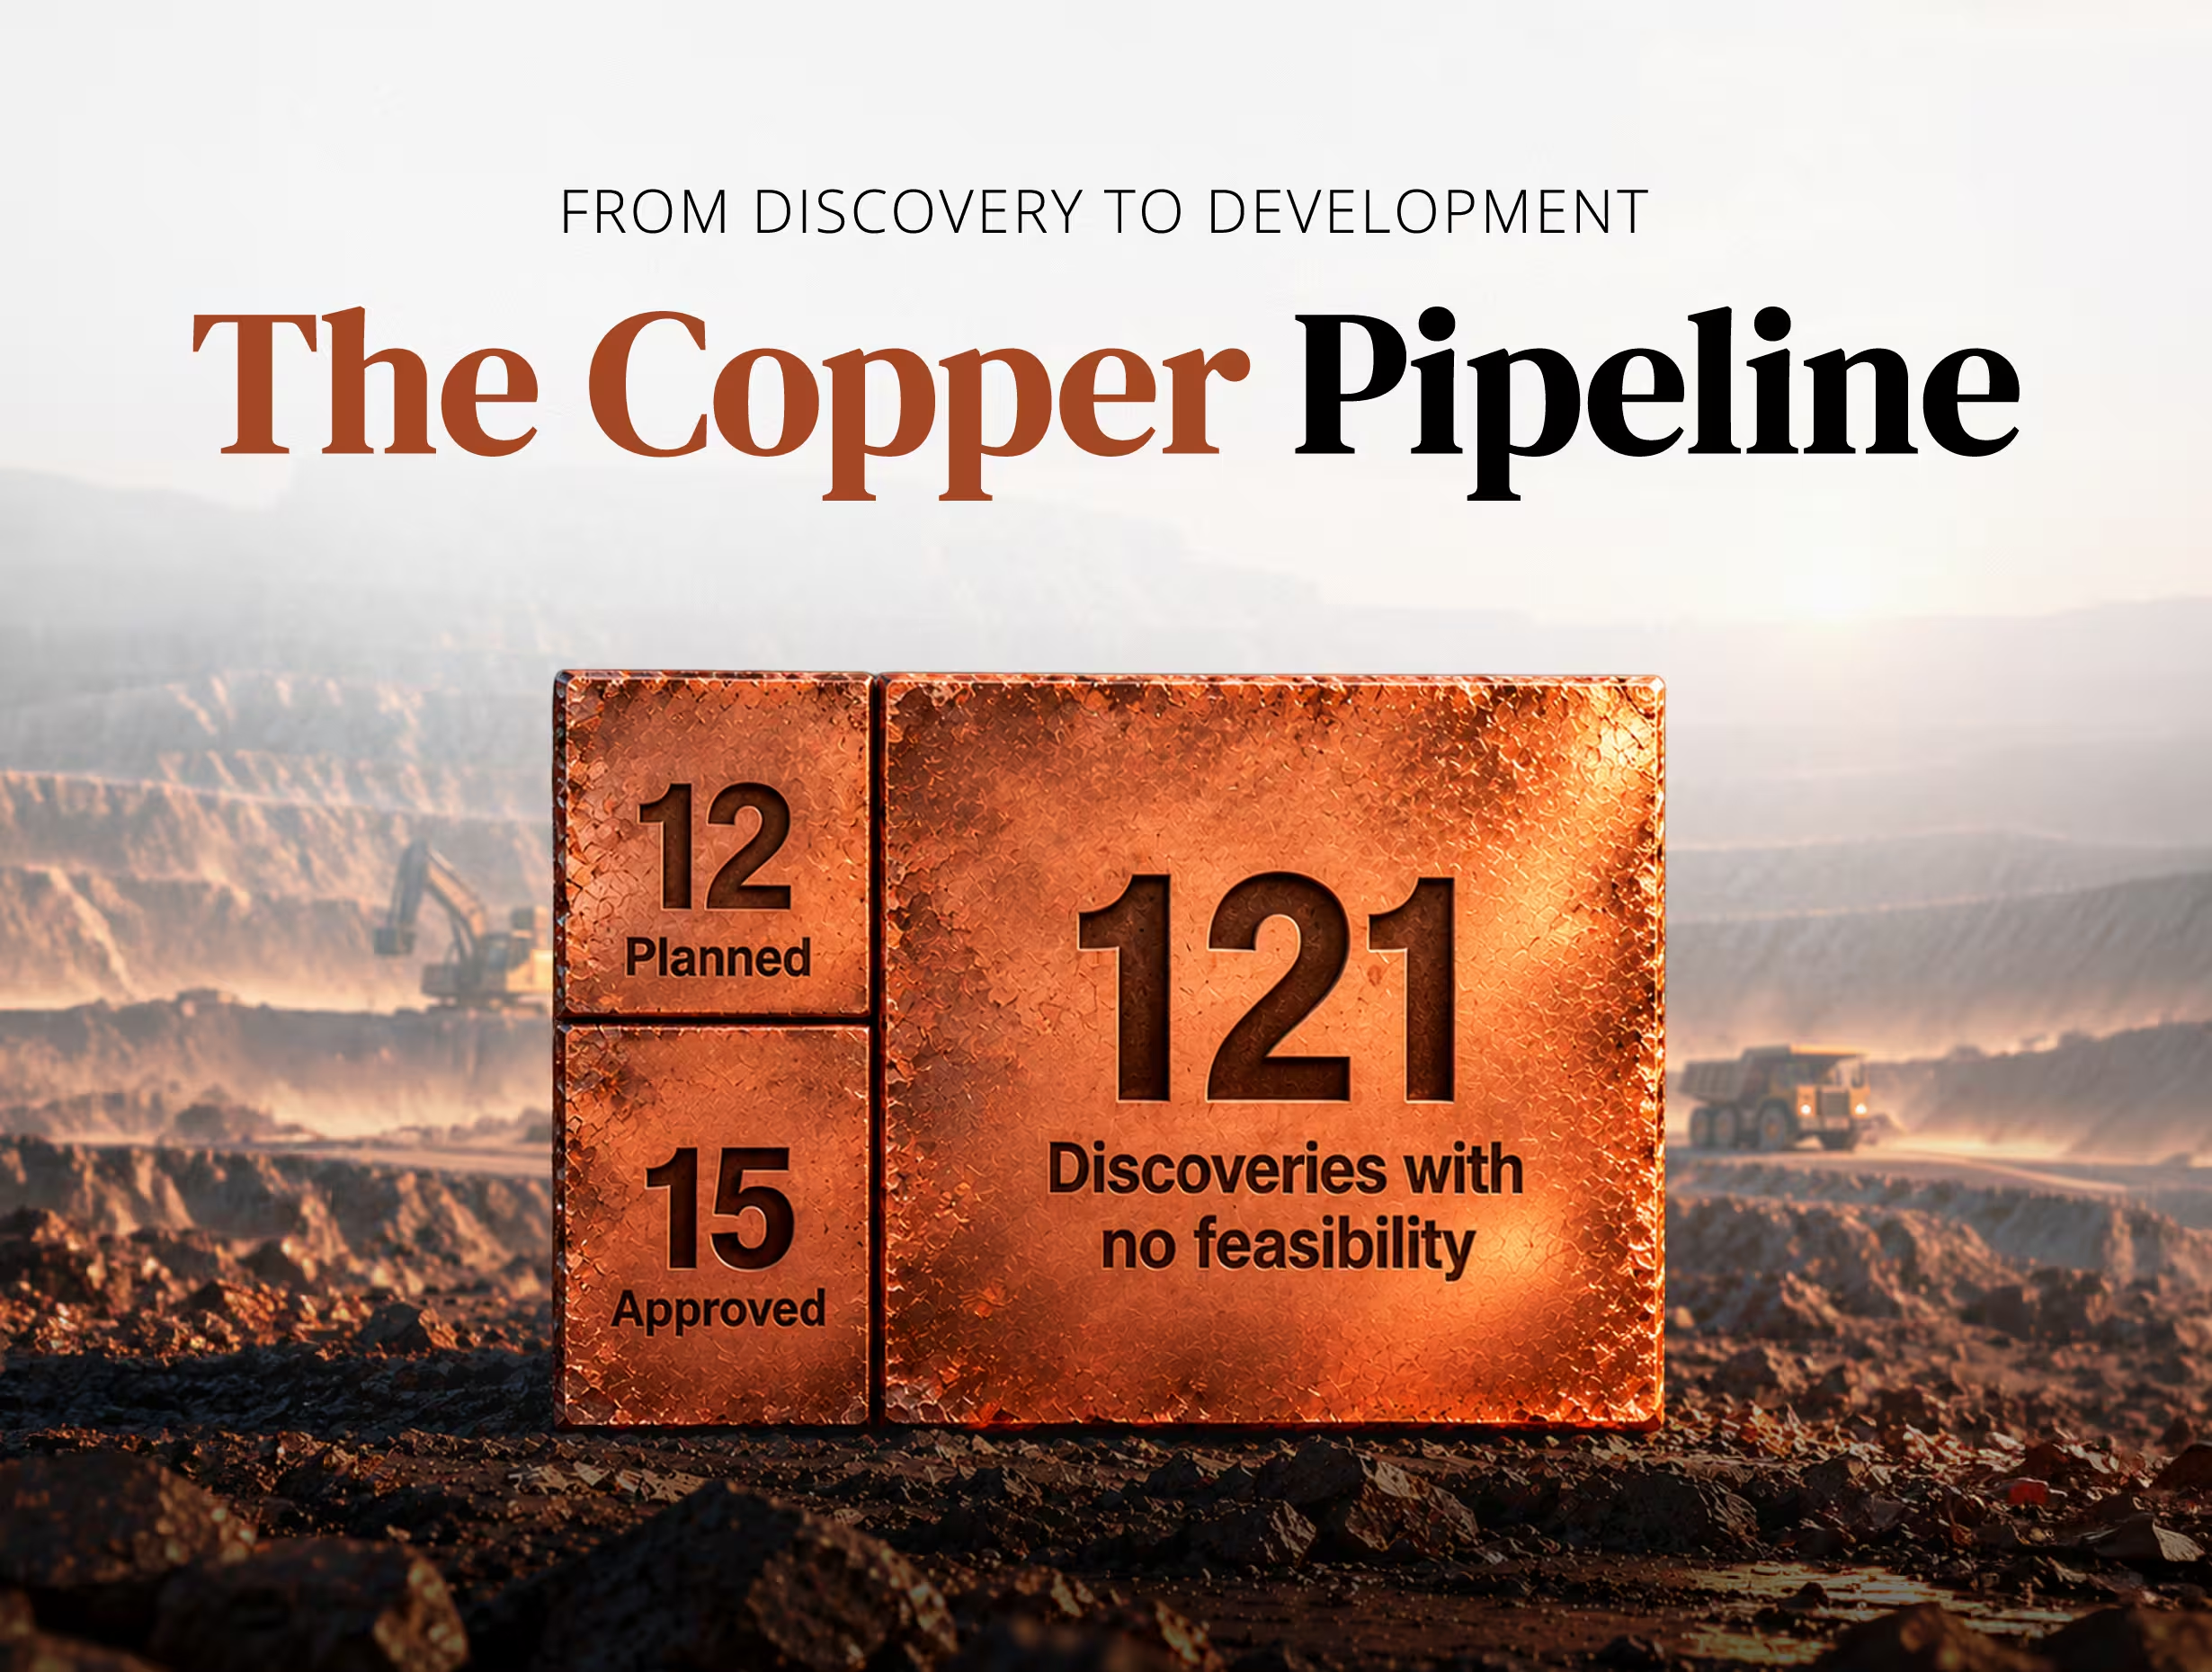
Most Major Copper Discoveries Since 1990 Are Still Not Mines.
Most Major Copper Discoveries Since 1990 Are Still Not Mines.
In May 2025, a joint venture of Lundin Mining and BHP released a resource estimate for its Vicuña district in the Andes, which S&P Global ranked as home to the largest greenfield copper discovery in 30 years. Per the same resource statement, the combined Filo del Sol and Josemaria deposits hold 13 million tonnes of contained copper in measured and indicated resources.
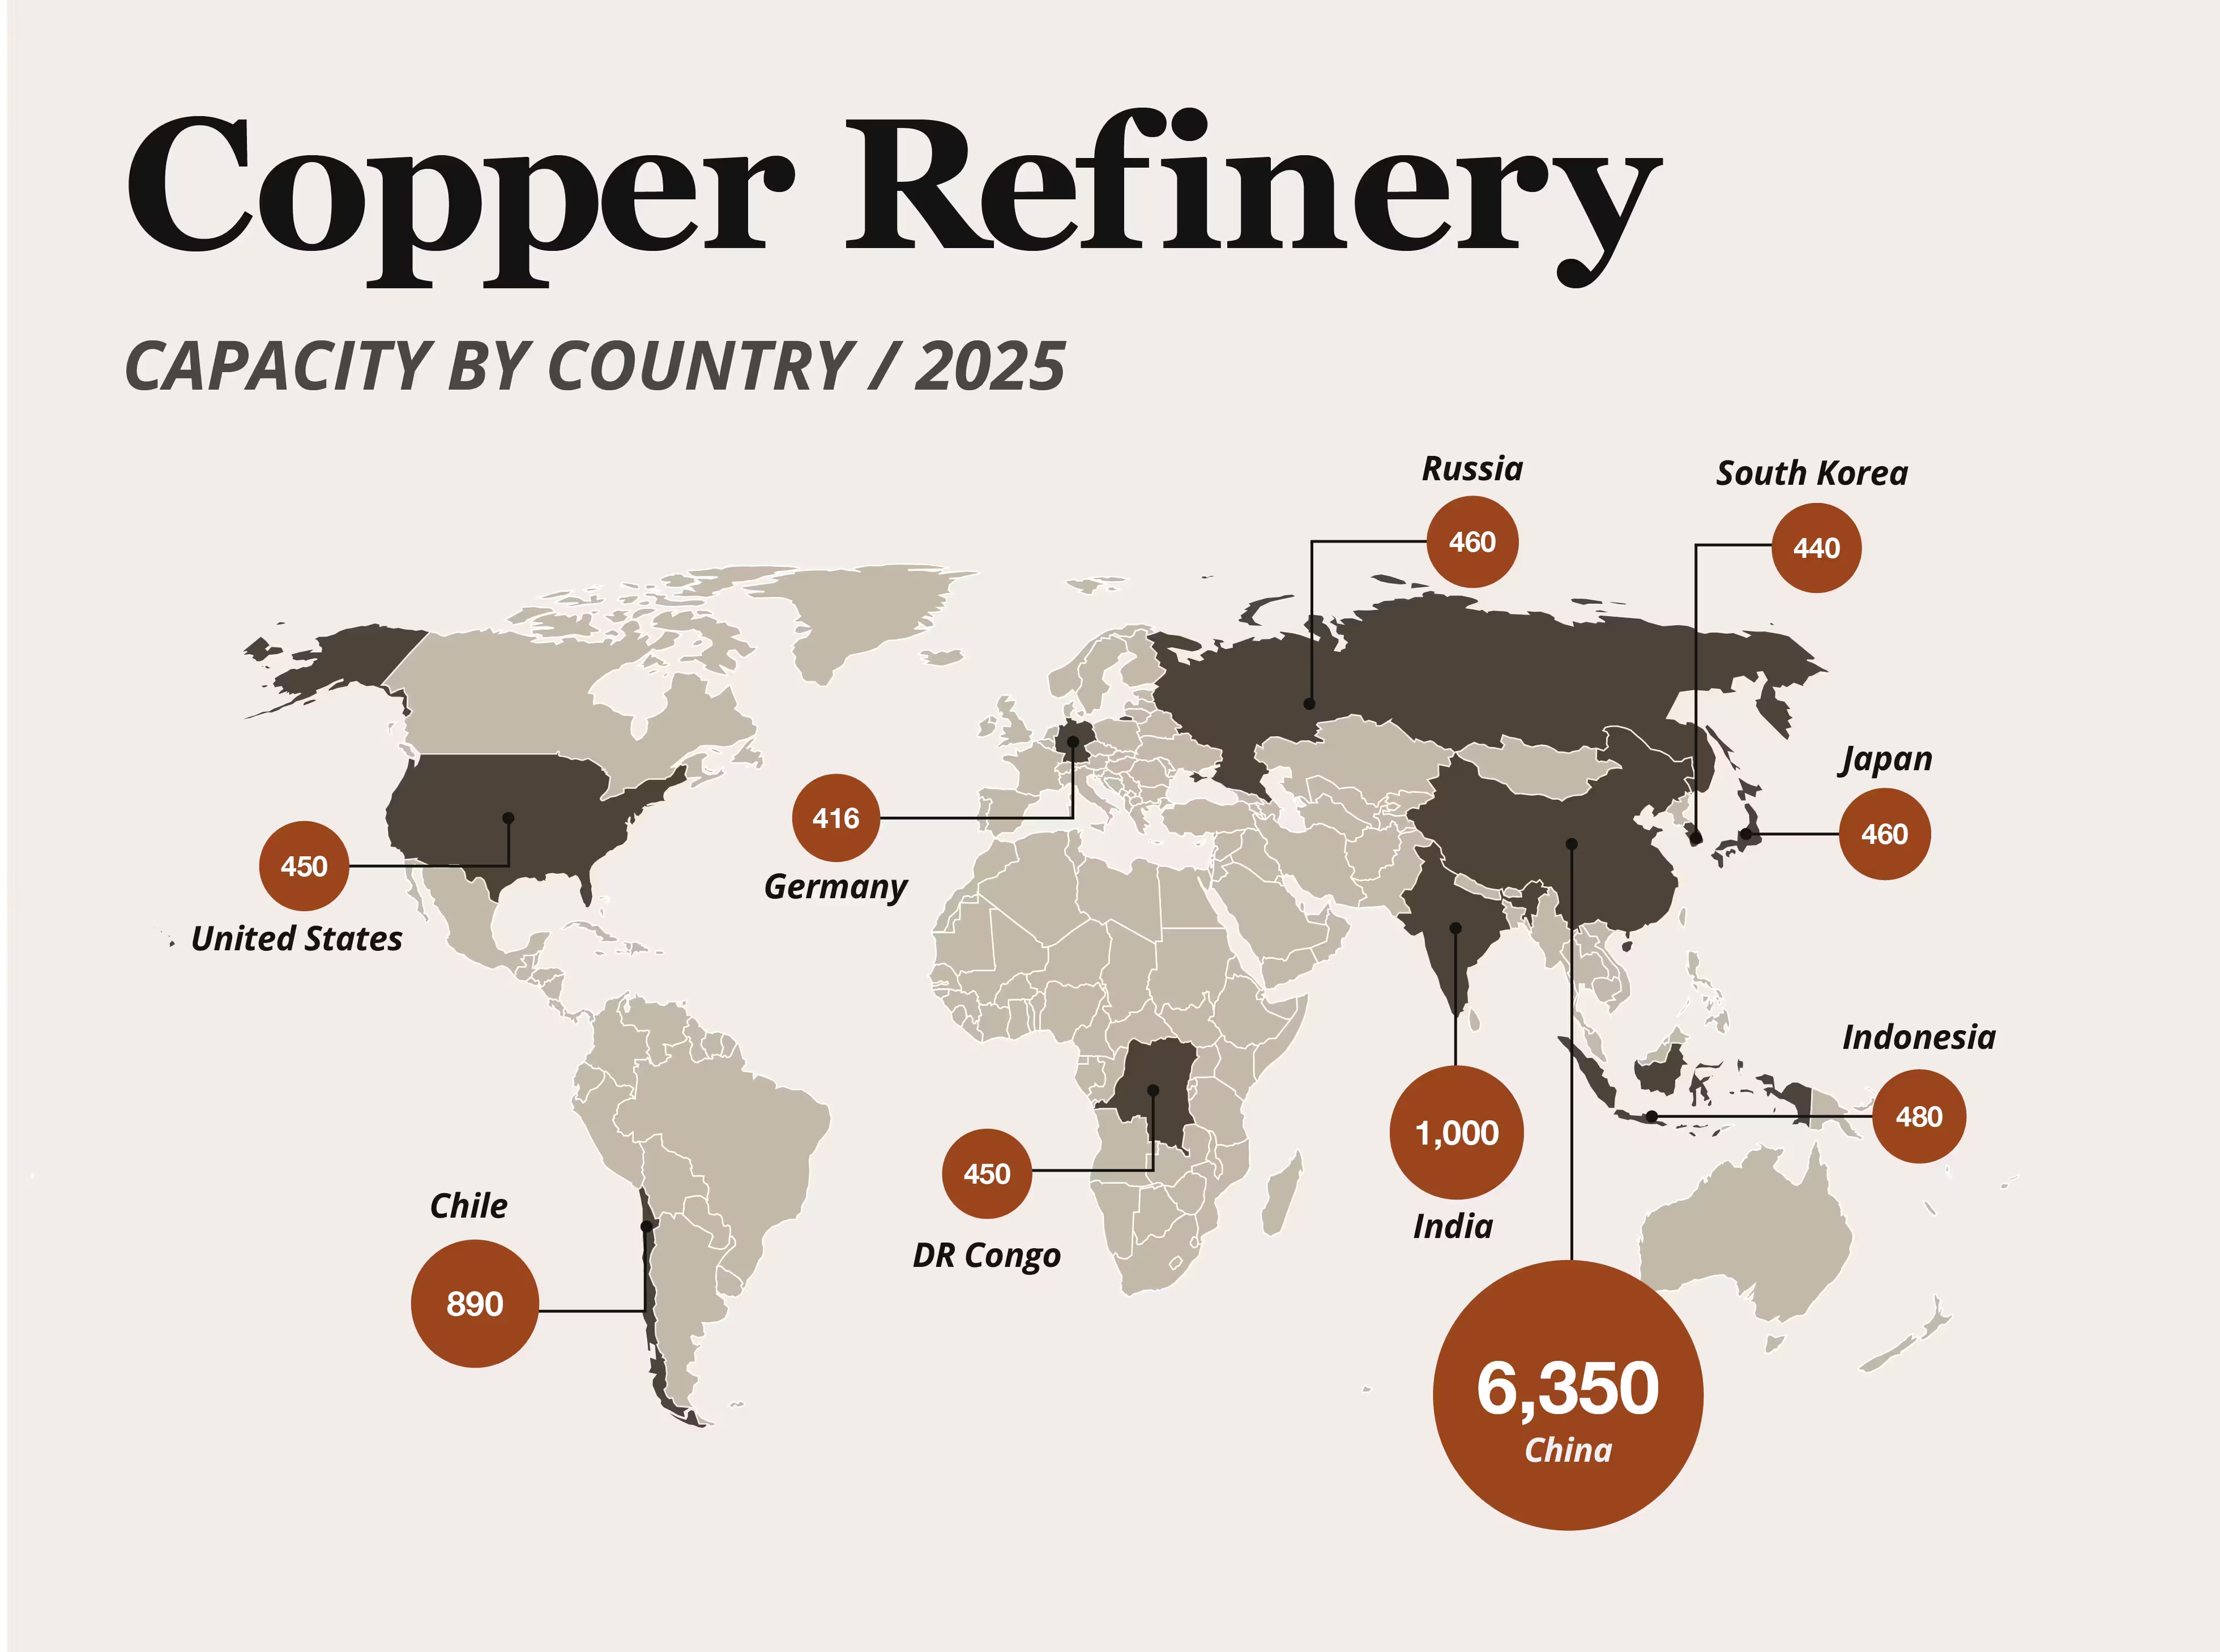
China Holds 56% of the Capacity at the World's 21 Largest Copper Refineries
China Holds 56% of the Capacity at the World's 21 Largest Copper Refineries
Indonesia's circle on the map above stands for a single plant: the Manyar refinery in East Java, operated by PT Freeport Indonesia, with 480,000 tonnes a year of capacity, according to the International Copper Study Group. It has been shut since the fourth quarter of 2025, after a mudflow at the Grasberg mine cut off its concentrate supply, and is due to restart this month at below 30% of capacity.