Tungsten
October 28, 2025
3min
Tungsten
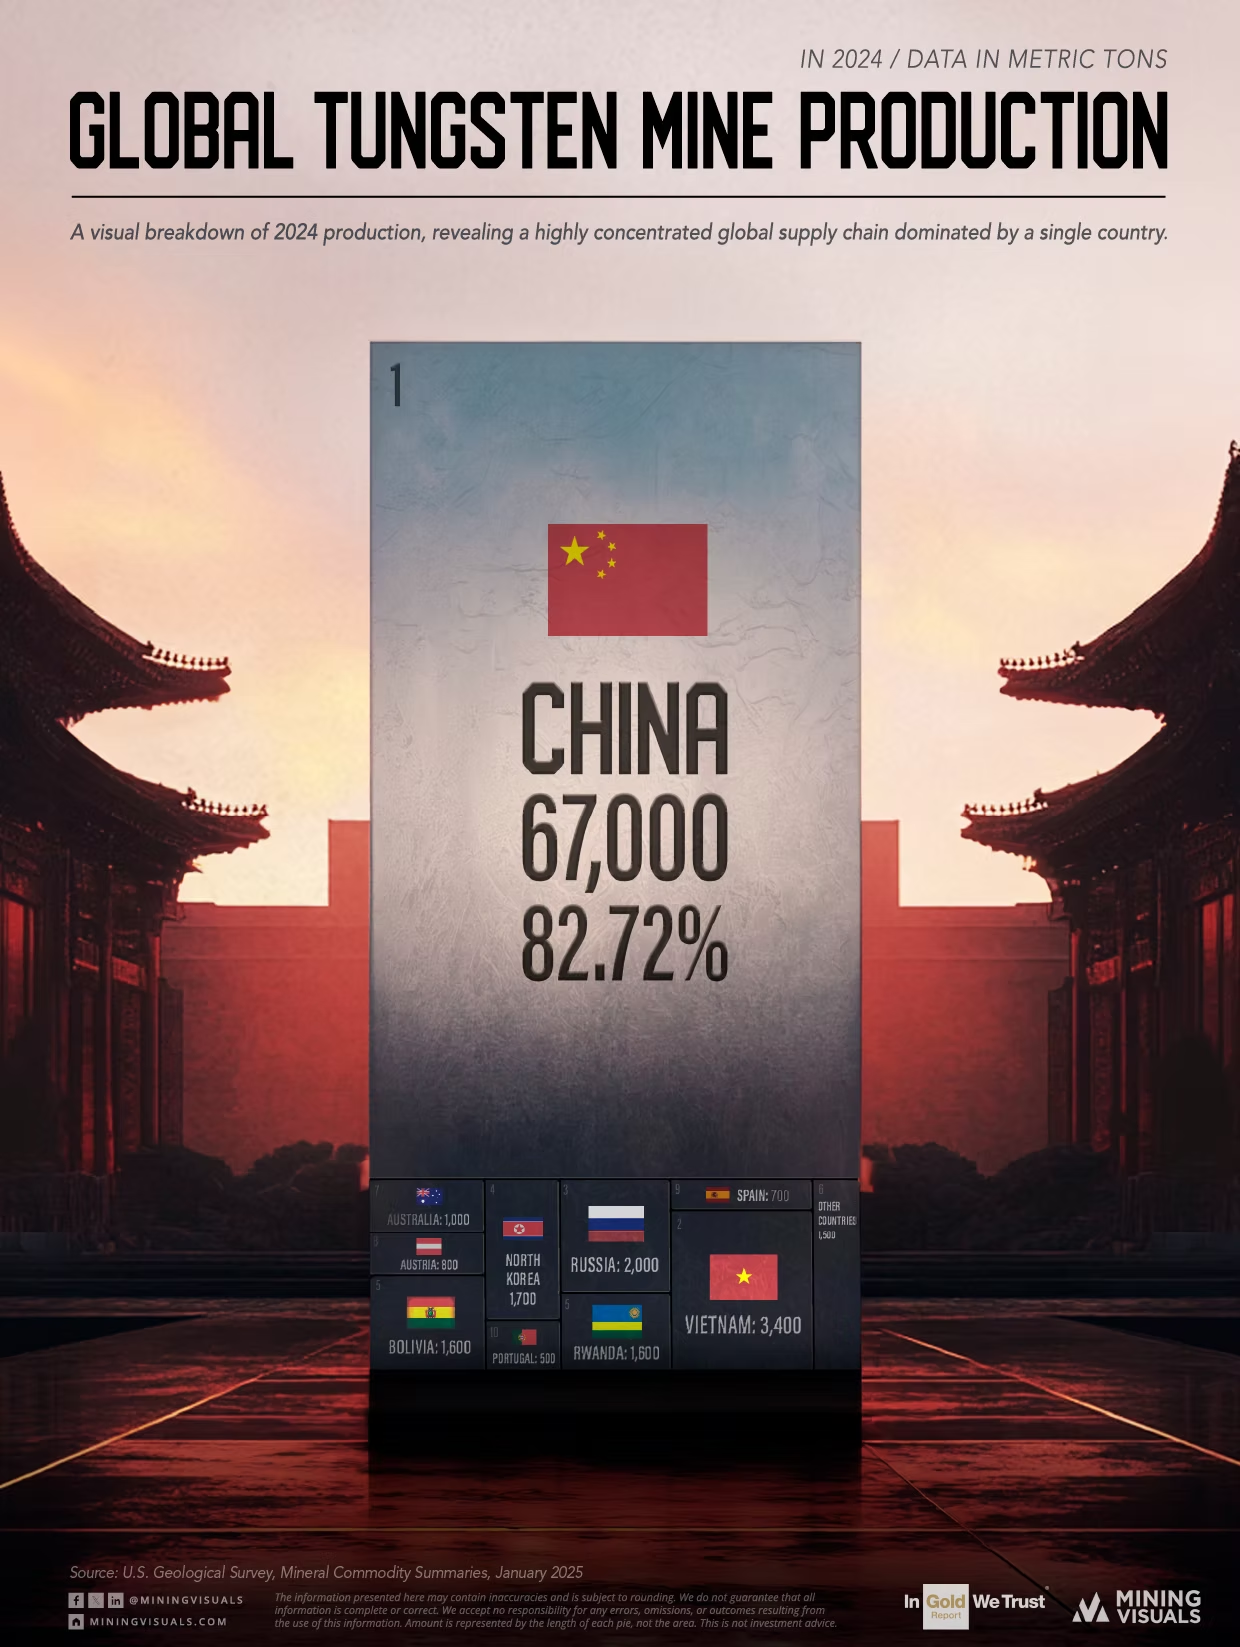

As the infographic above clearly illustrates, the global tungsten supply chain is one of the most concentrated in the world. Based on 2024 data from the U.S. Geological Survey, a single country—China—dominates the market, accounting for a staggering 83% of all global mine production.
This dominance places tungsten firmly on the critical minerals list for the United States, the EU, and other major economies. But what makes this metal so vital, and what are the implications of a supply chain this lopsided?
Tungsten is not a household name, but it is the hidden backbone of modern industry. Its unique properties make it virtually unsubstitutable in its key applications.
- Extreme Hardness: Tungsten's primary use (over 60%) is in the form of tungsten carbide (WC), a cermet with a hardness approaching that of a diamond. This makes it essential for cutting tools, mining drills, and construction equipment—the very tools used to build our infrastructure and extract other resources.
- Highest Melting Point: At 3,422°C, tungsten has the highest melting point of all metals. This makes it indispensable for high-temperature applications like welding electrodes, rocket engine nozzles, and heating elements in industrial furnaces.
- Extreme Density: With a density similar to gold, tungsten is also used for weights, counterweights, and vibration damping in aerospace and automotive applications.
- Strategic Importance: In defense, tungsten's hardness and density make it a key component in armor-piercing ammunition and other high-performance military hardware.
The 2024 Production Landscape
The 2024 data reveals the extent of this supply concentration. Of the 80,000 metric tons produced globally:
- China was responsible for 67,000 tons (83%).
- Vietnam was a distant second, producing 3,400 tons.
- Russia came in third with 2,000 tons.
The rest of the world's production is fragmented among a handful of smaller players, including Rwanda (1,600 tons), North Korea (1,100 tons), and Bolivia (1,000 tons). Production in Western-aligned nations is minimal, with Australia, Austria, Spain, and Portugal collectively producing just 2,800 tons—only 4% of China's output.
The Geopolitical Equation: Production vs. Reserves
The situation is further complicated when looking at reserves. While production is overwhelmingly concentrated, the tungsten in the ground is slightly more dispersed.
According to the USGS, China holds approximately 2.4 million tons of tungsten reserves, which is about 52% of the global total of 4.6 million tons.
This data reveals a critical insight: China is not just the dominant holder of tungsten; it is the dominant producer by a much wider margin. This strategic position gives it significant leverage over global prices and supply availability.
This dependency has become a major concern for Western governments. The concentration of production, especially for a metal essential to defense and high-tech manufacturing, creates a significant supply chain vulnerability. This is why nations in Europe and North America have made it a priority to "de-risk" by identifying and supporting the development of new tungsten projects outside of China.
However, as the infographic makes clear, closing an 83% production gap is a monumental challenge that will take decades, significant capital, and a fundamental realignment of the global supply chain.
Source: All production and reserve data in this article is sourced from the U.S. Geological Survey (USGS) Mineral Commodity Summaries 2025, which provides estimated data for the 2024 calendar year. Market share percentages were calculated based on this data. Information on tungsten's applications and properties is also derived from the same USGS report.


Explore More
View All

Behind Tin's 2026 Record High
Behind Tin's 2026 Record High
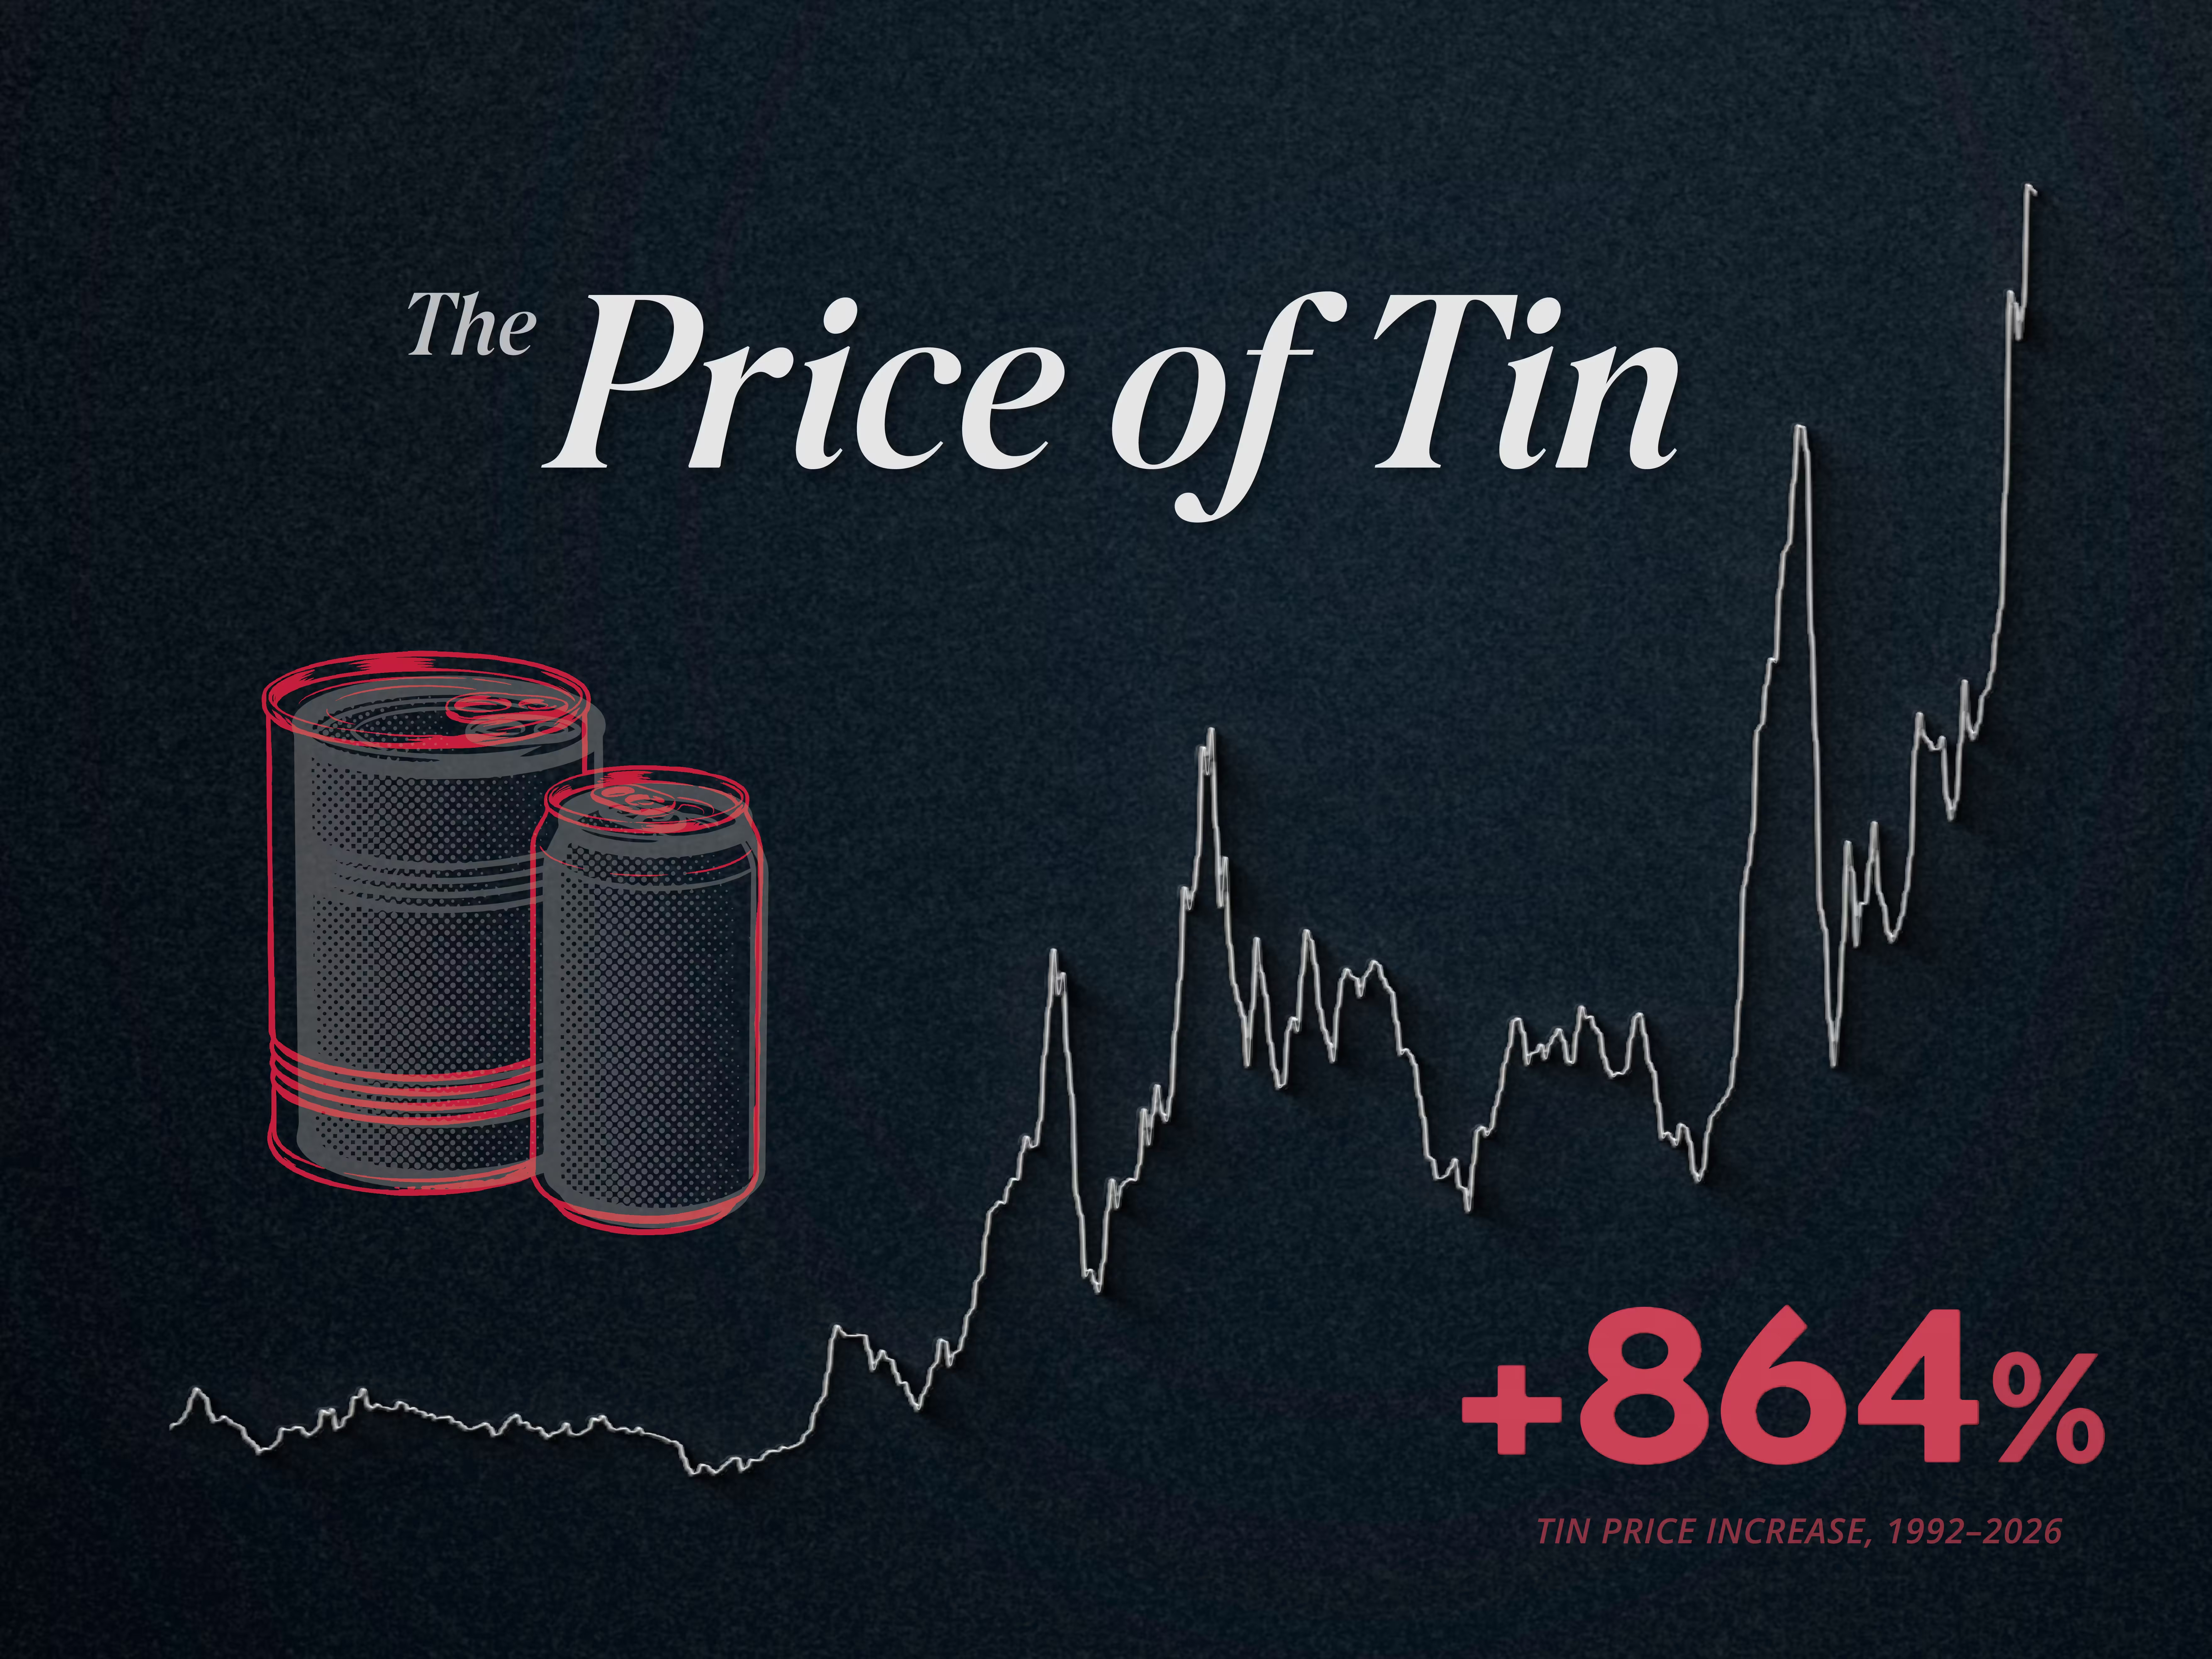
In January 2026, the London Metal Exchange three-month tin contract closed at US$53,462 a tonne, a nominal all-time high that surpassed the March 2022 peak, and it has traded near those levels since. The puzzle is that there is no shortage of tin today: exchange inventories actually rose as the price climbed, rather than being drawn down. Two very different things are holding the price up. The first is short-term: a wave of investor buying, which the industry says drove the January jump. The second is long-term: on current forecasts, the world will not mine enough tin to meet demand later this decade, a gap already projected before the rally began and expected to persist after it fades. The lasting story is that forecast shortfall, not the spike.
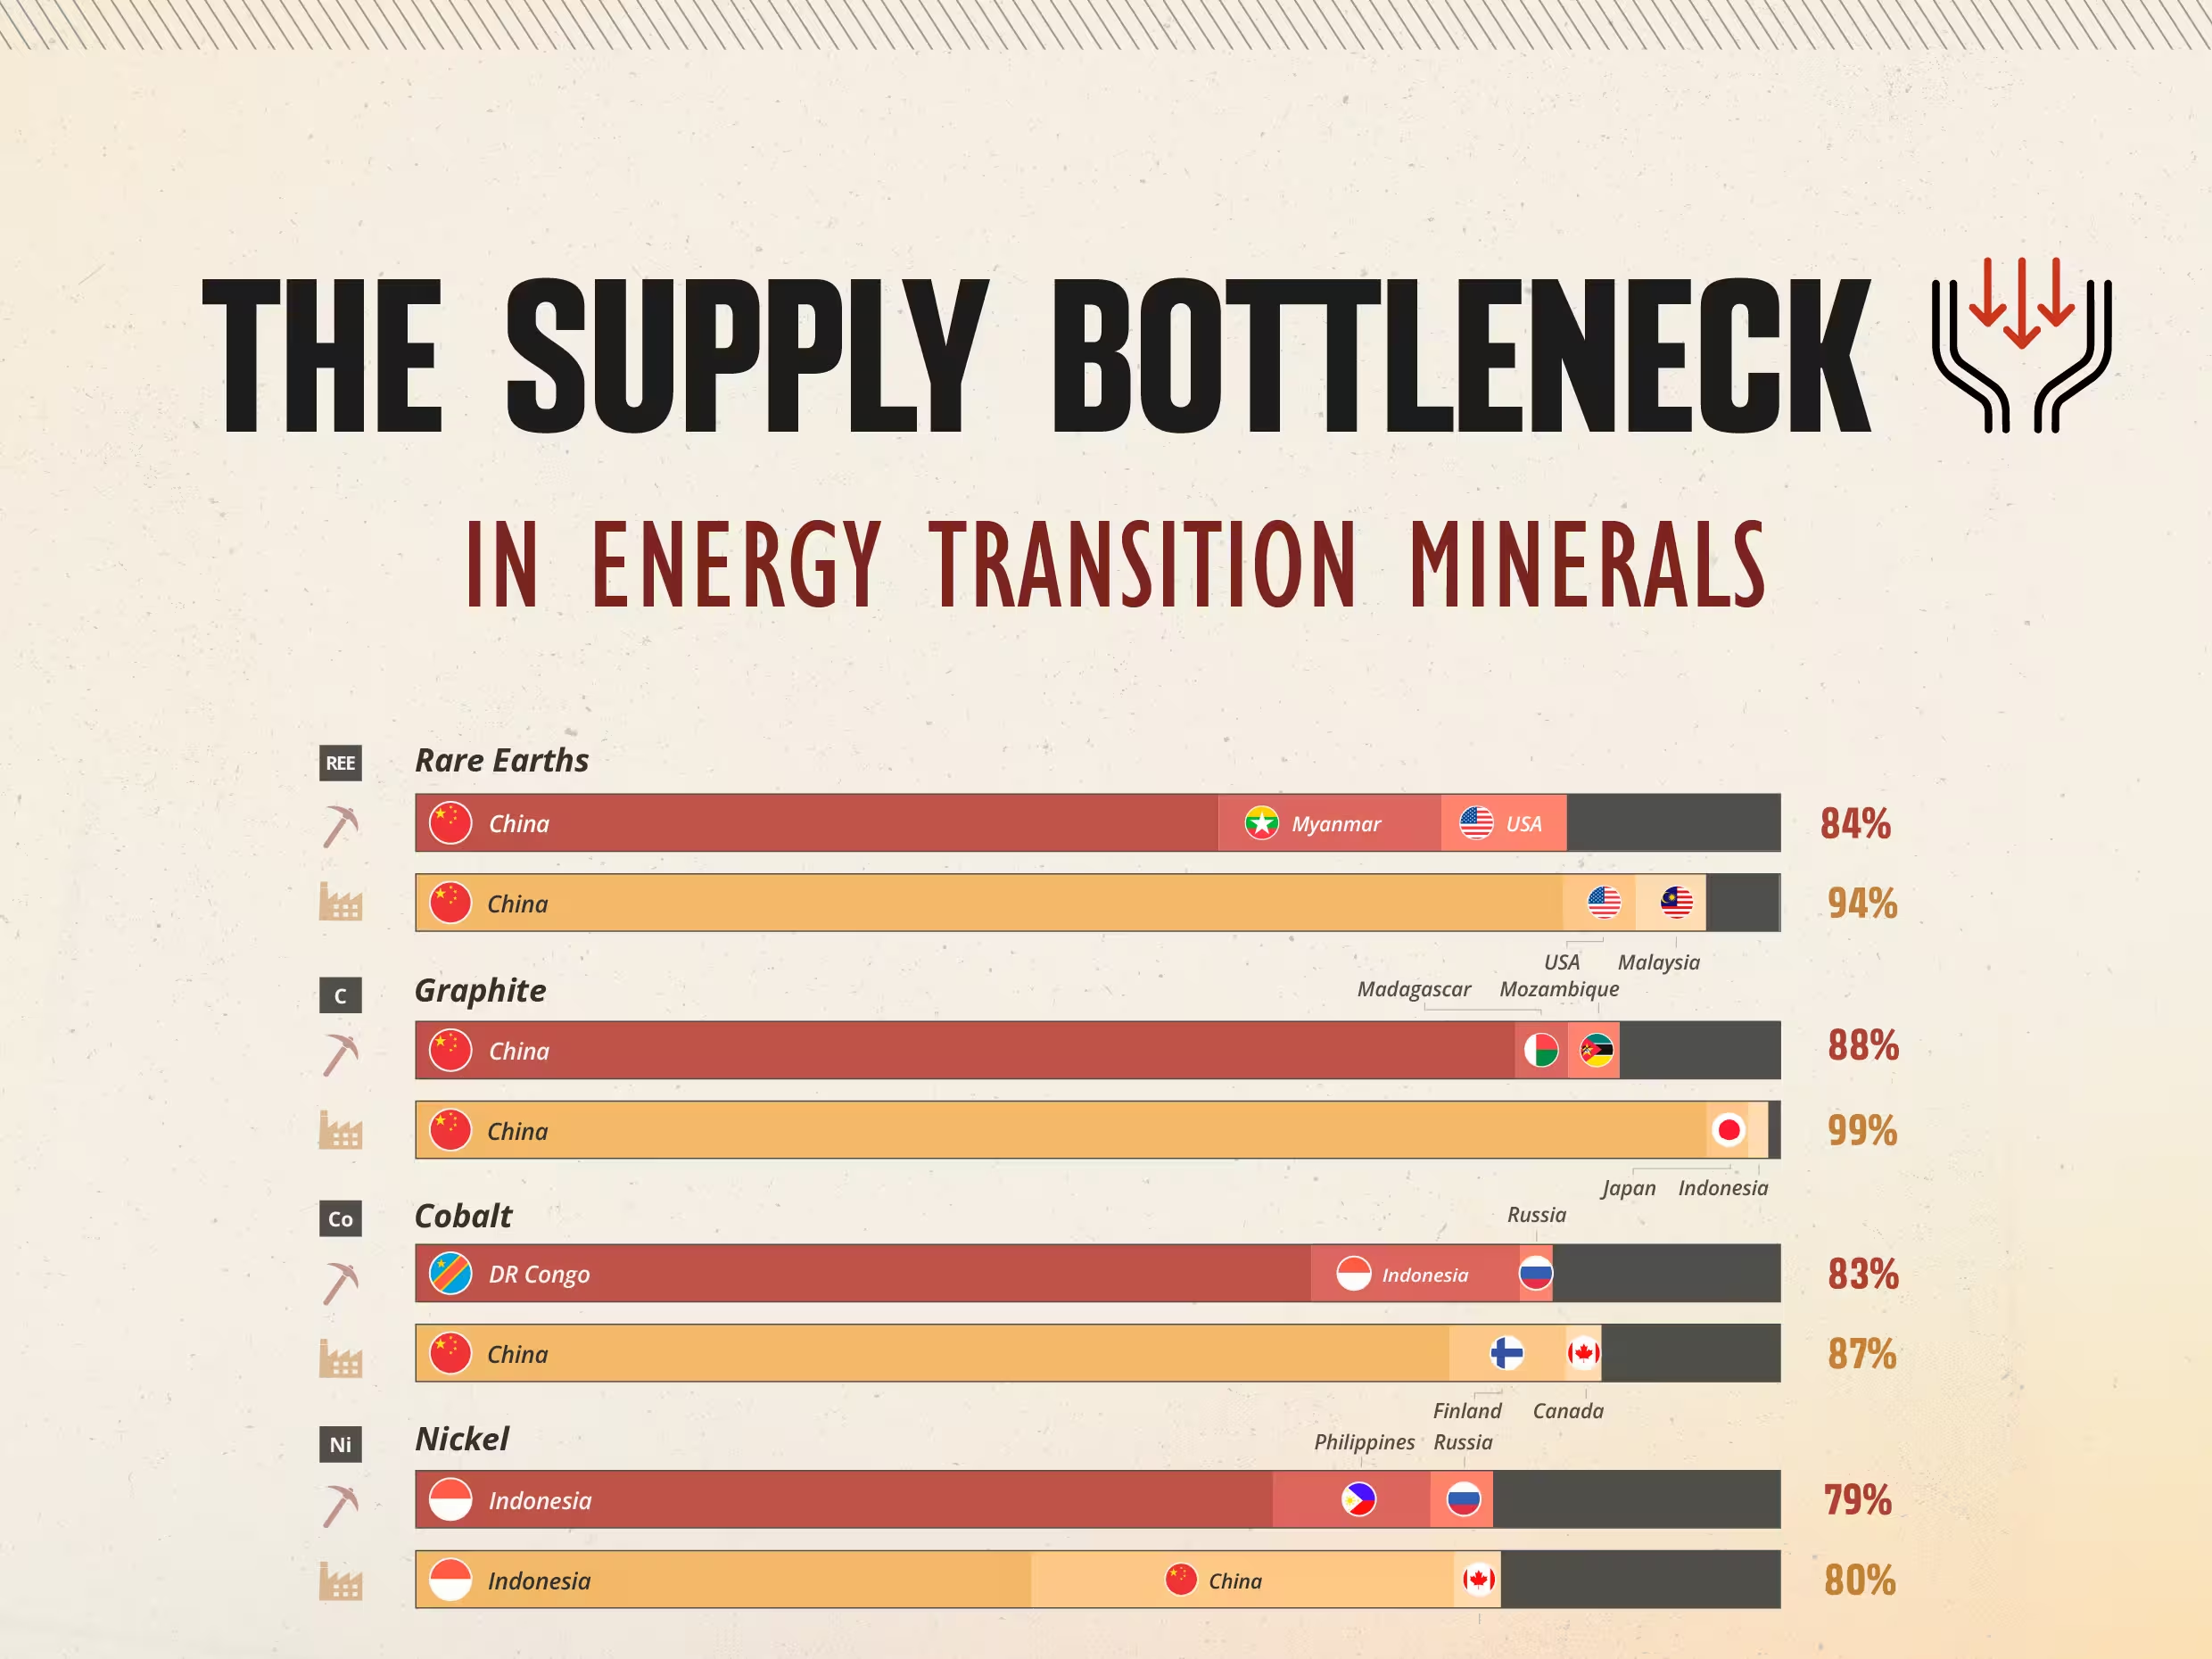
A Few Countries Control the World's Energy Transition Minerals
A Few Countries Control the World's Energy Transition Minerals
When China restricted exports of seven heavy rare earth elements and their magnets on 4 April 2025, factories felt it within weeks. Carmakers in the United States, Europe and Japan reported disruptions serious enough to cut output or halt production lines, and Washington negotiated a 90-day truce to restart the flow.
The Age of Giants: How Mining Shovels Grew, Peaked, and Deliberately Shrank
The Age of Giants: How Mining Shovels Grew, Peaked, and Deliberately Shrank
For four decades, the American coalfields hosted an engineering arms race measured in cubic metres of bucket. It ended not with a bigger machine, but with a deliberate retreat. The single largest mobile land machine ever built, the Marion 6360 "Captain," was commissioned in 1965 and destroyed by fire in 1991. No shovel has approached its scale since, and the machines that replaced it were smaller by design.
Where Indium Goes: The Metal Behind Screens, Chips, and Solar
Where Indium Goes: The Metal Behind Screens, Chips, and Solar
Indium is one of the metals you never see but use constantly. As indium tin oxide, it forms the transparent conductive coating on nearly every LCD and touchscreen, and that single application still accounts for most global consumption, according to the USGS. But the metal's role is broadening. Its compounds now sit inside the high-speed optical chips that route data through AI data centers, a shift that has turned a quiet, display-driven material into one buyers watch closely, especially as China refines about 70% of it and has begun tightening the flow.